
Granite Real Estate Investment Trust (TSX:GRT.UN) Lifts Distribution Target, Is It Still 26% Below Fair Value?
Granite Real Estate Investment Trust (TSX:GRT.UN) has drawn fresh attention after reporting higher third quarter and year to date revenue and net income, alongside a planned unit split and an increased targeted distribution.
Granite Real Estate Investment Trust’s recent earnings update, higher targeted distribution and planned three for one unit split come against a backdrop of mixed trading. The unit price is at CA$87.49 after a 1 day share price return of 1.98% and a 30 day share price return of 4.24%, while the 90 day share price return declined 3.99% and the 1 year total shareholder return sits at 18.19%. This suggests shorter term momentum has cooled compared with the stronger gains investors have seen over the past year.
Spot other income-focused real estate trusts riding similar momentum by scanning our hand picked 3 dividend fortresses alongside Granite Real Estate Investment Trust’s latest moves.
Granite Real Estate Investment Trust now combines higher revenue, more net income and a richer targeted distribution with a unit price that has already climbed over the past year. Does that fundamental strength still translate into a reasonable valuation today?
Price-to-Earnings of 14.5x: Is it justified?
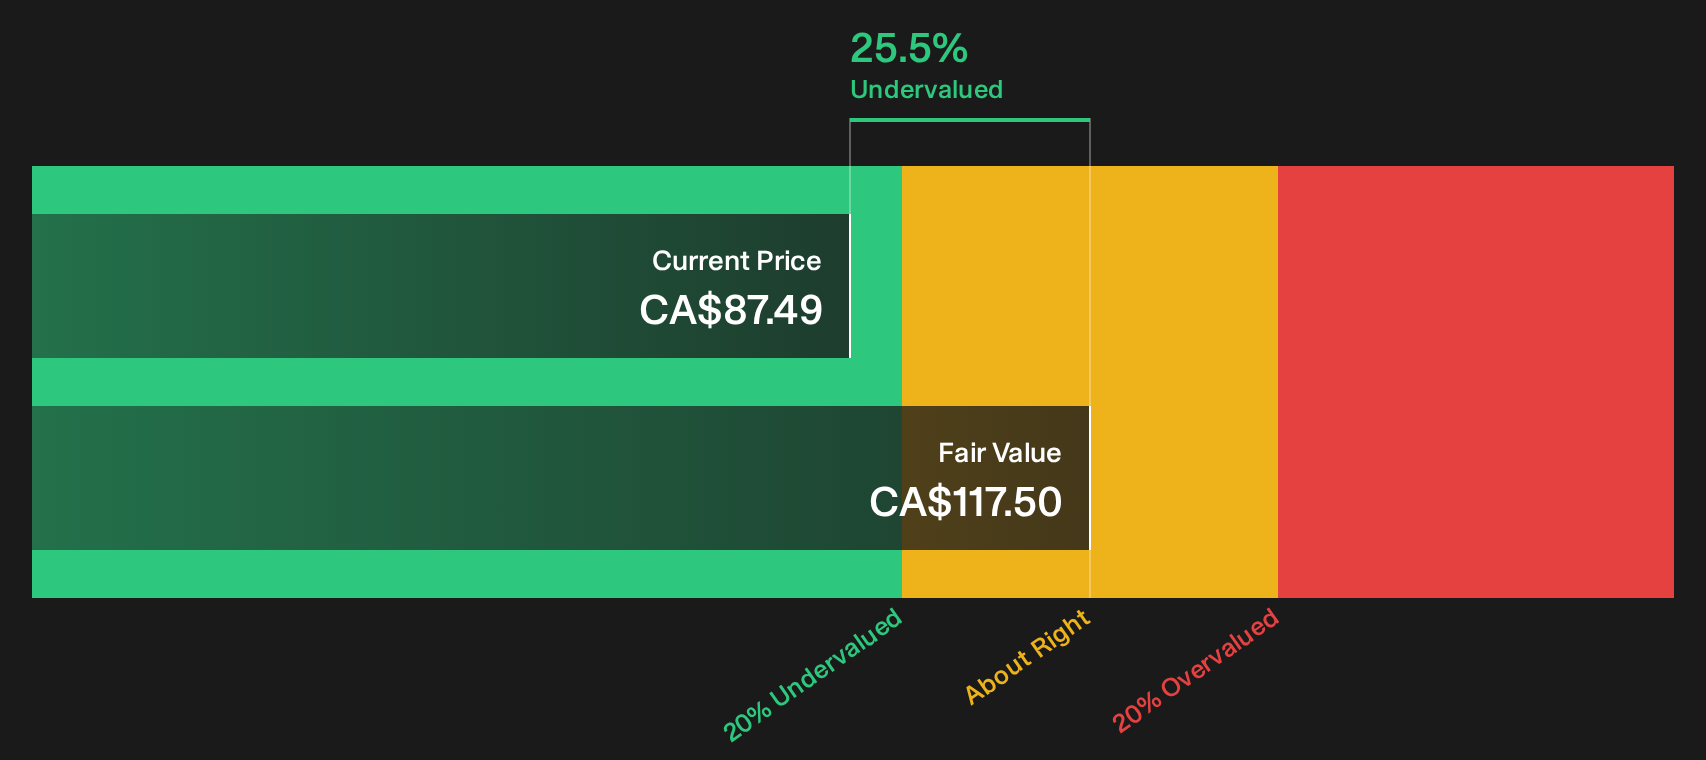
Granite Real Estate Investment Trust trades on a P/E ratio of 14.5x, with the last close at CA$87.49, while our cash flow model points to a future value of CA$117.50 that is 25.5% higher than the current price.
The P/E ratio compares what investors pay today for each dollar of current earnings. For an industrial REIT like Granite Real Estate Investment Trust, it gives a quick sense of how the market is weighing income from its logistics and warehouse portfolio against other options in the sector.
Granite Real Estate Investment Trust is described as expensive relative to the peer average P/E of 13.1x. It also looks rich when set against an estimated fair P/E of 11.9x. That fair ratio is a level the market could move towards if sentiment or growth expectations cool, even though the trust is considered good value against the wider Global Industrial REITs group, where the average multiple is 15.7x.
Explore the SWS fair ratio for Granite Real Estate Investment Trust.
Result: Price-to-Earnings of 14.5x (OVERVALUED)
Still, the recent share price pullback over 90 days and any shift in demand for logistics or industrial space could challenge the current valuation story for Granite Real Estate Investment Trust.
Find out about the key risks to this Granite Real Estate Investment Trust narrative.
Another View on Granite Real Estate Investment Trust’s Value
The SWS DCF model points in the opposite direction to the P/E signal. On this framework, Granite Real Estate Investment Trust at CA$87.49 trades about 25.5% below an estimated future cash flow value of CA$117.50. That gap looks like a potential opportunity, but only if the cash flow assumptions hold up over time.
Before leaning too heavily on either metric, it helps to understand how a cash flow model weighs long term rents, financing costs and reinvestment choices for an industrial REIT like this one. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Granite Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Granite Real Estate Investment Trust’s value can feel confusing, so move fast, review the numbers yourself, and pressure test the story against your own expectations using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Granite Real Estate Investment Trust?
If Granite Real Estate Investment Trust has sharpened your focus on value and income, do not stop here. Broader opportunities often emerge where fewer people are looking.
- Target stronger upside potential by reviewing carefully selected value opportunities in the 7 high quality undervalued stocks that pair quality fundamentals with attractive pricing.
- Prioritise resilience in tougher markets by scanning the list of solid balance sheet and fundamentals (6 results) for businesses with robust finances that can better support long term plans.
- Hunt for lesser known potential by tracking the 9 high quality undiscovered gems where solid fundamentals have not yet drawn much attention from the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com