
Chartwell Retirement Residences (TSX:CSH.UN) Could Be 19% Undervalued After Returning To Profit
Chartwell Retirement Residences (TSX:CSH.UN) just posted third quarter 2026 earnings, reporting CAD 324.98 million in revenue and CAD 114.96 million in net income, a shift from a net loss a year earlier.
At a share price of CA$21.0, Chartwell Retirement Residences has posted a 30 day share price return of 7.64% and a 1 year total shareholder return of 9.43%. The 3 year total shareholder return above 100% points to momentum that long term holders will likely be watching closely as the market reacts to its swing back to profitability.
Scan beyond Chartwell Retirement Residences and see how other income-focused operators with recent earnings momentum stack up using our curated screener of 3 dividend fortresses
Chartwell Retirement Residences has just swung back into profit and the unit price has already moved. Is this a reasonable entry now, or does waiting for a cheaper pullback make more sense once valuation is on the table?
Most Popular Narrative: 19% Undervalued
Compared with the last close at CA$21.0, the analyst consensus Narrative on Simply Wall St points to a fair value of about CA$25.86. This implies the market price is lagging the Narrative view and puts Chartwell Retirement Residences in potential discount territory based on those assumptions.
The main thing that has to go right is that Chartwell Retirement Residences continues to recycle capital into newer, higher yielding core assets while controlling operating costs and dilution so that occupancy and NOI targets translate into sustained per unit earnings power.
The current valuation implies investors are pricing Chartwell Retirement Residences as if equity issuance, dilution concerns, and sector risks will limit how much of the recent operating momentum and portfolio upgrade shows up in the long term unit price.
See why 20 investors see Chartwell Retirement Residences as 19% undervalued.
Result: Fair Value of CA$25.86 (UNDERVALUED)
Still, Chartwell Retirement Residences relies heavily on ongoing equity issuance, and any repeat of weak per unit earnings despite FFO strength could quickly cool that undervaluation story.
Find out about the key risks to this Chartwell Retirement Residences narrative.
Another View: Chartwell Retirement Residences Looks Expensive On Earnings
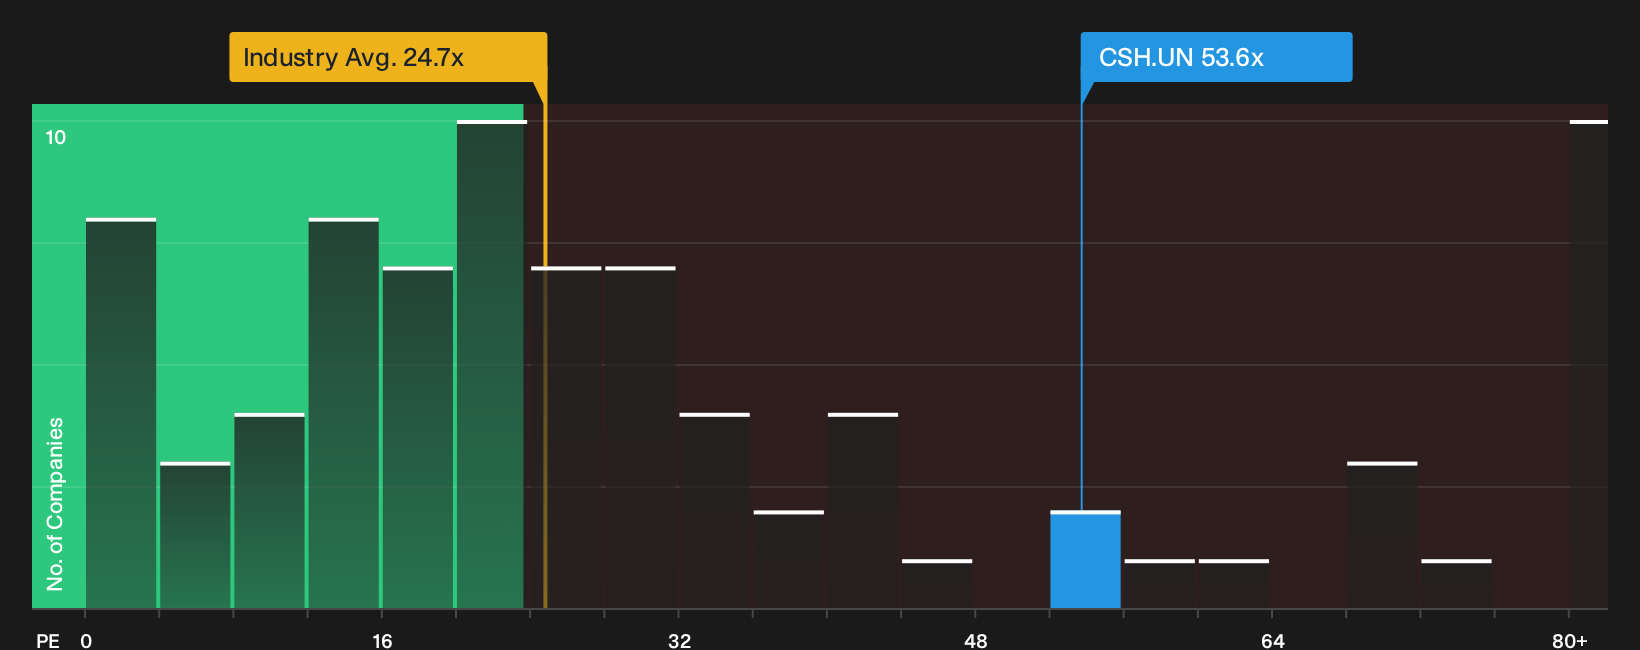
The fair value narrative for Chartwell Retirement Residences points to upside, yet the current P/E of 53.6x tells a different story. That multiple is more than double the North American Healthcare industry at 24.8x, the peer average at 25.4x, and well above a fair ratio of 20.8x. That gap increases the risk that sentiment, not cash flows, is doing much of the work here, so how comfortable are you paying that kind of premium for a seniors housing REIT?
For investors who prefer to stress test that premium using earnings based metrics, it can help to step back and see how this pricing compares more broadly across the sector See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mixed tone around Chartwell Retirement Residences, with both upside potential and clear pressure points, makes this a moment to move fast and test the numbers yourself. To weigh those cross currents properly, start by lining up the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Chartwell Retirement Residences?
If Chartwell Retirement Residences has sparked fresh thinking, do not stop with a single ticker. Broader idea hunting can sharpen your watchlist and highlight better fits.
- Target resilient balance sheets and steadier cash generation by scanning our curated list of solid balance sheet and fundamentals (6 results) for ideas that may hold up across different market conditions.
- Hunt for potential mispricings by reviewing the 7 high quality undervalued stocks that combine quality fundamentals with prices that lag underlying business performance.
- Build income focused watchlists by checking the 3 dividend fortresses that pair higher yields with financial profiles designed to support ongoing distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com