
Why Frontdoor (FTDR) Could Be 4% Undervalued Following Its Finance Hire And Upbeat Guidance
Frontdoor (FTDR) just refreshed its finance bench, appointing Mary Hopkins as Controller and Chief Accounting Officer shortly after posting higher third quarter sales and net income and issuing more upbeat 2026 revenue guidance.
The reshuffle in Frontdoor’s finance team comes after a strong run in the shares, with a 30 day share price return of 26.49%, a year to date gain of 69.42%, and a 1 year total shareholder return of 88.97%. This performance suggests momentum has been building as investors respond to higher recent profits, upbeat 2026 revenue guidance, and an active buyback program.
Scan how other home service and consumer stocks are reacting to similar earnings beats and buybacks by checking the 32 high quality undervalued stocks that may be drawing fresh attention.
Frontdoor’s share price has sprinted ahead while both intrinsic value estimates and analyst targets still sit higher. Is the gap a genuine margin of safety or a signal that the market smells risk?
Most Popular Narrative: 4% Undervalued
Frontdoor’s last close at $96.64 sits below the analyst consensus Narrative fair value of $100.80, which is built on detailed earnings and cash flow forecasts in the analyst consensus Narrative on Simply Wall St. That framework leans heavily on sustained execution in the core warranty and newer non warranty services.
Expansion of non warranty offerings, with the HVAC upgrade program scaling from US$13 million to an expected US$170 million of annual revenue in four years and non warranty revenue growing more than 19% year over year in early 2026, provides Frontdoor with a template to add further trades and increase total revenue and EBITDA.
See why 8 investors see Frontdoor as 4% undervalued.
Result: Fair Value of $100.80 (UNDERVALUED)
Still, the Frontdoor narrative starts to fray if home warranty member growth stalls again, or if heavier discounting and marketing spend compress margins.
Find out about the key risks to this Frontdoor narrative.
Another Look At Frontdoor’s Valuation
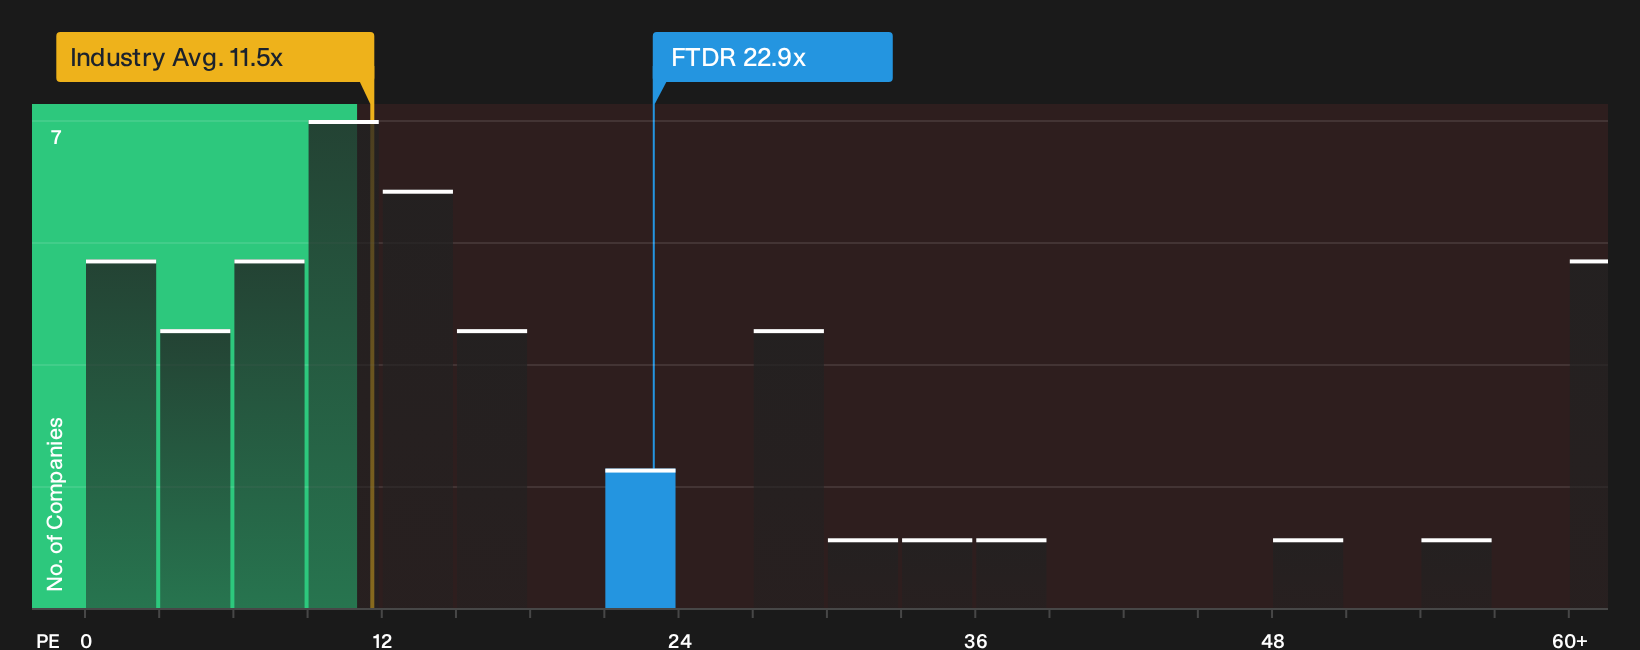
On simple earnings yardsticks, Frontdoor tells a different story. The stock trades on a P/E of 22.9x, while the fair ratio is 19.6x and peers average 18.7x. The wider gap versus the US Consumer Services sector at 11.6x points to richer pricing. Is that premium comfort or risk for you?
To see how this earnings based view lines up with a fuller breakdown of assumptions, read through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals in the Frontdoor story so far. If you want to move quickly and decide where you stand, consider both sides of the ledger with the 3 key rewards and 1 important warning sign
Looking for more ideas beyond Frontdoor?
If Frontdoor has sharpened your focus on pricing, risk and quality, do not stop here. Broader opportunity often shows up where the market is not already looking.
- Pressure test your bargain hunting by scanning a curated 32 high quality undervalued stocks that blends strong fundamentals with prices that have not fully reflected them yet.
- Strengthen defense in your portfolio by reviewing a 31 resilient stocks with low risk scores built around resilient balance sheets and steadier business profiles.
- Hunt for potential future leaders early by checking a 20 high quality undiscovered gems that combines solid financial traits with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com