
Did Stronger Earnings Growth Just Shift Innodata (INOD) Investment Narrative?
- Innodata reported third quarter 2026 sales of US$95.62 million and net income of US$10.33 million, with higher basic and diluted earnings per share from continuing operations than a year earlier, and year to date figures also above the prior period.
- The combination of higher quarterly and nine month sales and earnings, along with stronger earnings per share, indicates that Innodata’s current project mix and cost structure are supporting improved profitability across the year, not just in a single reporting window.
- This article examines how Innodata’s stronger year to date earnings performance relates to the existing AI focused investment narrative for investors.
Scan beyond Innodata and see how other AI focused players with stronger sales and earnings trends line up in the 42 profitable AI stocks that aren't just burning cash.
Innodata Investment Narrative Recap
To own Innodata, you need to believe its AI focused data and evaluation work can keep turning large customer programs into durable earnings, even with project based contracts. The latest quarter shows higher sales and profits for both Q3 and the first nine months. That supports the analyst consensus narrative on Simply Wall St around scaling AI workloads into stronger earnings.
The near term swing factor is whether recent program momentum with large tech clients holds up and offsets revenue concentration risk. The biggest operational threat remains any pullback or insourcing from those key customers. That could quickly tighten revenue visibility even if the broader AI opportunity stays intact.
The Q3 and nine month report is the central announcement to focus on here. Sales of US$95.62 million and net income of US$10.33 million for the quarter, along with year to date earnings of US$39.64 million, show Innodata currently converting AI demand into profit. Basic and diluted EPS from continuing operations sit above the prior period.
For investors tracking catalysts, that result speaks directly to the themes in the analyst consensus narrative on Simply Wall St. It links ongoing AI infrastructure spending, more complex multimodal workloads and Innodata’s proprietary datasets and evaluation platforms to current execution. It also highlights the tension between higher profitability and customer concentration, valuation sensitivity and recent share price volatility.
Innodata's narrative points to forecast revenues of US$662.4 million and earnings of US$96.6 million by 2029. This implies analysts are baking in yearly revenue expansion of 23.7% and an earnings increase of about US$48.1 million from US$48.5 million today.
Uncover why Innodata's fair value indicates a 214% potential upside to its current price that could narrow quickly.
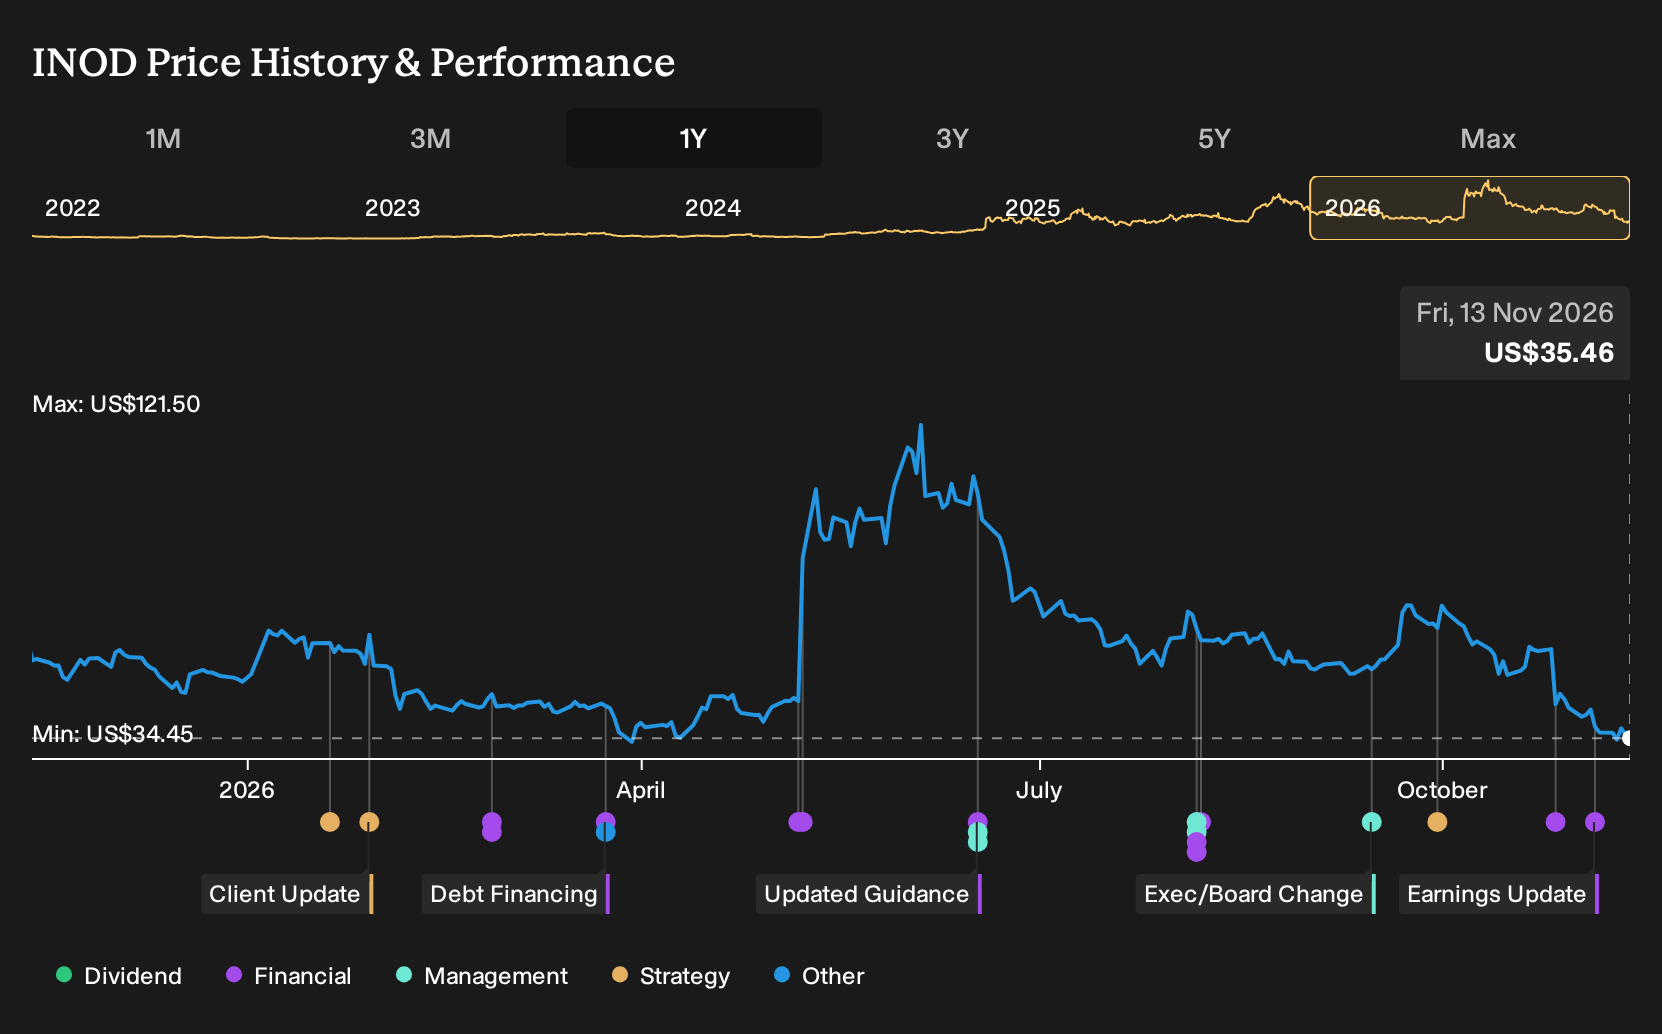
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Innodata’s IP based tools as a catalyst, not just its project work. Before this earnings release, the bullish camp was pencilling in revenue of about US$725.5 million and earnings near US$114.3 million by 2029. That is far higher than consensus and could shift again once this latest report fully filters into updated views.
Explore 4 other Innodata fair value estimates, including one that suggests as much as 295% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Innodata research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Innodata. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Innodata's overall financial health at a glance.
Looking For More Investment Ideas Beyond Innodata?
If Innodata has sharpened your interest in AI and data driven earnings stories, it can be useful to widen the lens and compare it with companies that show different combinations of value, quality and risk. The Simply Wall St Screener lets you scan for other stocks that align with the type of balance sheet strength, income potential, or mispricing you want to focus on next.
- If capital protection is your priority, start with companies that score well on financial resilience by reviewing a 31 resilient stocks with low risk scores.
- For investors who care most about getting paid while they wait, filter for income opportunities using a 6 dividend fortresses that have historically offered higher yields.
- Readers looking for mispriced opportunities with solid fundamentals can broaden their watchlist through a 32 high quality undervalued stocks that pass quantitative quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com