
What Is Driving Fresh Attention Around Elisa Oyj (HLSE:ELISA)?
Elisa Oyj (HLSE:ELISA) just tied its telecom infrastructure to Sensofusion’s drone detection tech through a new 50-50 joint venture, Masthead Oy, targeting security focused monitoring across Finland and Estonia.
Recent trading tells a mixed story for Elisa Oyj. The share price is at €34.14, with a 1-day share price return of 0.89% and a 7-day share price return of 0.41%. However, the 30-day share price return is down 4.15%, and year to date the share price return has fallen 8.03%, while total shareholder return over five years is down 19.86%. This suggests that despite initiatives such as the Masthead Oy joint venture, investors are still weighing longer term risks more heavily than short term catalysts.
Scan other security-focused telecom plays that are moving on similar catalysts with our curated list of 212 resilient stocks with low risk scores.
That security push has not stopped Elisa Oyj’s share price from drifting over recent years. The real puzzle now is whether today’s valuation leaves meaningful upside ahead or if most of the easy gains have already gone.
Most Popular Narrative: 10.8% Undervalued
The analyst fair value for Elisa Oyj sits at €38.26 versus the latest close at €34.14, which frames the current pricing as a discount according to the analyst consensus Narrative on Simply Wall St that aggregates forecasts and price targets rather than relying on a single viewpoint.
Ongoing fiber and 5G network investments, maintained within a disciplined 12 percent CapEx to sales range, position Elisa to capture structurally rising demand for high speed data and data center connectivity, underpinning long term revenue expansion and resilient EBITDA margins.
See why 8 investors see Elisa Oyj as 11% undervalued.
This fair value of €38.26 is based on analyst assumptions of modest revenue growth around 1.8% a year, relatively stable net profit margins near 17.2%, and a discount rate of 6.11% that reflects their view of Elisa Oyj’s risk profile and cash flow durability.
Those same models rely on earnings forecasts out to 2029 and a future P/E near 18.0x. This implies investors would be paying slightly more for each euro of expected earnings than the current European telecom peer multiple referenced in the Narrative, while also factoring in Elisa’s capital spending, cost savings program, and international software ambitions.
Result: Fair Value of €38.26 (UNDERVALUED)
Still, the analyst story around Elisa Oyj can unravel quickly if Finnish mobile price competition continues to erode pricing power or if international software projects face prolonged delays.
Find out about the key risks to this Elisa Oyj narrative.
Another Take On Elisa Oyj’s Value
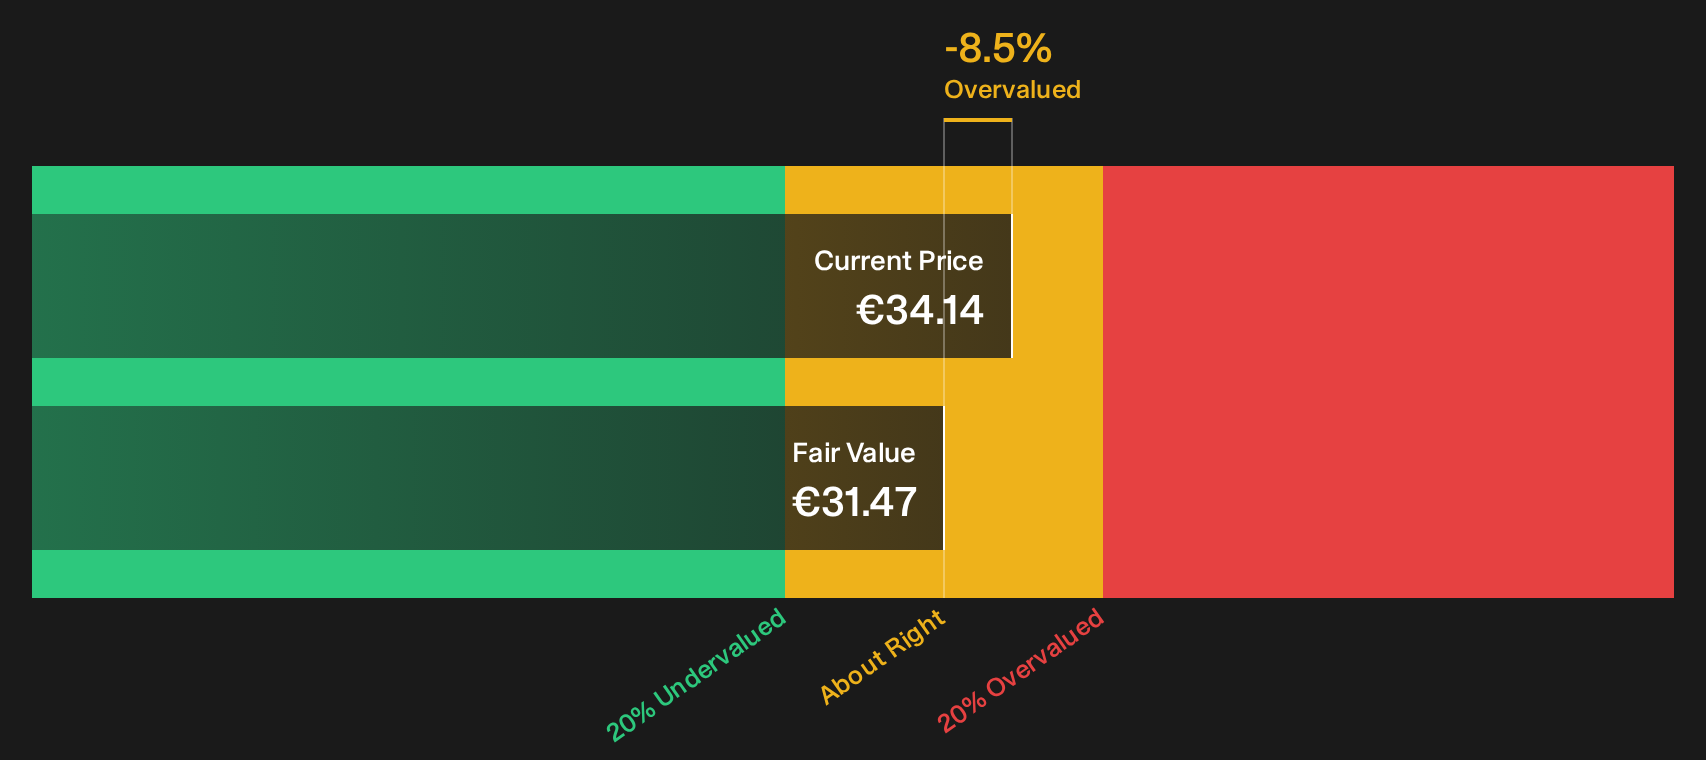
Analyst targets frame Elisa Oyj as roughly 10.8% undervalued, yet Simply Wall St’s DCF model paints a cooler picture. On that cash flow view, the shares at €34.14 sit above an estimated value of €31.47, which points to an overvalued outcome. Which lens feels closer to your own expectations for Elisa’s future cash generation?
For readers who want to see how the cash flow driven view is built line by line, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Elisa Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Elisa Oyj so far. If you want to move fast and shape your own view based on the data, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more Elisa Oyj style ideas?
If Elisa Oyj has sharpened your focus on risk, cash flows, and pricing, do not stop here. The next winners on your list might already be visible.
- Target resilient capital first and run your eye over a list of solid balance sheet and fundamentals (198 results) that can better withstand shocks when conditions get tougher.
- Hunt for value gaps and compare Elisa Oyj with a 199 high quality undervalued stocks where fundamentals and current pricing look out of sync.
- Build your watchlist around sturdier cash generators by scanning a 220 dividend fortresses that aims to combine yield with consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com