
How Investors Are Reacting To Pembina Pipeline (TSX:PPL) Strong Quarterly Earnings
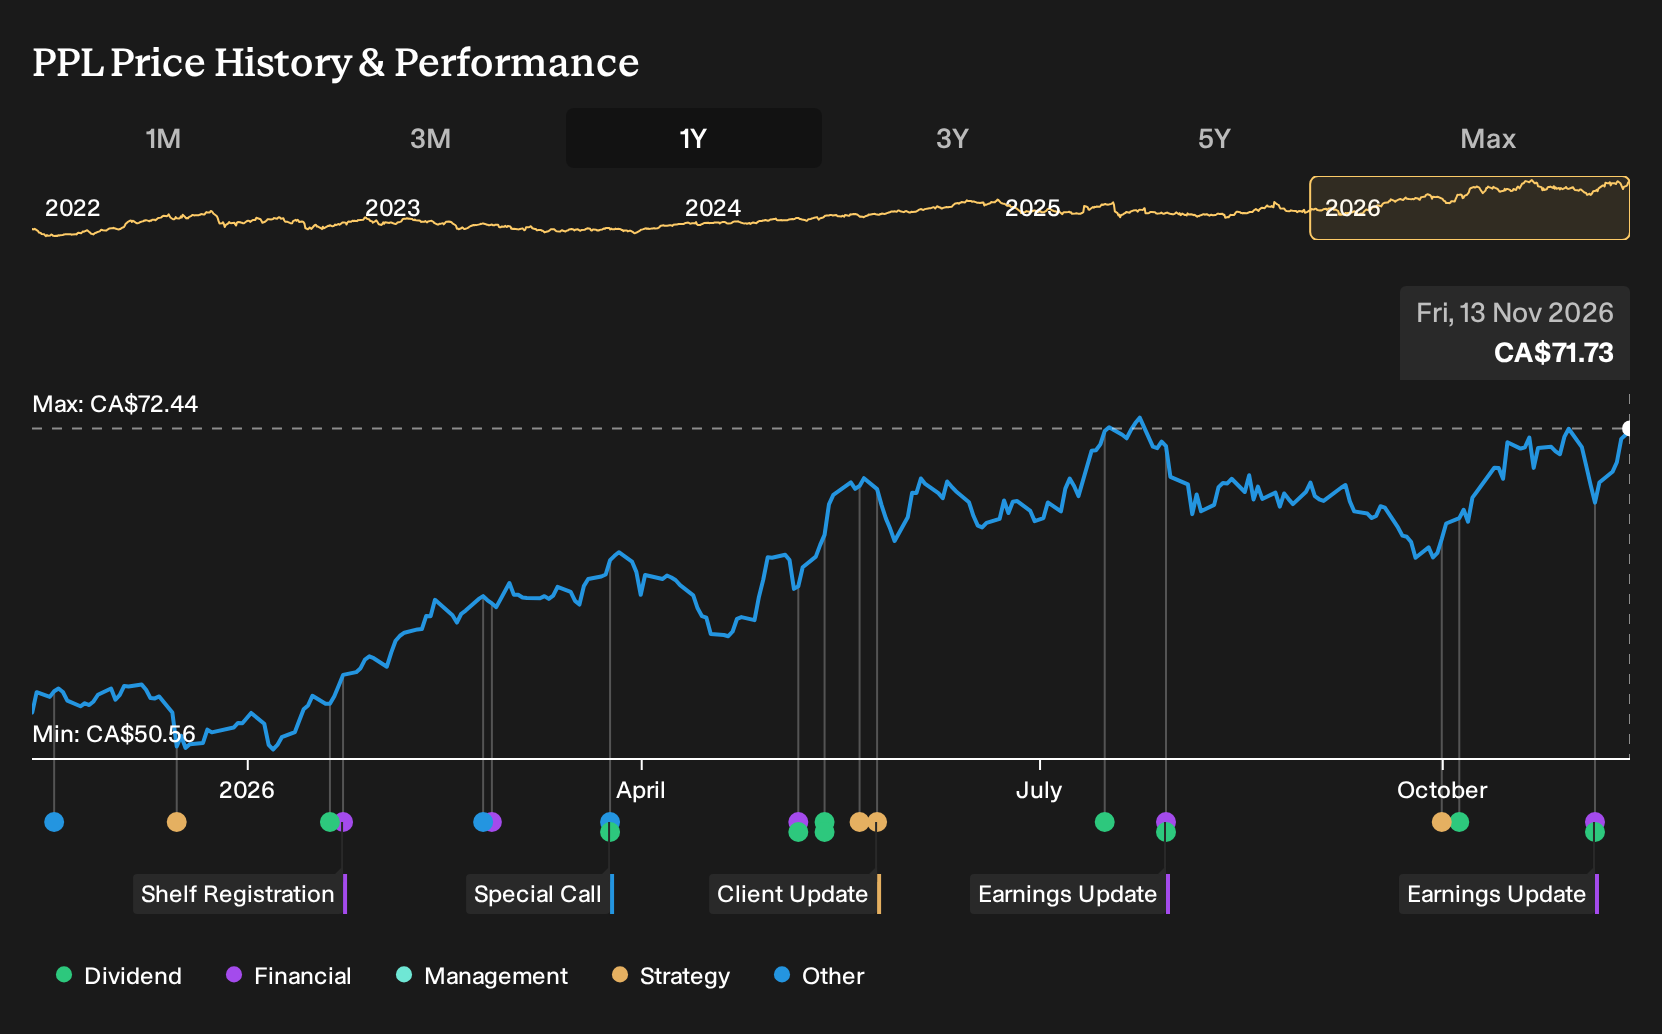
- Pembina Pipeline reported third quarter 2026 sales of C$2,179 million and net income of C$570 million, with basic EPS from continuing operations of C$0.92 compared with C$0.43 a year earlier.
- Stronger earnings and an affirmed fourth quarter 2026 dividend of C$0.735 per share indicate cash generation that supports Pembina Pipeline's existing capital commitments.
- The focus now shifts to how Pembina Pipeline's higher quarterly net income might influence the investment narrative built around large fee based projects.
Scan fee-based energy infrastructure plays that focus on cash flow resilience and income potential with our curated 3 dividend fortresses.
Pembina Pipeline Investment Narrative Recap
Pembina Pipeline suits investors who want exposure to fee based energy infrastructure where cash flow depends more on contracted volumes than commodity prices. The analyst consensus narrative on Simply Wall St leans on execution of large projects like Cedar LNG and Greenlight Electricity Centre to support future earnings. The third quarter 2026 results show higher sales and net income, which supports that thesis but do not remove execution or regulatory risk.
The key near term swing factor is still project delivery on time and within budget, especially in a year flagged as peak Cedar LNG spending. The biggest risk remains cost or schedule pressure on those builds, combined with toll resets on regulated pipelines that could pressure margins. This earnings print helps the story around funding capacity, although leverage and policy delays still need close monitoring.
The most relevant update alongside the earnings release is Pembina Pipeline's affirmed common share cash dividend of C$0.735 per share for the fourth quarter of 2026. A maintained payout, coming in the same period as stronger quarterly earnings, points to management prioritizing consistent shareholder income while funding a heavy capital program in projects like Cedar LNG and Greenlight.
For you as a holder or potential holder, that dividend decision feeds directly into the near term catalyst. Investors watching fee based cash flow and balance sheet flexibility can use the payout level as a quick check on how comfortable the board is with leverage and project spend. It also frames the risk that any future cost overruns, regulatory delays or weaker toll outcomes could eventually pressure both capital deployment and income policy.
Pembina Pipeline's current earnings are CA$1.7b and analysts forecast consensus earnings of CA$2.2b by 2029. This implies an earnings increase of about CA$500m, alongside a projected 3.5% yearly revenue growth rate and expected revenues of CA$8.8b in the same forecast year.
Uncover why Pembina Pipeline's fair value is in line with its current price.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from C$73 to about C$237 per share, which is a wide gap for the same Pembina Pipeline equity story. You can compare those retail views with toll reset risks and major project spending, then decide how much execution uncertainty you want to factor into the price.
Explore 2 other Pembina Pipeline fair value estimates, including one that suggests as much as 231% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment results tend to come from independent thinking, so consider trusting your own analysis.
- A great starting point for your Pembina Pipeline research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Pembina Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Pembina Pipeline's overall financial position.
Looking For More Investment Ideas Beyond Pembina Pipeline?
If the Pembina Pipeline story has sharpened your sense of what matters, broaden the opportunity set and pressure test your thesis across a wider field of companies using the Simply Wall St Screener.
- For investors who put downside first, stress test your capital preservation focus with 9 resilient stocks with low risk scores that align with tighter risk controls.
- If quality at a reasonable price is your priority, line up companies with stronger fundamentals against their share prices using the 7 high quality undervalued stocks as a starting universe.
- Income focused portfolios can widen their watchlist by scanning a curated 9 high quality undiscovered gems that combine fundamental strength with less crowded coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com