
BILL Holdings (BILL) Earnings Beat And Buyback Put Fair Value Back In Focus
BILL Holdings (BILL) just delivered a first quarter update that paired higher revenue and a move to profitability with fresh guidance and a completed buyback, giving investors several new data points to weigh.
Across the market, attention has shifted back to BILL Holdings after the recent earnings beat, revised outlook and completion of a US$600.01m buyback. The 30 day share price return of 23.31% suggests momentum has picked up following a softer 3 year total shareholder return that declined 14.50%.
Spot fresh momentum in BILL Holdings and compare it with other payment and software players by running your own screen of 20 high quality undiscovered gems.
The jump in BILL Holdings after earnings and buybacks puts investors on a forked path. Lean into the current reset, or wait and see if the valuation offers a cheaper entry later.
Most Popular Narrative: 9% Undervalued
BILL Holdings closed at $54.48 against an analyst consensus fair value of $60.15, which points to a modest discount in the analyst consensus Narrative on Simply Wall St that is built from revenue, earnings and margin forecasts rather than a single opinion.
The main thing that has to go right is that BILL Holdings successfully executes its pivot to an integrated, AI-powered financial operations and embedded payments platform while managing the drag from Spend & Expense and bank-channel pruning.
The current valuation implies the market is heavily discounting BILL Holdings despite guidance for double-digit core revenue growth, higher non-GAAP operating margins above 23%, rising GAAP profitability, and sizeable share repurchases that reduce the share count.
See why 25 investors see BILL Holdings as 9% undervalued.
Result: Fair Value of $60.15 (UNDERVALUED)
Still, the BILL Holdings story can break if muted small business spending crimps payment volumes, or if bank partner pruning and Spend & Expense churn drag on core growth longer than expected.
Find out about the key risks to this BILL Holdings narrative.
Another View: BILL Holdings Looks Expensive On P/E
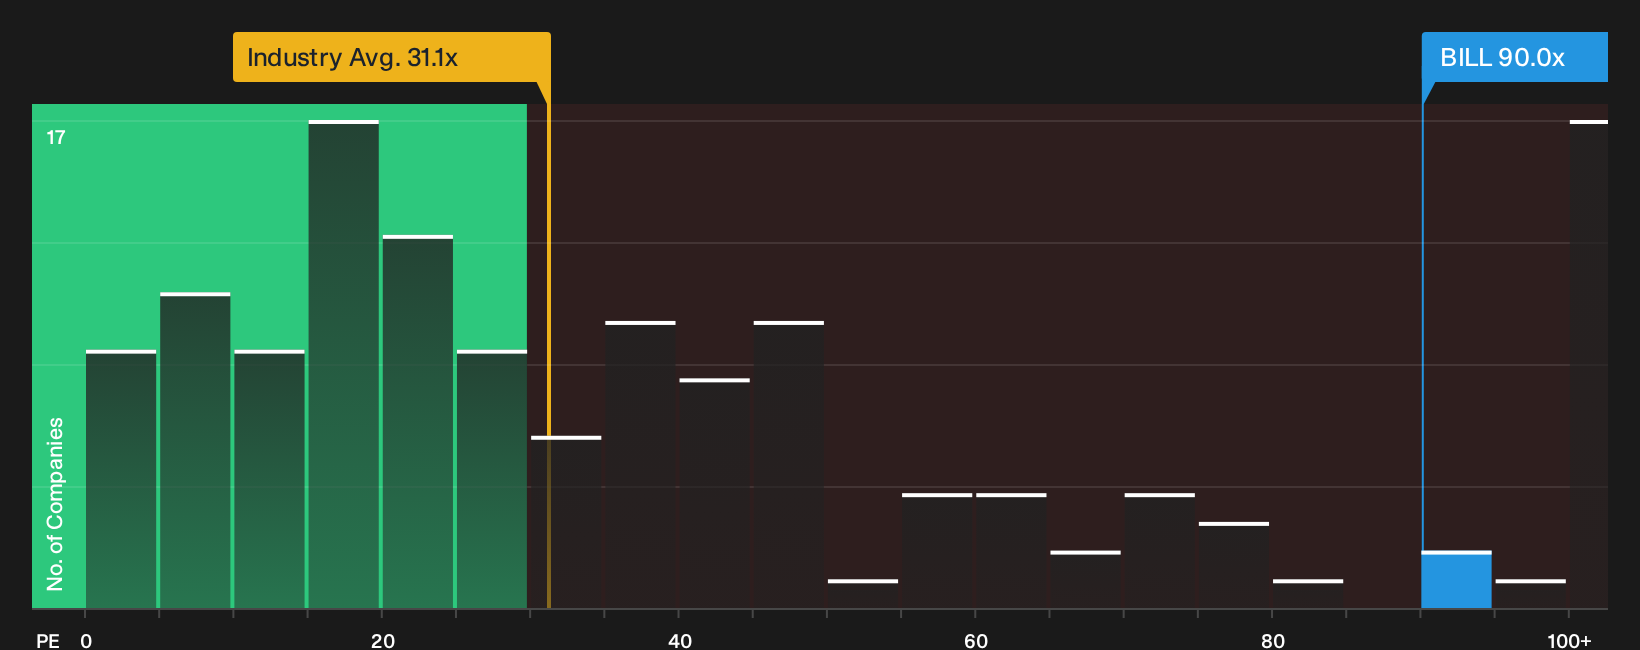
The analyst narrative on BILL Holdings points to a modest 9% discount to fair value, but the market is telling a different story when you focus on earnings. The stock trades on a P/E of 90x, compared with 30.9x for the US Software space and a fair ratio of 47.7x. That kind of gap usually means you are paying up heavily for the growth story. The key question is whether you think future profits can fill that valuation hole.
Before leaning too hard on any single fair value estimate, it helps to see how the numbers stack up in more detail, including that high P/E, peer comparisons and the fair ratio our models suggest the market could move toward. From there, you can weigh your own comfort with valuation risk against BILL Holdings execution track record. See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on BILL Holdings so far. If you want to move past the headline takes and build your own stance, start by weighing 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BILL Holdings?
You have fresh context on BILL Holdings, so now is the moment to widen your watchlist with a few focused idea lists built for different risk profiles.
- Target steadier compounding by checking companies that pair quality fundamentals with appealing entry points through the 32 high quality undervalued stocks.
- Prioritise resilience by scanning the 31 resilient stocks with low risk scores and see which businesses score strongest on balance sheet strength and risk metrics.
- Hunt for potential early-stage opportunities before they get crowded using the 13 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com