
Are Strong Half Year Earnings Altering The Investment Case For Landsec (LSE:LAND)?
- Land Securities Group reported half year sales of £443 million and net income of £244 million to 30 September 2026, and the board declared an interim dividend of 19.4 pence per share to be paid on 8 January 2027.
- The mix of higher earnings, stronger rental income and a slightly larger interim payout suggests management confidence in the reshaped retail focused portfolio.
- We will now look at how Land Securities Group's higher interim dividend affects the existing investment narrative around capital recycling.
Compare Land Securities Group's higher interim payout and retail tilt with a hand picked 4 dividend fortresses that may offer different combinations of income resilience and balance sheet strength.
Land Securities Group Investment Narrative Recap
To be comfortable owning Land Securities Group, you need to back the idea that a prime retail and London focused portfolio with high occupancy can keep supporting rental income, even if revenue is forecast in the analyst consensus Narrative on Simply Wall St to decline modestly. The higher interim dividend is a small adjustment, so it does not materially change that big picture.
The short term swing factor remains how quickly capital can be recycled from lower returning offices into higher yielding shopping centres, without stretching an already debt heavy balance sheet. The main risk is that higher interest costs and weaker asset sale markets slow that process and leave leverage and dividend cover under pressure.
The half year earnings release is the key piece of news to weigh here. Land Securities Group reported £443 million of sales and £244 million of net income, with basic EPS of £0.33. That level of profitability, helped by large one off items, gives management room to maintain guidance and support the slightly higher interim payout.
For catalysts, the more than expected interim rental income and reiterated full year guidance matter most. They speak directly to whether recent retail acquisitions like Metrocentre and higher stakes in Bluewater are tracking in line operationally. The risk side is that debt is not well covered by operating cash flow, so execution on leasing and recycling still needs to be tight.
Land Securities Group's narrative projects £768.5 million of revenue and £709.7 million of earnings by 2029, which implies revenue declining by 4.8% per year and an earnings increase of about £366.7 million from £343.0 million today.
Uncover why Land Securities Group's fair value indicates that Land Securities Group is roughly in line with its current price.
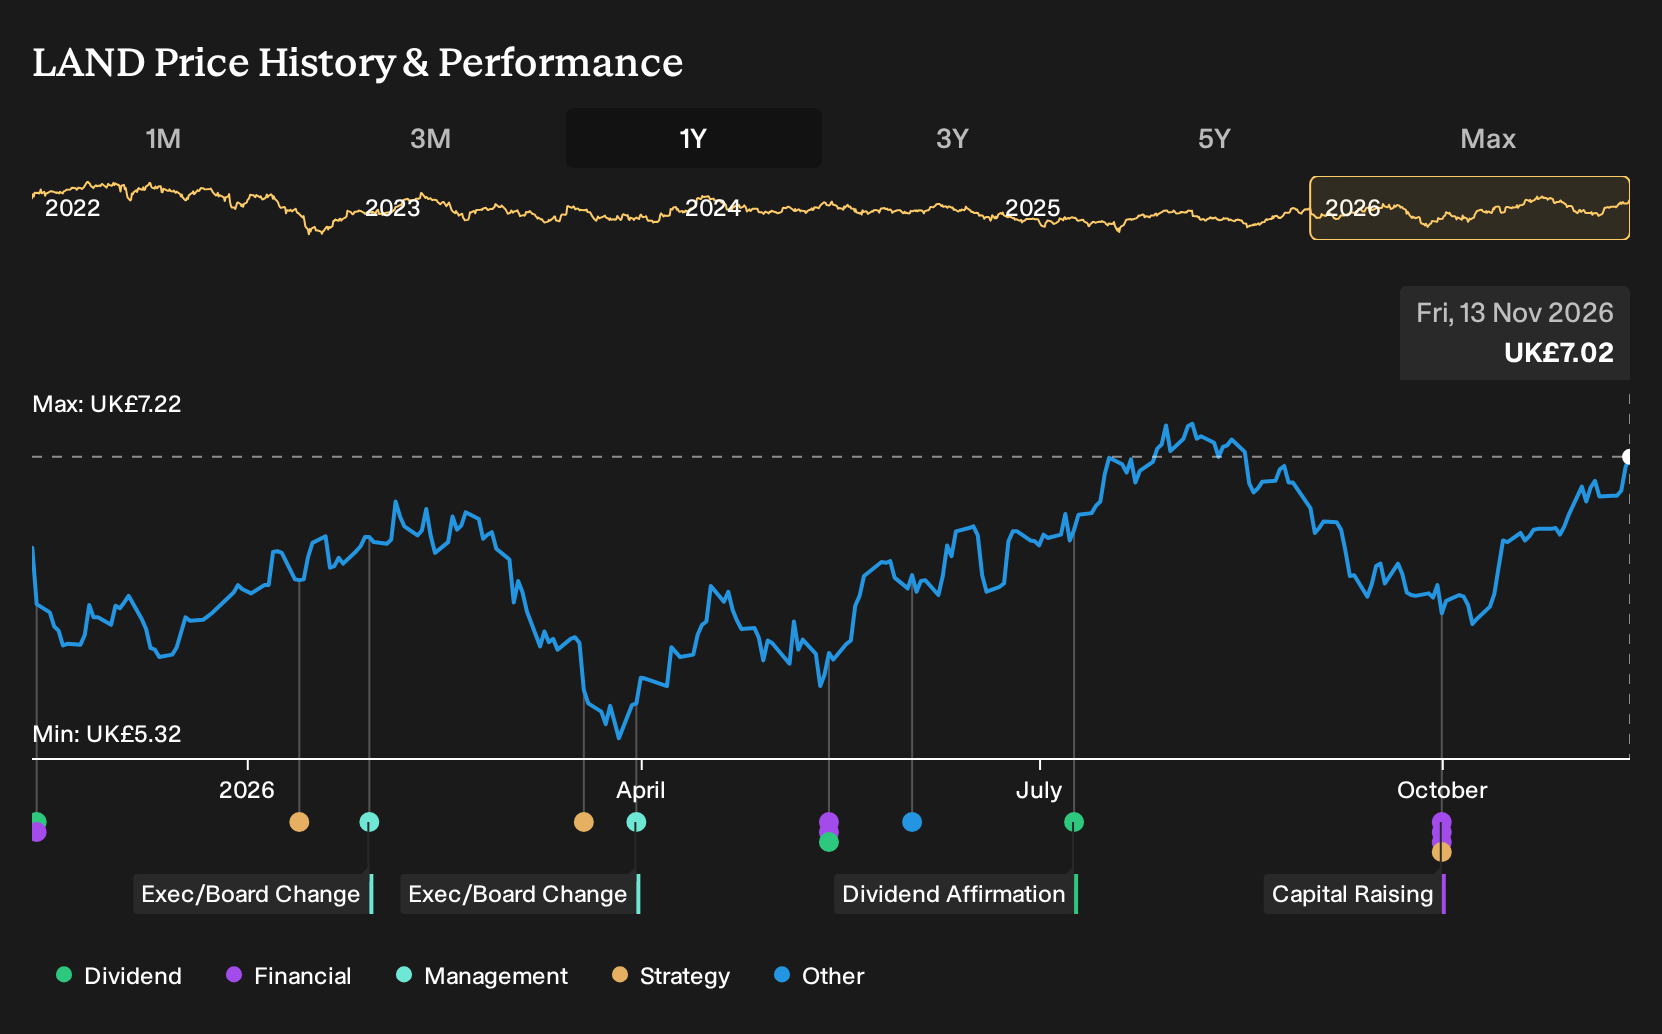
Exploring Other Perspectives
One alternate view on Land Securities Group focuses on the risk that its 9,000-unit residential pipeline underdelivers. Bearish analysts were already assuming revenue would decline around 7.4% a year and earnings of about £673.1 million by 2029. It is possible that this more cautious view could change once the higher interim dividend and recent earnings are fully reflected.
Explore 3 other Land Securities Group fair value estimates, including one that suggests it could be worth just £7.18.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Land Securities Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Land Securities Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Land Securities Group's overall financial health at a glance.
Looking for more investment ideas beyond Land Securities Group?
If the Land Securities Group story has sharpened your thinking on income, balance sheets and future earnings, it can help to widen the lens and compare it with other companies filtered on the same metrics that matter to you.
- For investors who care most about capital preservation and steadier profiles, scan a group of 5 resilient stocks with low risk scores that screen well on resilience and risk ratings.
- If value is your priority and you want businesses that combine quality fundamentals with prices that may look appealing on common ratios, start with a curated pool of 14 high quality undervalued stocks.
- For those hunting for strong income potential backed by cash generation and robust coverage, line up alternatives to Land Securities Group by reviewing a targeted 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com