
National Vision Holdings (EYE) Has Fresh Attention, But What Is Driving It?
Q3 earnings spark fresh focus on National Vision Holdings
National Vision Holdings (EYE) just put out third quarter results that showed higher revenue and net income versus a year earlier, while also rolling out a new US$100 million share repurchase plan.
Recent trading tells a mixed story. National Vision Holdings has delivered a 7.43% 1 month share price return and a 2.21% 7 day gain, yet the year to date share price return is down 29.5% and the 1 year total shareholder return has fallen 22.81%. This suggests sentiment is only cautiously improving despite the stronger earnings print and ongoing buybacks.
Spot fresh momentum stories like National Vision Holdings by scanning our curated 20 high quality undiscovered gems, which combine solid fundamentals with under-the-radar share price moves.Earnings momentum and a fresh US$100 million buyback plan present National Vision Holdings as a stronger business today. The real test is whether that profile is already reflected in the share price or still available at a discount.
Most Popular Narrative: 33% Undervalued
Against a last close of $18.30, the analyst consensus Narrative on Simply Wall St anchors fair value for National Vision Holdings at $27.50, pointing to a sizeable valuation gap and putting its mix shift and margin story under the microscope.
Ongoing premiumization of frames and lenses, with more than half of 2026 year to date ticket lift coming from customers choosing higher end products, while National Vision Holdings still offers over 40% of frames under $99 and remains priced well below category averages, leaves room for mix driven ticket growth that can support gross profit dollars and operating margin.
See why 0 investors see National Vision Holdings as 33% undervalued.
Result: Fair Value of $27.50 (UNDERVALUED)
Still, this hinges on the managed care mix and premium frames actually delivering the margin lift that analysts model, and on SG&A savings not fading as cost programs mature.
Find out about the key risks to this National Vision Holdings narrative.
Another View on National Vision Holdings
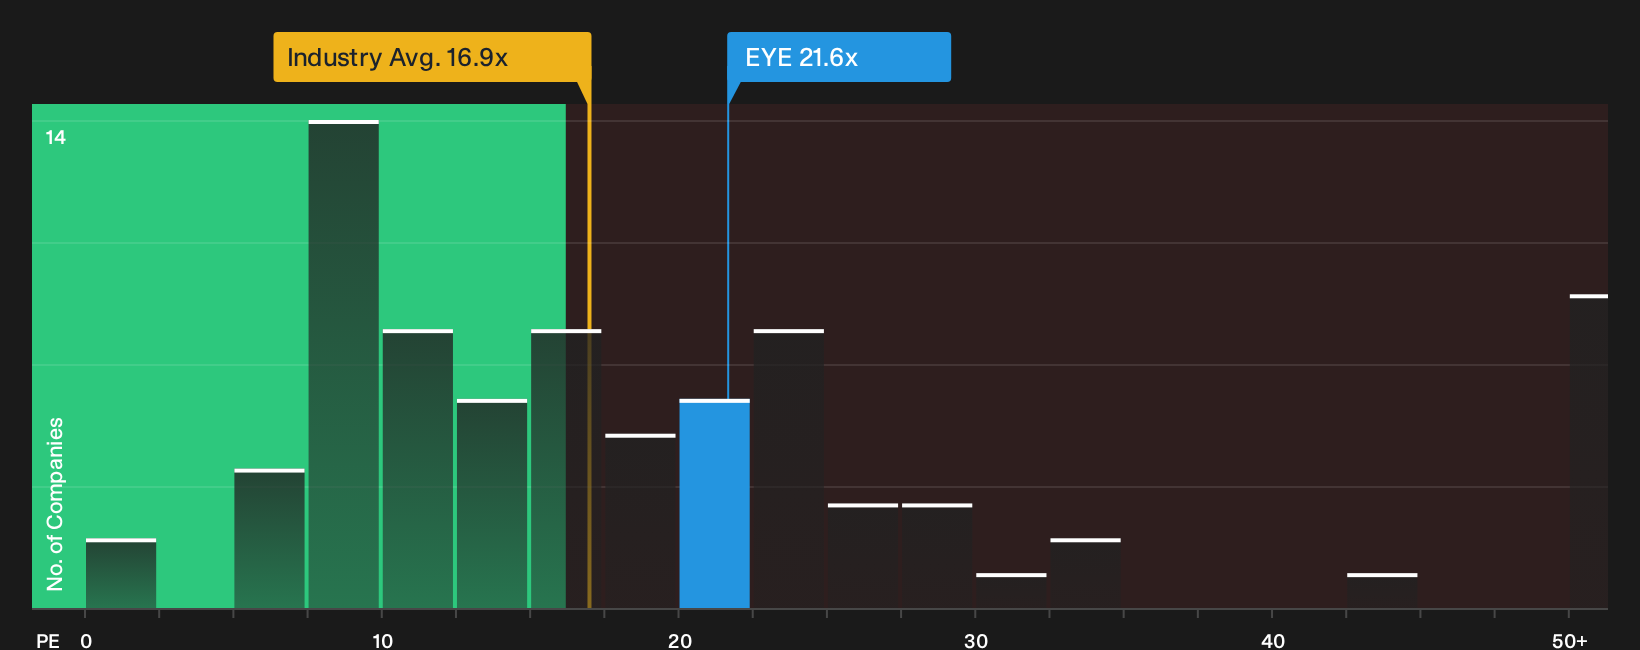
The story looks very different when the lens shifts from analyst fair value to earnings multiples. National Vision Holdings trades on a P/E of 21.6x, compared with 18x for peers, and a fair ratio of 16.9x. That premium suggests investors are already paying up. Is that margin of safety as wide as it seems?
For readers weighing the premium that multiple implies against the upside case, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment in this piece may feel cautiously optimistic, so move fast and pressure test the numbers, assumptions, and valuation work yourself before views harden. To see which rewards analysts and investors are focusing on, check the 3 key rewards.
Looking for more National Vision Holdings style ideas?
If you stop with National Vision Holdings, you risk missing other setups that match your risk profile and return goals across different corners of the market.
- Target potential upside in mispriced quality by scanning the 32 high quality undervalued stocks list that combines stronger fundamentals with what may be discounted valuations.
- Strengthen income potential and cash flow reliability by reviewing the 6 dividend fortresses options that focus on higher yield and payout resilience.
- Dial down portfolio shock risk by filtering for the 31 resilient stocks with low risk scores group that screens for sturdier balance sheets and more stable histories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com