
Learn Why The Bull Case For Maersk Stock Could Change Following Strong Quarterly Earnings
- A.P. Møller - Mærsk reported third quarter 2026 sales of US$18,095m and net income of US$2,986m, with basic EPS from continuing operations of US$207.
- The company completed a DKK544.85m buyback covering 0.22% of shares. This, alongside strong free cash flow guidance, highlights active capital return as earnings expand.
- We will now look at how A.P. Møller - Mærsk's stronger free cash flow outlook could reshape the investment narrative around its cycle exposure.
Scan how A.P. Møller - Mærsk's cash generation profile compares with peers by reviewing our curated list of list of solid balance sheet and fundamentals (198 results).
A.P. Møller - Mærsk Investment Narrative Recap
The analyst consensus Narrative on Simply Wall St suggests that to hold A.P. Møller - Mærsk, you need to believe the integrated logistics shift, Gemini cost efficiencies and terminal concessions can offset pressure on Ocean earnings. The latest quarter, with US$18,095m in sales and US$2,986m in net income, supports the idea that cost and capacity execution remain key short term drivers.
The biggest near term catalyst is whether strong free cash flow and operational benefits from Gemini keep offsetting softer shipping conditions and an expanding global orderbook. The main risk is earnings compression if freight rates or volumes weaken faster than logistics and terminals can grow their contribution.
The most relevant fresh datapoint is the third quarter 2026 result. Sales of US$18,095m and net profit of US$2,986m, with basic EPS from continuing operations of US$207, underline how much operating leverage still sits in A.P. Møller - Mærsk when capacity stays tight and efficiency work lands.
Those figures matter for catalysts because they interact directly with the firm’s upgraded 2026 guidance and free cash flow outlook. Strong earnings help fund buybacks such as the DKK544.85m already completed, support dividends and give management room to keep investing in terminals and Logistics & Services while absorbing potential Ocean volatility.
A.P. Møller - Mærsk's current analyst framework points to revenue of US$58.1b and earnings of US$1.5b by 2029, based on revenue growing at 1.1% a year and earnings moving from US$2.3b today to the US$1.5b consensus, a decline of US$0.8b.
Uncover why A.P. Møller - Mærsk's fair value indicates A.P. Møller - Mærsk is in line with its current price.
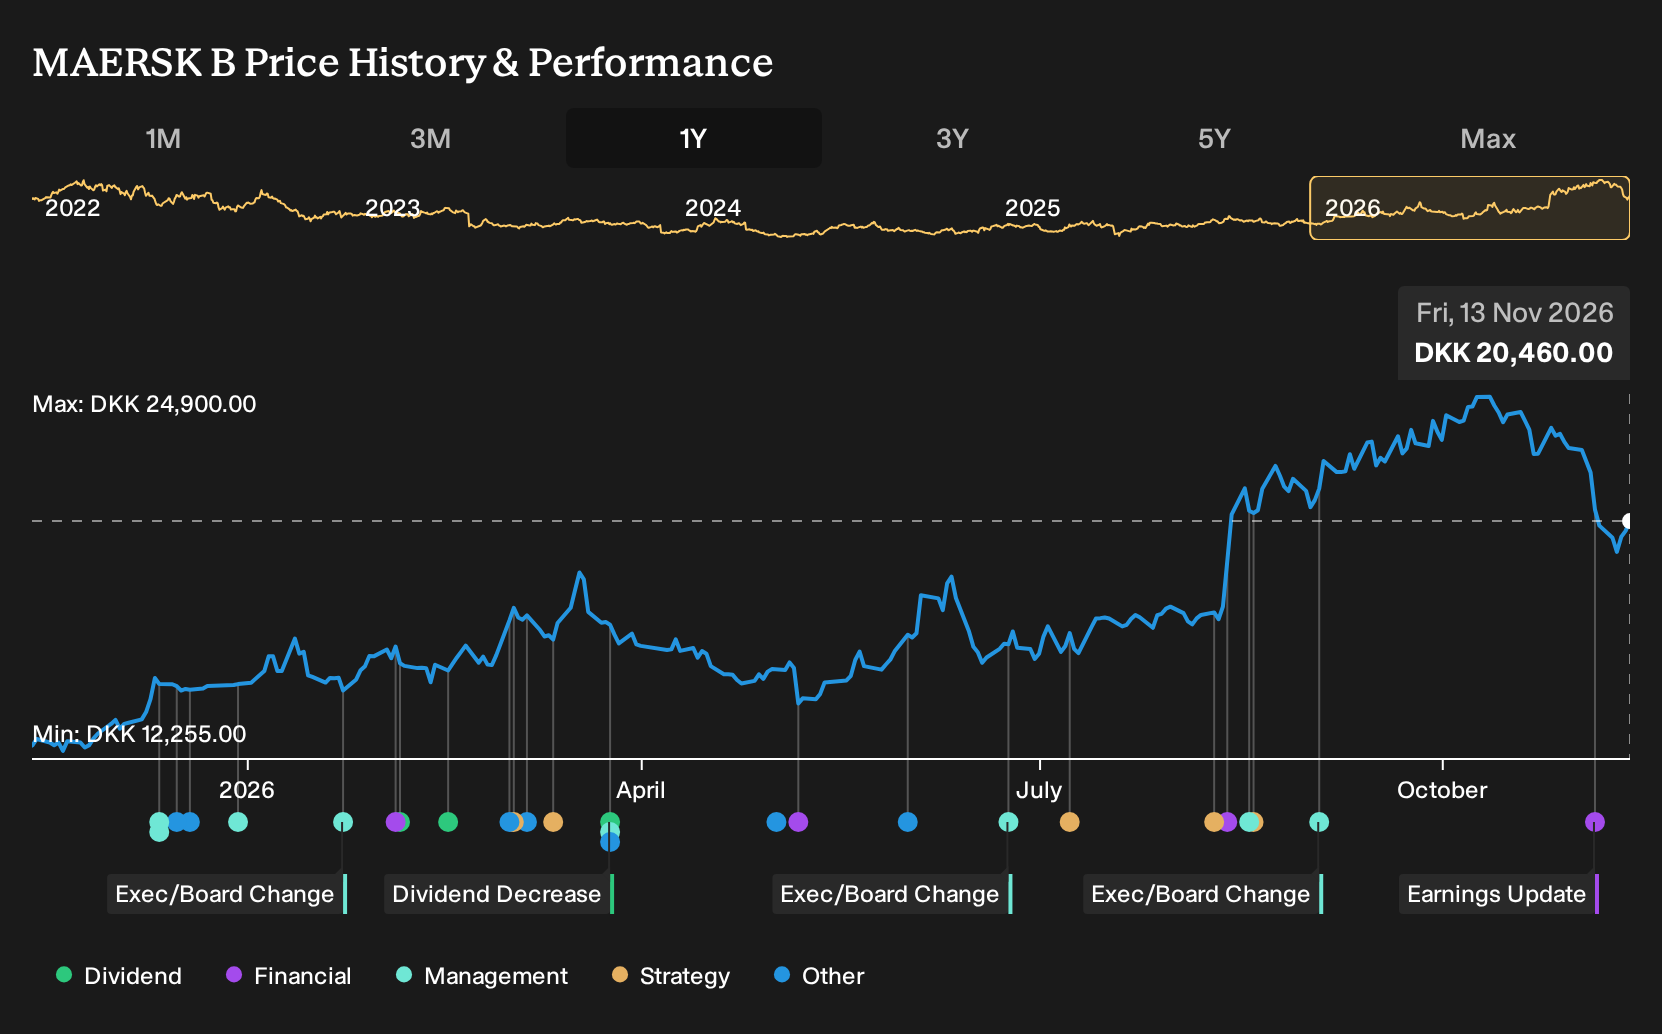
Exploring Other Perspectives
Some of the most optimistic analysts focus on Gemini cost savings as the key catalyst for A.P. Møller - Mærsk, arguing that roughly US$950m of annual Ocean efficiencies and a path to US$2.9b in earnings on US$62.8b of revenue by 2029 were already on their radar before this earnings beat. You can see how far views can stretch, from cautious to very upbeat, and you can use this strong quarter and buyback update as a trigger to compare those pre news assumptions with your own expectations.
Explore 3 other A.P. Møller - Mærsk fair value estimates, including one that suggests there could be as much as 34% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your A.P. Møller - Mærsk research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for A.P. Møller - Mærsk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A.P. Møller - Mærsk's overall financial health at a glance.
Looking for more A.P. Møller - Mærsk investment ideas?
If this A.P. Møller - Mærsk update has you thinking about portfolio upgrades, it can help to compare this stock with other companies that have very different risk and return profiles. Use the Simply Wall St Screener to quickly sort through focused shortlists instead of scrolling through hundreds of tickers.
- If you care most about resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (198 results) that meet a high bar on debt and cash metrics.
- If income matters to you, scan for reliable cash returns using our filter of 220 dividend fortresses that offer elevated yields with supporting financials.
- If you prefer to hunt for potential bargains, broaden your watchlist with 199 high quality undervalued stocks based on their quality scores and intrinsic value checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com