
Transocean (RIG) Shares Climbed, What Is Behind The Latest Attention?
Transocean earnings and guidance reset the story
Transocean (NYSE:RIG) just swung to a third quarter net profit of US$26 million after a large loss a year earlier, and paired that result with fresh drilling revenue guidance through 2027.
At a share price of US$5.54, Transocean has seen a 1-day share price return of 4.14% and a year-to-date share price gain of 30.66%. The 1-year total shareholder return of 38.15% contrasts with a weaker 3-year total shareholder return, which signals recent momentum building as investors reassess the earnings turnaround and new revenue guidance.
Scan other contract drillers showing similar earnings momentum and revenue visibility by reviewing the 32 high quality undervalued stocks that pair improving cash flows with balance sheet strength.
After Transocean’s sharp rebound and fresh revenue guidance out to 2027, the question tightens. Does it make more sense to step in at US$5.54, or wait for the market to offer a cheaper shot at the story reset?
Most Popular Narrative: 38% Undervalued
On Simply Wall St, the most followed valuation narrative pegs Transocean’s fair value at about $9.00 per share, compared with the latest close at $5.54. According to Cannibal_Stocks, an investor in the Simply Wall St Community who wrote the narrative, that gap comes down to how the rig fleet and debt profile are viewed together.
In 2008 the market paid $48 billion for a worse fleet with more debt on the way. Today it pays $6.5 billion for this one and calls it risky.
See why 9 investors see Transocean as 38% undervalued.
Result: Fair Value of $9.00 (UNDERVALUED)
Still, the Transocean narrative could crack if debt remains elevated longer than expected or if offshore dayrates soften enough to weaken cash flow and reduce confidence in refinancing.
Find out about the key risks to this Transocean narrative.
Another View: What Transocean’s P/E Is Really Pricing In
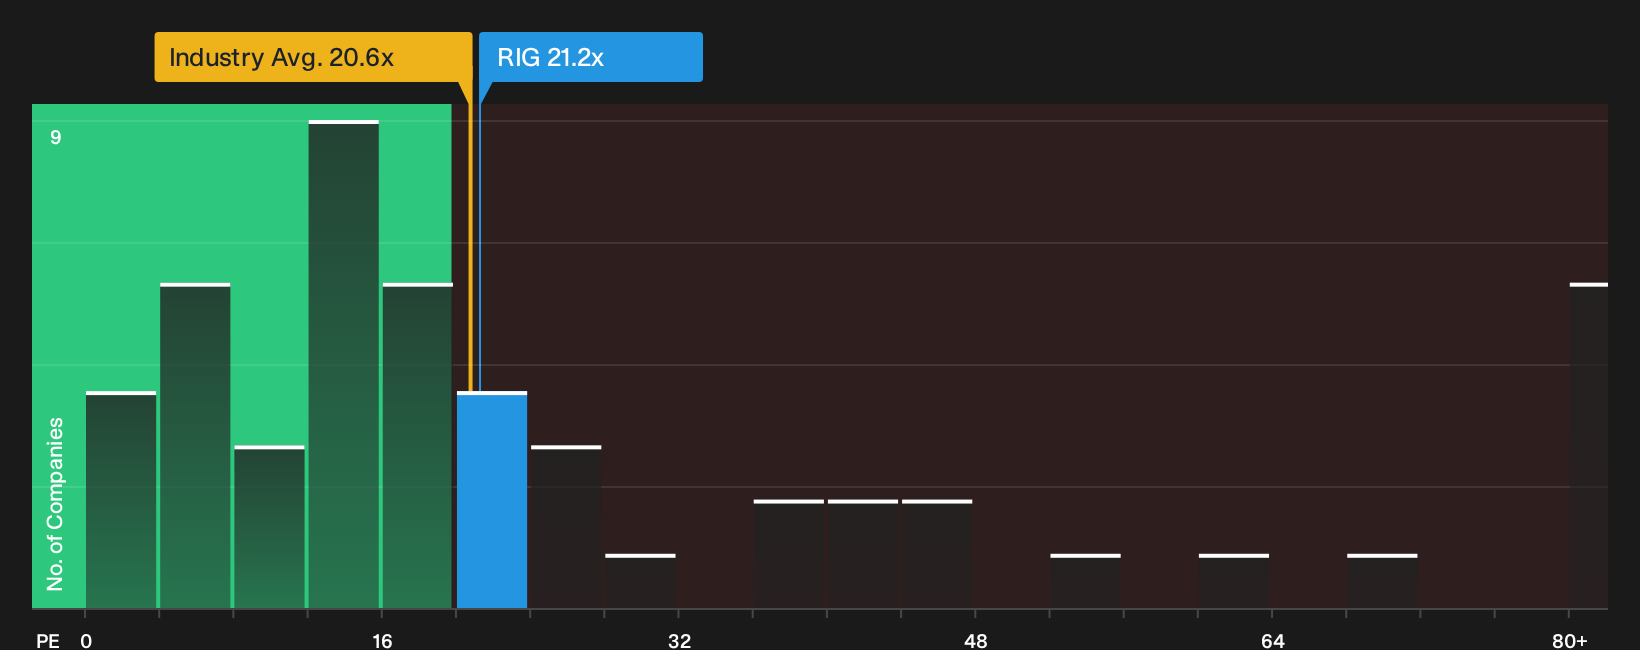
The community narrative leans on rig count, dayrates and a US$9.00 fair value, yet the market is also looking hard at simple earnings multiples. On that lens, Transocean trades on a P/E of 21.2x against an estimated fair ratio of 12.9x and a US Energy Services industry average of 20.6x.
That mix tells you two things. The share is cheaper than some peers that carry an average 48.5x P/E. At the same time, it screens as more expensive relative to the fair ratio that the market could drift toward if sentiment cools. For anyone weighing the US$5.54 price against a 38% discount narrative, how much room feels comfortable if the market leans back toward that 12.9x anchor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Transocean is split, with clear risks on one side and meaningful upside arguments on the other. Move quickly and test the numbers yourself using the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Transocean?
Do not stop with Transocean. Broaden your watchlist now and give yourself more ways to react when the market serves up mispriced stories.
- Target potential mispricings by scanning companies that combine solid fundamentals with discounted valuations using the 32 high quality undervalued stocks.
- Rebalance toward stability by reviewing a 31 resilient stocks with low risk scores that score well on resilience when conditions turn rough.
- Hunt for future market favourites early by checking a 20 high quality undiscovered gems that already show strong underlying business quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com