
Missed Electro Optic Systems' Run? What Holders Had To Believe
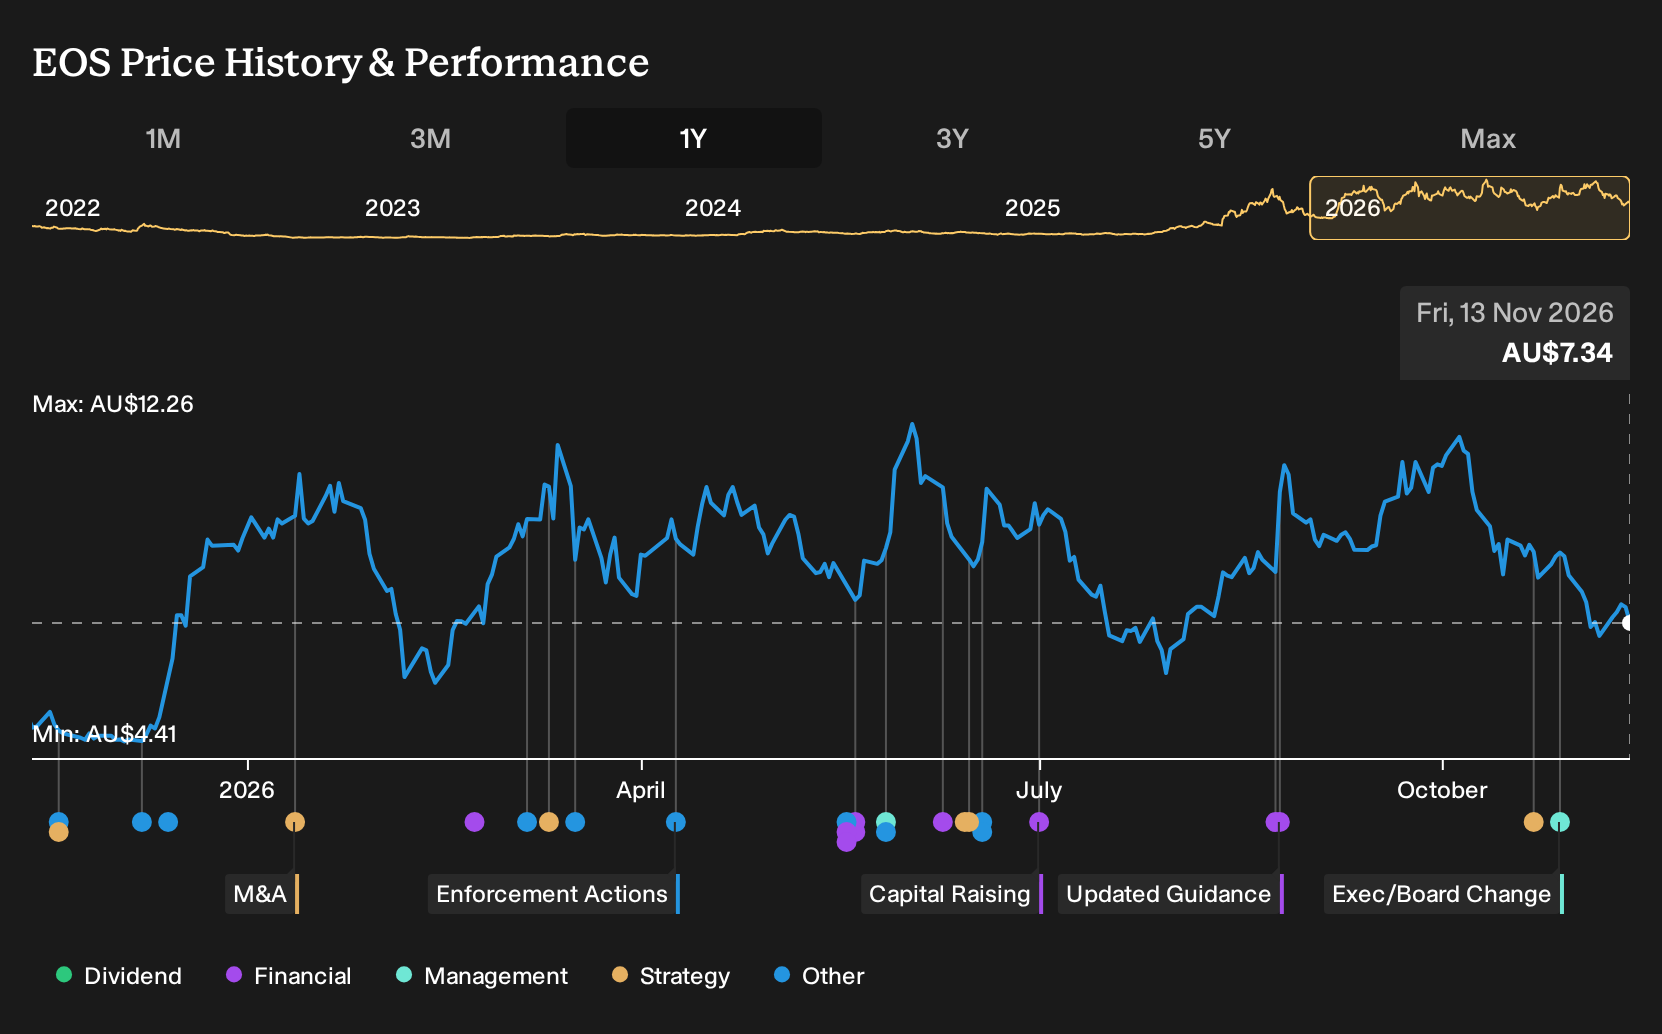
If you had backed Electro Optic Systems on 13 November 2025 and simply held on, the outcome would have been hard to ignore. Holding Electro Optic Systems over the past year would have returned 53.6%, including dividends. That result now sits alongside headlines about MARSS, multi country counter drone contracts, and a swelling order book. If you were weighing those bullish and cautious forecasts a year ago, what mattered most in deciding whether the business model could really scale?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The move put Electro Optic Systems in the middle of this trade. Scan 53 AI infrastructure stocks for other companies exposed to it.
The Argument You Would Have Been Weighing Up On Electro Optic Systems
The shares cost A$4.75 at the start of the period, so any view on Electro Optic Systems needed to stack that price against two very different stories investors were telling themselves.
The optimistic camp saw Fair Value at A$5.45, based on assumptions that revenue could climb 39.8% a year with profit margins moving from a loss to 8.3% and a future P/E of 49.0x.
The sceptical side put Fair Value at A$4.36, assuming 30.0% annual revenue growth and a 10.0% margin but worrying that overconfidence in defense spending and counter-drone demand might not hold.
What The Evidence Around Electro Optic Systems Actually Tested
The MARSS acquisition, Kuwait’s £370 million Nation Shield contract and letters of intent for Apollo lasers all leaned toward the bullish view that Electro Optic Systems could scale full stack counter drone systems and grow its order book. The 2026 interim result also showed revenue at A$168.8 million and a smaller loss, with net margin at a 19.5% loss, so profitability assumptions remained unproven. Overall, the evidence cut both ways.
The key lesson is simple. When a story rests on scaling a defence platform, track order book size, contracted delivery windows and whether rising revenue turns loss making margins into profit in the reported numbers.
What Electro Optic Systems’ Run Leaves You Paying For Now
Electro Optic Systems now trades at A$7.34 after a 53.6% gain over the past year, and the analyst consensus Narrative on Simply Wall St sets its Fair Value above that market price.
That view leans heavily on defence contracts, counter-drone systems and a growing European presence. A buyer today needs to judge whether sustained global demand for these defence and space offerings really holds.
"Technological leadership, global defense demand, and diversified dual-use offerings position the company for resilient financial growth, margin improvement, and reduced earnings risk. Technology trends favoring automation, AI-driven swarm defenses, and increasing demand for both military and critical civilian infrastructure protection position EOS''s product pipeline for secular growth, supporting medium to long-term revenue and potential margin expansion."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 27% below our estimate - supplies critical truck and bus components that extend vehicle uptime for operators.
- Company 2 - 15% below our estimate - integrates cloud, security and AI systems as clients consolidate fragmented technology projects.
- Company 3 - 31% below our estimate - sells consumer electronics through efficient stores supported by higher-margin after-sales services.
Three companies from the same screener. Open every one of the 12 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com