
NASA Contract Wins Might Change The Case For Investing In Intuitive Machines Stock (LUNR)
- Intuitive Machines reported third quarter 2026 revenue of US$269.35 million, a net loss of US$4.02 million, and highlighted a US$1.9b backlog supported by NASA contracts such as CLPS 2 and FALCON-RADAR.
- The same period showed Intuitive Machines widening its nine month loss while securing a larger mix of lunar, Earth observation, and national security work, which points to heavier investment in building out a broader space technology platform.
- We will now look at how this investment narrative shifts as a record backlog and new NASA work start to reshape business risk.
Scan beyond Intuitive Machines and compare its space-tech story with other high-potential plays from our hand picked 53 AI infrastructure stocks.
Intuitive Machines Investment Narrative Recap
To own Intuitive Machines, you need to believe it can turn a growing space infrastructure footprint into a more efficient, eventually self-funding operation. The latest quarter shows US$269.35 million in revenue, a record US$1.9b backlog and a relatively small quarterly loss of US$4.02 million, so scale is clearly building.
The near term hinge is execution on contracted lunar and Earth observation work while keeping fixed costs under control. According to DanielOliveira, an investor in the Simply Wall St Community, earlier concern was that backlog quality and thin margins might limit upside, and that question remains the key operating risk despite stronger reported figures.
The CLPS 2 award announcement looks most connected to the current investment story around Intuitive Machines. CLPS 2 is an up to US$10b NASA framework across multiple providers, with a possible lift to US$15b. This gives the business a pipeline structure for future lunar delivery task orders rather than just one off wins.
For you as a shareholder, the contract framework matters because it intersects directly with catalysts and risks that DanielOliveira highlighted. The upside comes from converting framework access into large, executable missions that feed the backlog and support the Build, Connect, Operate model. The flip side is that execution, timing of awards and capital intensity will drive how much of that opportunity actually translates into sustainable cash generation.
On valuation, DanielOliveira anchors fair value at US$9.93 per share, as the thesis focuses on what Intuitive Machines' Q3 2026 report will reveal rather than on a long-run cash flow model or a margin rebuild story.
Uncover how Intuitive Machines' fair value indicates a 24% potential downside to its current price, which may reflect a premium that does not hold.
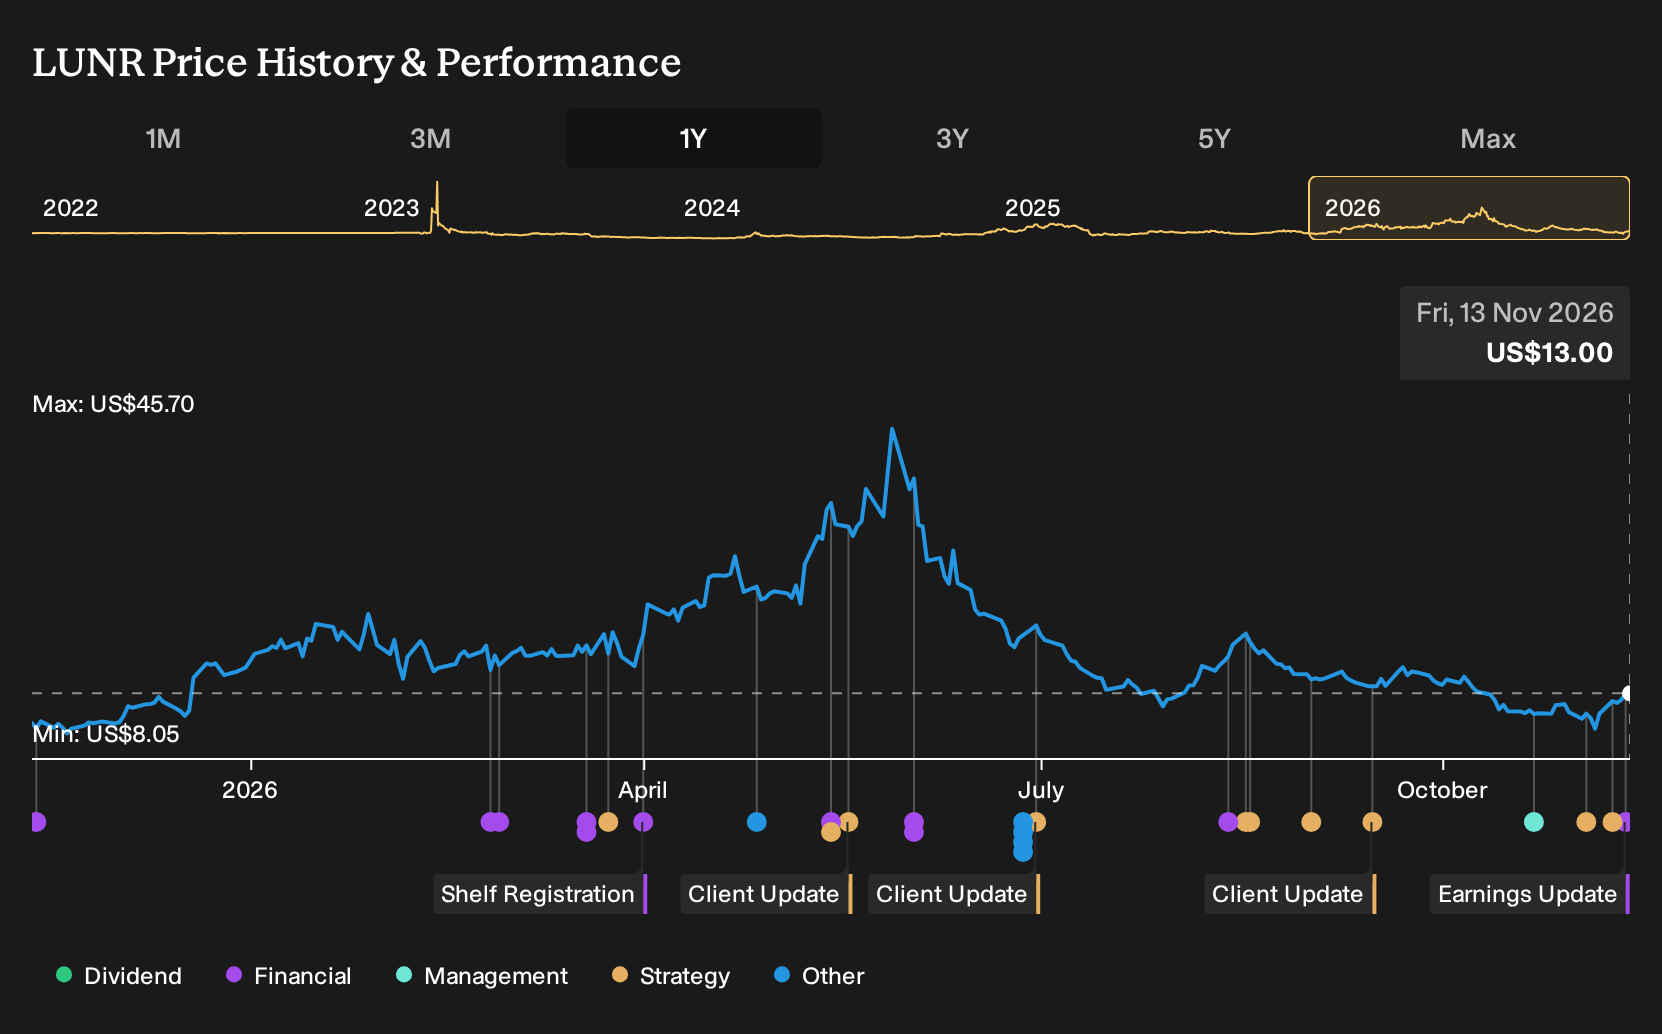
Exploring Other Perspectives
Some of the most optimistic analysts focus on Intuitive Machines' CLPS 2 access as a potential accelerator. Before this report, they were penciling in around US$900m to US$1b of revenue and future earnings of about US$150.2m by 2029. That is a far more upbeat story, and it may shift once this week’s contracts and Q3 numbers are fully absorbed.
Explore 9 other Intuitive Machines fair value estimates, including one that suggests up to 200% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Intuitive Machines research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Intuitive Machines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuitive Machines' overall financial health at a glance.
Looking for more investment ideas beyond Intuitive Machines?
Once you have a view on Intuitive Machines, it can help to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you quick, comparable shortlists so you are not relying on a single story.
- If you want to stay focused on resilience and capital preservation, consider reviewing a 30 resilient stocks with low risk scores that score well on defensive qualities and lower overall risk.
- If balance sheet strength is your priority, start with a list of solid balance sheet and fundamentals (24 results) that pair financial stability with underlying business quality.
- If you are hunting for potential mispricings, scan through a 19 high quality undiscovered gems that combine strong fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com