
How Buy Upgrade Will Impact Getty Realty Stock Investors
- Argus recently raised its rating on Getty Realty to BUY, reflecting attention on the REIT’s focus on single tenant convenience and automotive properties across the U.S.
- The upgrade turns the spotlight onto Getty Realty's core engine: long dated net leases and relationship driven sale leasebacks that shape rent visibility and acquisition economics.
- This development places additional focus on how Getty Realty's investment narrative may be influenced by the Argus upgrade and the emphasis on its net lease portfolio.
See how Argus’ upgrade on Getty Realty compares with peers by reviewing hand picked list of solid balance sheet and fundamentals (24 results) positioned for stable cash flow and tenant resilience.
Getty Realty Investment Narrative Recap
For Getty Realty, the big picture you need to buy into is simple. The REIT keeps its 1,224 property portfolio largely full, maintains long net leases and steadily recycles capital into new convenience and automotive sites. The analyst consensus Narrative on Simply Wall St leans on that combination of high occupancy, roughly 10.3 year lease terms and rent coverage around 2.5x as core to the story.
In the near term, the key swing factor is how effectively Getty Realty can deploy its US$95 million to US$125 million pipeline at yields that still clear its roughly 6.25% unsecured debt cost. The biggest operational risk is pressure on tenant economics from fuel demand changes or automotive consolidation, which could eventually weigh on occupancy and rent collection if conditions weaken.
One of the most relevant data points alongside the Argus rating change is the focus on Getty Realty using mid to high 7% initial yields on acquisitions. Those deal terms, if maintained, create a spread over its estimated funding cost and support the external growth engine analysts are watching.
That acquisition profile, combined with more than US$570 million of liquidity and no debt maturities until 2028, frames both the opportunity and the execution test. Getty Realty has room to keep funding long dated net leases and development projects, while investors track whether tenant coverage at newer assets like car washes improves enough to limit credit losses and protect AFFO.
Getty Realty's current analyst narrative points to forecast revenue of US$306.9 million and projected earnings of US$108.1 million by 2029, based on assumed yearly revenue growth of 9.6%. That outlook implies an earnings increase of about US$11.8 million from earnings today of US$96.3 million.
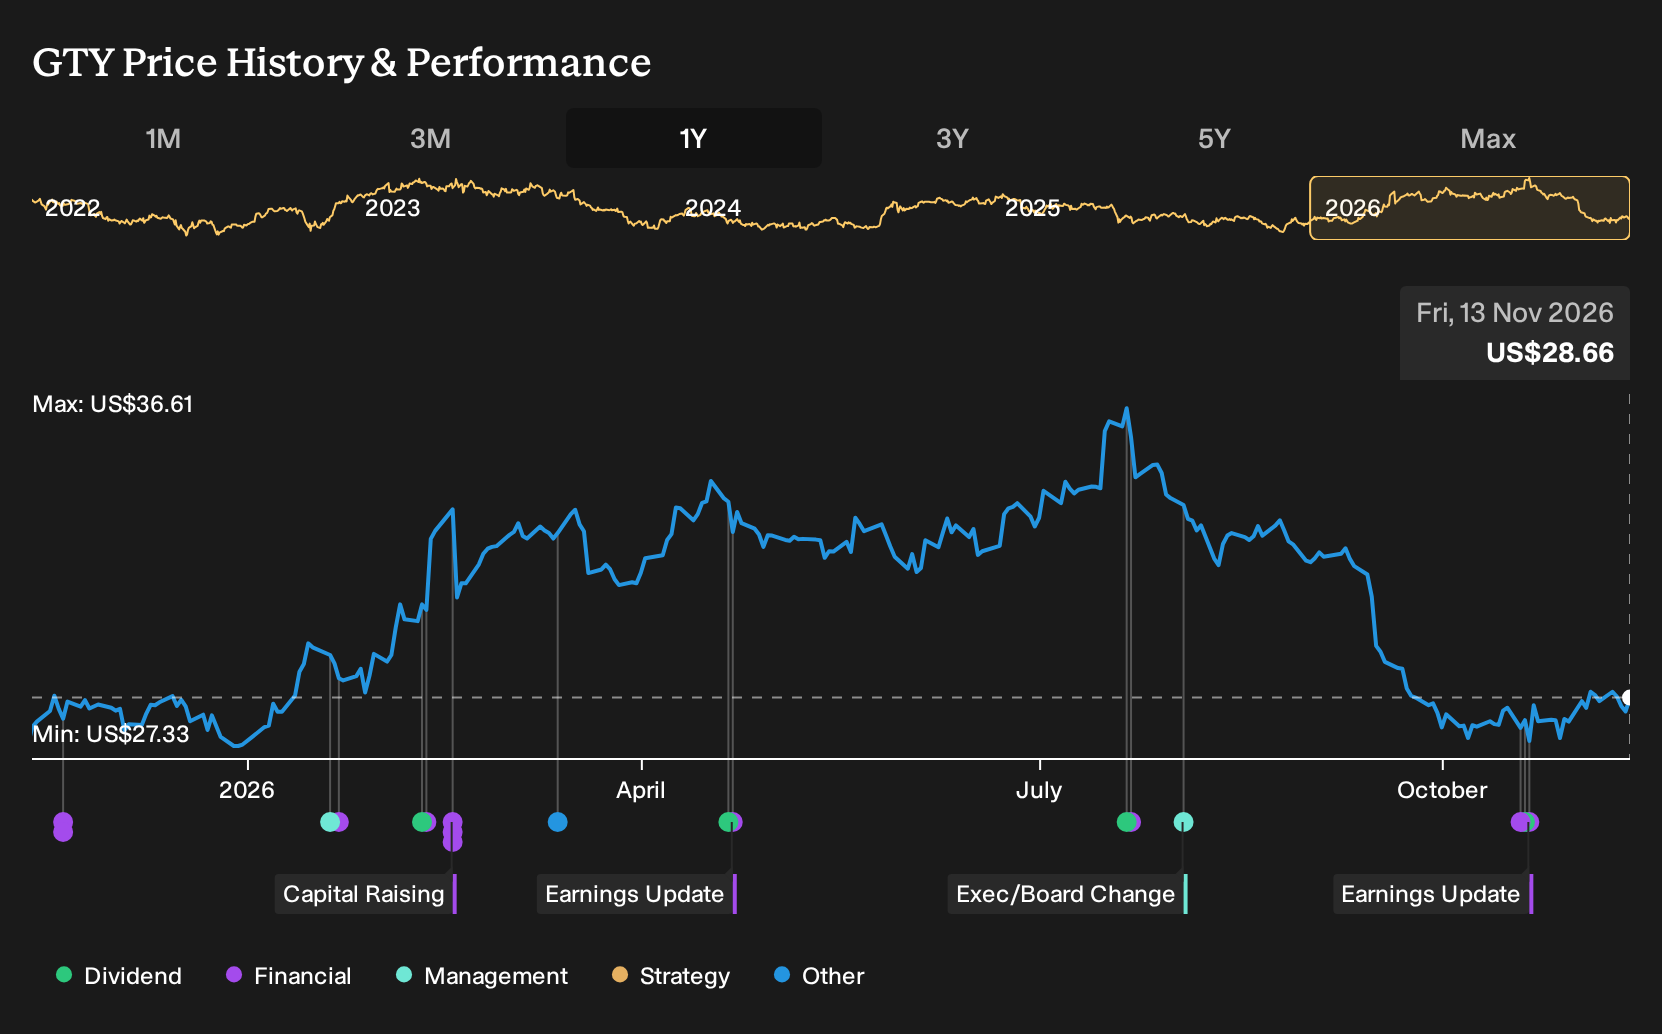
Uncover why Getty Realty's fair value indicates a 24% potential upside to its current price before the discount closes for Getty Realty.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$33.86 to US$74.19 per share for Getty Realty, so private investors are clearly not aligned on what the stock is worth. Pair that wide spread with risks around fuel demand, tenant consolidation and car wash coverage, and you should actively compare several viewpoints.
Explore 2 other Getty Realty fair value estimates, including one that suggests it could be worth just $33.86.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Getty Realty research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Getty Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Getty Realty's overall financial health at a glance.
Looking for more investment ideas beyond Getty Realty?
Once you have a view on Getty Realty, it can help to broaden your watchlist with other stocks that fit clear financial criteria using the Simply Wall St Screener.
- If you want potential upside with fewer balance sheet surprises, you can scan for resilient businesses using the 30 resilient stocks with low risk scores that score well on financial stability checks.
- For investors who care most about quality at a reasonable price, you can start with the 34 high quality undervalued stocks that filters for companies combining solid fundamentals with attractive valuations.
- If you prefer opportunities that are not heavily followed, the 19 high quality undiscovered gems can surface businesses with strong numbers that are still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com