
Does Revenue Growth Guidance Change The Bull Case For American Superconductor Stock?
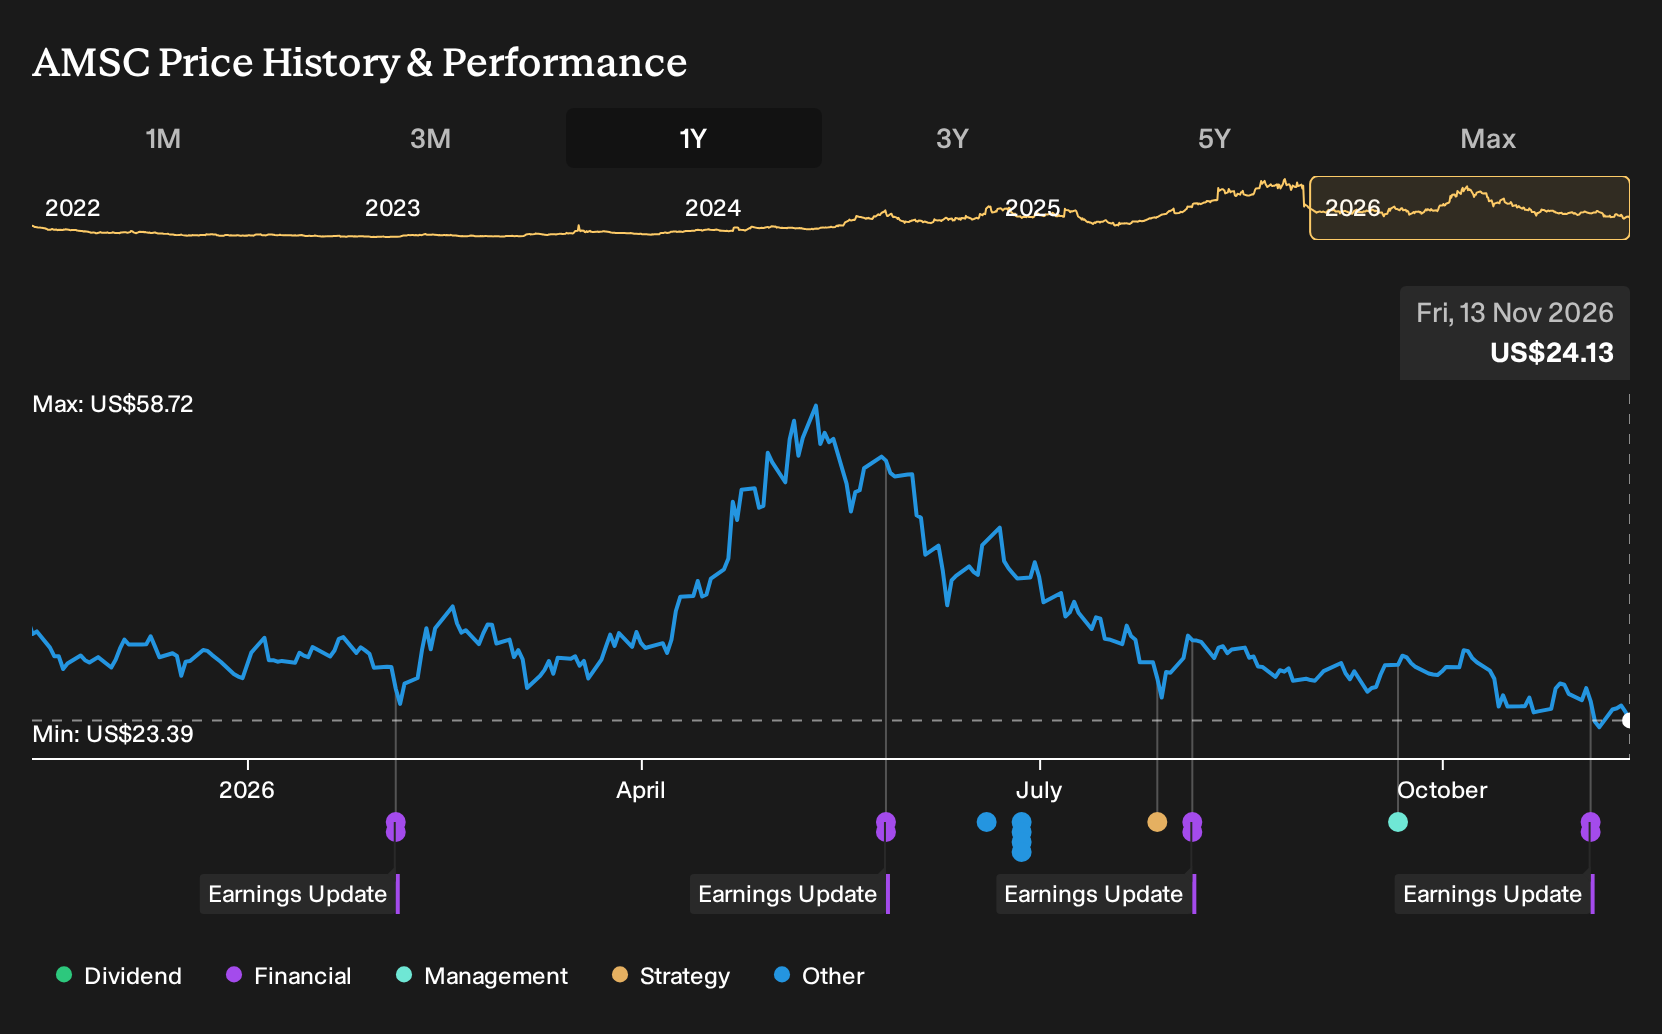
- American Superconductor reported Q2 FY2026 sales of US$94.04 million with net income of US$3 million, and issued guidance that Q3 revenue and net income are both expected to exceed breakeven levels.
- The mix of higher top line and softer quarterly earnings highlights how heavier cost absorption and expansion spending are pushing American Superconductor to work harder to convert strong demand into durable profitability.
- We will now assess how American Superconductor's stronger revenue base but thinner recent earnings could influence its broader investment narrative.
Scan beyond American Superconductor and compare its grid and wind momentum with a hand picked field of 44 power grid technology and infrastructure stocks that are shaping the future of energy infrastructure.
American Superconductor Investment Narrative Recap
To own American Superconductor, you need to believe the grid and wind solutions portfolio can turn a growing project pipeline into consistent cash generation despite a heavier cost base. The latest quarter delivered US$94.04 million in sales and US$3 million in net income, which keeps that narrative alive but shows less earnings breathing room.
The analyst consensus narrative on Simply Wall St leans on American Superconductor absorbing higher R&D and SG&A into future volumes. In the short term, the key catalyst is execution on high voltage grid and power quality projects while managing gross margin pressure. The biggest risk remains revenue lumpiness from large customers and expansion spend outpacing near term profits.
The fresh guidance for the third quarter ending December 31, 2026 is the clearest operational signal. Management expects revenue to exceed US$80 million and net income to come in above breakeven, or above US$0.00 per share. That points to an effort to hold the profitability streak even as earnings per share in Q2 stepped back to US$0.06 from US$0.11 a year earlier.
For you as a shareholder, that outlook ties directly into the main catalysts highlighted earlier, including integrated grid projects and Brazilian capacity. Delivering another profitable quarter at a slightly lower top line would suggest American Superconductor can support ongoing expansion without eroding earnings quality, while any miss against the breakeven guide could reinforce concerns about rising operating costs and order timing volatility.
American Superconductor's narrative projects US$529.1 million revenue and US$1.9 million earnings by 2029. This projection is based on 18.1% yearly revenue growth and an earnings decrease of about US$134.7 million from current earnings of US$136.6 million.
Uncover why American Superconductor's fair value indicates a 156% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For American Superconductor, the bearish twist is all about backlog risk. The lowest analysts worry that more than US$300m of 12 month backlog and roughly US$400m total could prove harder to convert, even though they were still penciling in about US$530.6m of revenue and US$4.5m of earnings by 2029. Those estimates were set before this latest Q2 result and fresh guidance, so treat them as moving pieces rather than fixed truth and use them as a prompt to compare several viewpoints before you decide how much risk you want to carry.
Explore 5 other American Superconductor fair value estimates, including one that suggests it could be worth just $38.61!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your American Superconductor research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Superconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Superconductor's overall financial health at a glance.
Looking for more investment ideas beyond American Superconductor?
If the American Superconductor story has sharpened your thinking, you can use that same lens across the wider market by scanning for other companies that fit the kind of balance of quality, risk and income profile you care about most.
- If capital preservation comes first for you, start with companies that score well on resilience through our 30 resilient stocks with low risk scores. Then compare how their risk profiles line up against American Superconductor.
- If you want potential value opportunities with stronger fundamentals, line up candidates from the 19 high quality undiscovered gems. Then see which ones offer a mix of quality metrics and under-the-radar coverage.
- If balance sheet strength matters more than headlines, filter for businesses with solid financial footing using the list of solid balance sheet and fundamentals (24 results). Then pressure test how they handle investment cycles and downturn risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com