
3 US Agribusiness Stocks Worth Watching If US China Trade Talks Progress
Trade talks between Washington and Beijing are back on the table, and agriculture is suddenly in the spotlight again. When tariffs are under review and farm exports are a key talking point, companies linked to US fields and equipment can see expectations shift fast, for better or worse. This article examines how that story ties into three US agribusiness stocks that are exposed to the latest US China trade headlines.
The stocks highlighted below are only a small sample, with the full screen surfacing 56 more US agribusiness and farm equipment companies tied to this trade theme that are not covered in the article. To identify and analyze the highest conviction ideas from that broader group, head straight to the US Agribusiness and Farm Equipment Benefiting from Improved US–China Trade screener.
Titan International (TWI)
Titan International plugs directly into the trade theme, since its off highway wheels and tires sit on the same farm machines that could see more use if US export flows improve. The analyst consensus Narrative on Simply Wall St frames how trade rules might reshape that picture.
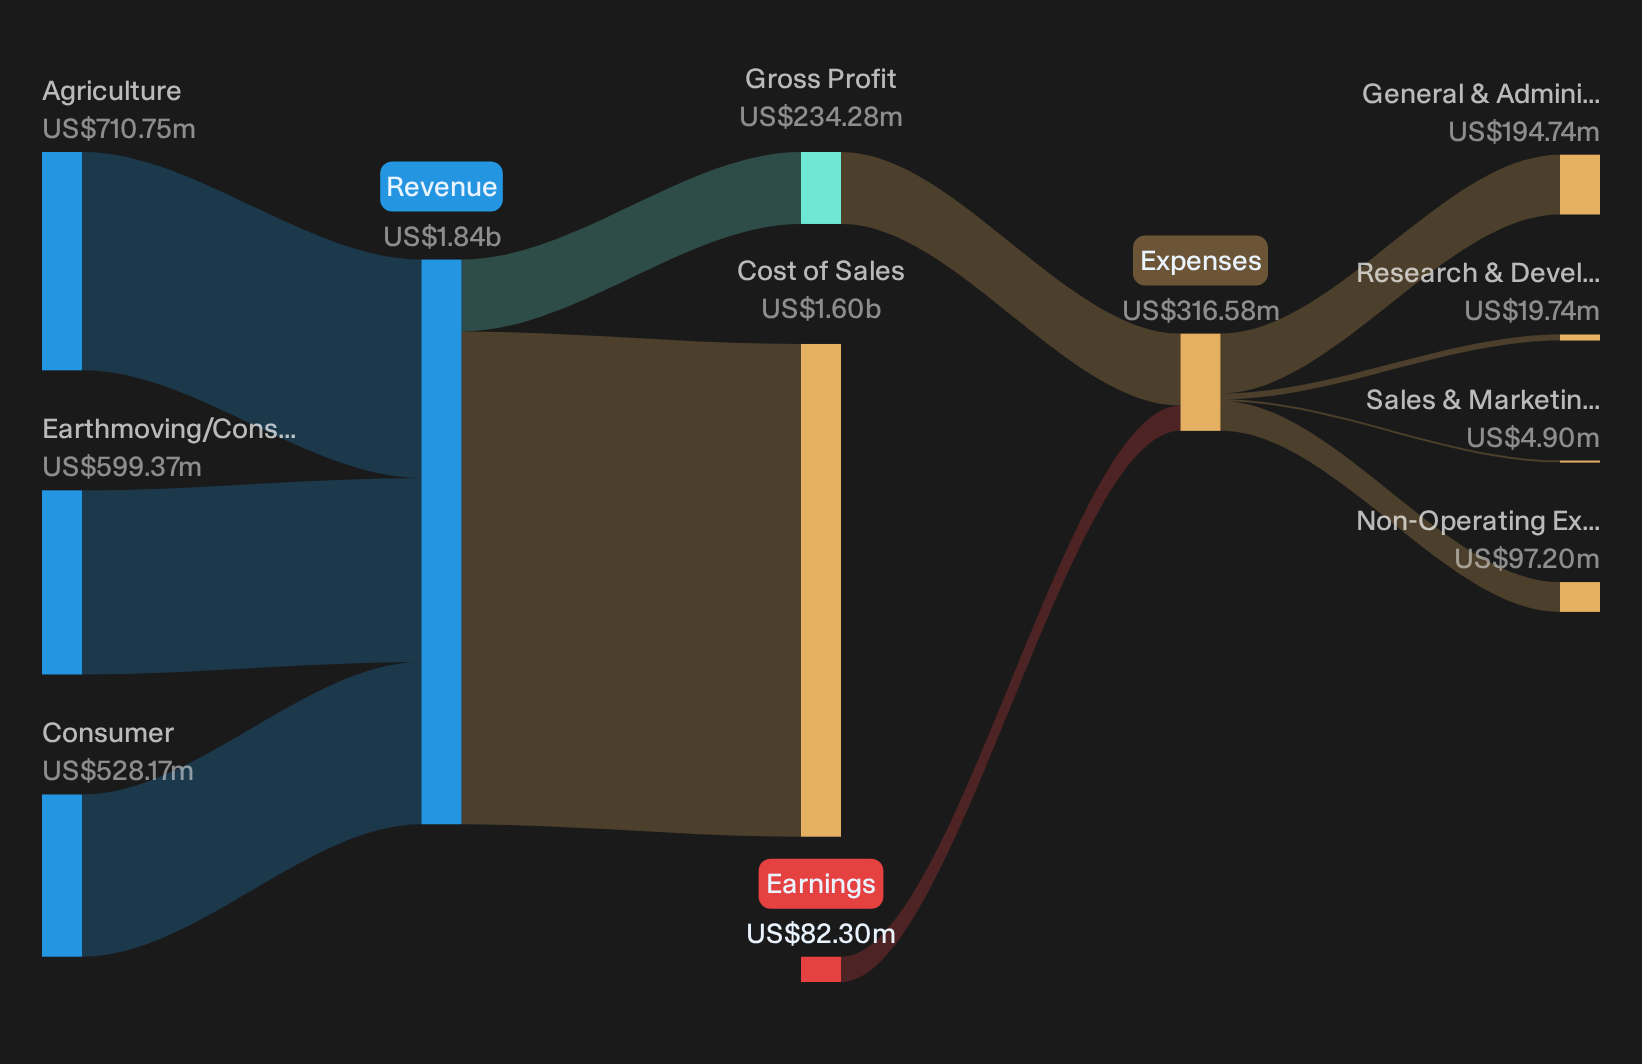
Titan International manufactures off highway wheels, tires and undercarriage systems for agricultural and construction machinery worldwide, with agriculture generating about US$711 million of revenue, earthmoving and construction about US$599 million, and consumer markets roughly US$528 million. The stock is a smaller cap at about US$329 million.
"Anticipated resolution and consistent application of global trade policies and tariffs are expected to create a more level playing field, reducing competitive pressures from low cost imports and supporting higher pricing power and improved net margins for Titan International."
The real swing factor for Titan International is how one unresolved pressure on its pricing power ultimately feeds through to margins and farm equipment demand.
That pricing squeeze is exactly what the full narrative for Titan International unpacks in detail, including where trade policy pressure could be masking a stronger long term earnings story.
Corteva (CTVA)
Corteva sits squarely in the screener theme because it sells seeds and crop protection products to the same US growers whose spending power rises when export demand improves. According to Bouden, a Simply Wall St Community investor who wrote the Narrative, the real story shows up in the revenue path.
"Whether revenue progresses toward the FY2026, FY2027 and FY2028 consensus estimates of US$7.814b, US$8.056b and US$8.310b."
What happens if one pressure point on Corteva’s profitability shifts just as exporter confidence returns will do a lot of the heavy lifting.
Corteva is a pure-play agriculture supplier built around crop protection, with Crop Protection revenue of about US$7.675b and a segment adjustment of US$2.707b, and a market value of roughly US$6.3b.
If that shift in profitability is what you care about, the full narrative for Corteva shows how trade driven demand could accelerate or stall Corteva’s earnings mix.

Bunge Global (BG)
Bunge Global is one of the clearest US export plays in this screen, sitting at the junction between American grain and oilseed flows and global demand, where any thaw in US China trade can quickly reshape volumes and crush economics. This is exactly what the bullish analyst Narrative on Simply Wall St focuses on.
Bunge Global runs a worldwide agribusiness and food platform built around soybean processing, other oilseeds and grain merchandising that links US farms to overseas buyers. Revenue is anchored in Soybean Processing and Refining at about US$44.9b, Grain Merchandising and Milling at roughly US$30.2b, Softseed Processing and Refining at around US$18.4b, and Tropical Oils and Specialty Ingredients at about US$5.3b, with eliminations and Corporate and Other adjusting the total. The stock carries a market value near US$19.5b.
"Portfolio pruning following the agreed sale of two non core Brazilian sugarcane mills creates room for Bunge Global to recycle capital and management attention into higher return grain, oilseed and value added processing activities, which can support segment margins and return on invested capital."
What happens when a single shift in how Bunge Global mixes export volumes and higher return projects flows through to crush spreads and overall profitability will matter a lot.
If you want to see how that export and project mix might be accelerating or masking the real opportunity, read the full narrative for Bunge Global for the bigger picture.

Seeking Fresh Alternatives Before They Fly
Opportunities move fast. Fresh ideas gain momentum, old ones get caught, and entry points drop out of reach before the crowd reacts. Scan these curated shortlists while it matters and get in early.
- Spot resilient cash generators early and run through a curated list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center before everyone else reacts.
- Chase income while prices still look reasonable by tracking high-yield candidates in the curated 6 dividend fortresses that focuses on durability as much as headline yield.
- Target future-facing infrastructure and review a handpicked 53 AI infrastructure stocks built around businesses supplying the hardware backbone behind AI demand while it remains under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com