
What BorgWarner (BWA)'s Data Center Power Push Means For Shareholders
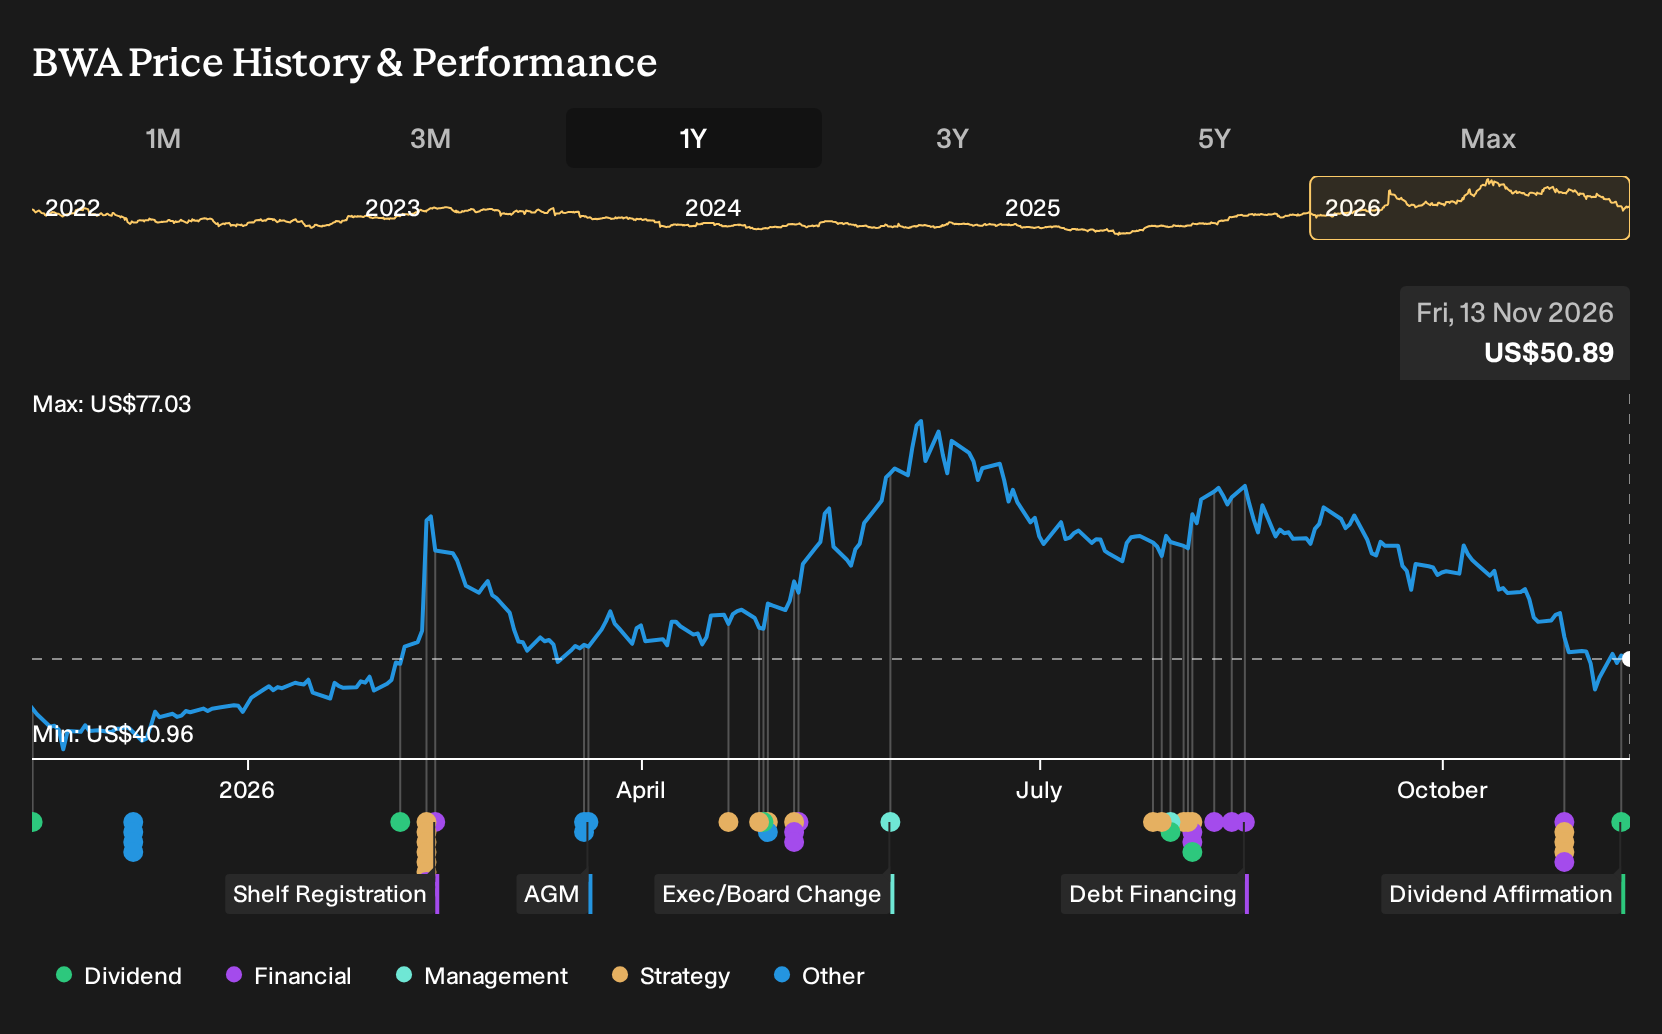
- BorgWarner confirmed that Tonit Calaway will retire from her executive roles in March 2027 and continue as a consultant through March 2028. The board also appointed Rajesh Kalathur to the Audit Committee and affirmed a quarterly dividend of US$0.17 per share payable on 15 December 2026.
- The company also outlined expectations for about US$300 million in 2027 revenue from its turbine generator data center power business and plans for additional data center focused products. Management highlighted a push to build earnings streams that are less tied to light vehicle cycles while managing inflation in electronic components and modest automotive demand.
- We will now look at how BorgWarner's investment narrative could be influenced by its push into data center power and turbine generators.
Scan BorgWarner's move into data center power in the context of a broader range of electrification and infrastructure opportunities by reviewing the hand picked 44 power grid technology and infrastructure stocks shaping this theme.
BorgWarner Investment Narrative Recap
BorgWarner asks you to believe it can use its combustion, hybrid and EV portfolio to fund a pivot into higher quality earnings streams across data center and industrial power. The analyst consensus Narrative on Simply Wall St leans on that shift, with turbine generators and related products helping offset a battery segment that is already a drag on organic sales and margins.
The most important short term test is execution on the new data center programs while managing modest automotive demand and inflation in electronic components. Recent board and executive changes, along with a maintained dividend, do not materially change that near term equation or the key risk that legacy combustion products see faster regulatory or customer pressure.
The dividend affirmation of US$0.17 per share for December 2026 is the clearest current signal about how BorgWarner sees its cash generation against these moving pieces. A regular payout can matter if you are weighing how much balance sheet flexibility exists as the firm invests in the 2 GW turbine generator facility and related data center power products.
That dividend sits alongside capital allocation priorities in the analyst consensus Narrative on Simply Wall St, which highlights a return hurdle of 15% or higher for new projects and a buyback authorization through 2029. For catalysts around the stock, the key question is whether turbine generator revenue of about US$300 million in 2027 plus industrial power products eventually more than offset the headwind from the shrinking battery business without stretching that cash return framework.
BorgWarner's narrative projects US$16.8b revenue and US$1.1b earnings by 2029. This reflects an assumed 5.7% yearly revenue growth and an earnings increase of about US$622m from current earnings of US$478m.
Uncover why BorgWarner's fair value indicates a 55% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame BorgWarner’s turbine generator and storage rollout as the real swing factor. Before this board and dividend news, they were modelling revenue of about US$17.0b and earnings around US$1.4b by 2029, far above consensus. You can treat those forecasts as one end of a wide opinion spectrum, which might shift as governance and data center plans evolve.
Explore 3 other BorgWarner fair value estimates, including one that suggests as much as 104% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BorgWarner research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BorgWarner. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BorgWarner's overall financial health at a glance.
Looking for more investment ideas beyond BorgWarner?
If the BorgWarner story has you thinking about portfolio upgrades, it can help to line it up against other opportunities with cleaner balance sheets, different risk profiles, or deeper value potential. The Simply Wall St Screener lets you do that in a structured way rather than hopping from ticker to ticker.
- If capital strength matters most to you, start with a list of solid balance sheet and fundamentals (24 results) that can help filter for businesses with sturdier financial footing.
- For investors hunting for mispriced opportunities, scan a 34 high quality undervalued stocks that combine quality fundamentals with room for the market to re-rate them.
- When steadier profiles appeal more than big swings, focus on a 30 resilient stocks with low risk scores that filters for companies with lower risk scores and more resilient characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com