
Will Net Sales Growth Change Buckle's (BKE) Narrative
- Buckle reported sales results for the 4 week, 13 week third quarter, and 39 week period ended October 31, 2026, with comparable store net sales mixed but total net sales for each period higher than the prior year.
- The combination of a slight comparable sales decline in the latest 4 week period and higher net sales over the quarter and year to date suggests that store productivity and broader demand trends may be pulling in different directions for Buckle.
- This raises questions about how Buckle's higher quarterly and year to date net sales relate to the longer term investment narrative around execution.
Spot similar retail stories where sales momentum and store efficiency may be pulling in different directions by checking our hand picked list of 34 high quality undervalued stocks for comparison.
Buckle Investment Narrative Recap
To own Buckle, you need to believe the retailer can keep store productivity and merchandise margins healthy enough to offset rising occupancy and SG&A costs that the analyst consensus Narrative on Simply Wall St highlights. The latest update shows modest comparable sales softness for the 4 week period but higher net sales for the quarter and year to date, which does not materially shift that near term story.
The key short term swing factor still sits in execution around women’s, kids and private label, which have been the volume and margin supports when men’s and footwear lag. The main risk remains that heavier spending on stores and marketing adds cost faster than traffic and basket size respond, which would squeeze earnings rather than support them.
The recent sales release itself is the most relevant announcement for Buckle right now, because it directly ties into the catalysts around category mix and store investments. Comparable sales moved slightly lower in the most recent 4 weeks, while the 13 week quarter and 39 week period showed higher comps and net sales against the prior year.
For an investor, that combination keeps the focus on whether women’s, kids and private label can keep carrying the load if weaker men’s and footwear trends persist. It also matters for the view that ongoing remodels, relocations and new locations can support enough throughput to balance higher rent, depreciation and SG&A that were already pressuring margins earlier in 2026.
Buckle's narrative projects revenue of about US$1.5b and earnings of US$212.4m by 2029. This rests on analysts modeling 4.2% yearly revenue growth and an earnings decline of roughly US$8.4m from current earnings of US$220.8m.
Uncover why Buckle's fair value indicates a 6% potential upside to its current price that could narrow quickly.
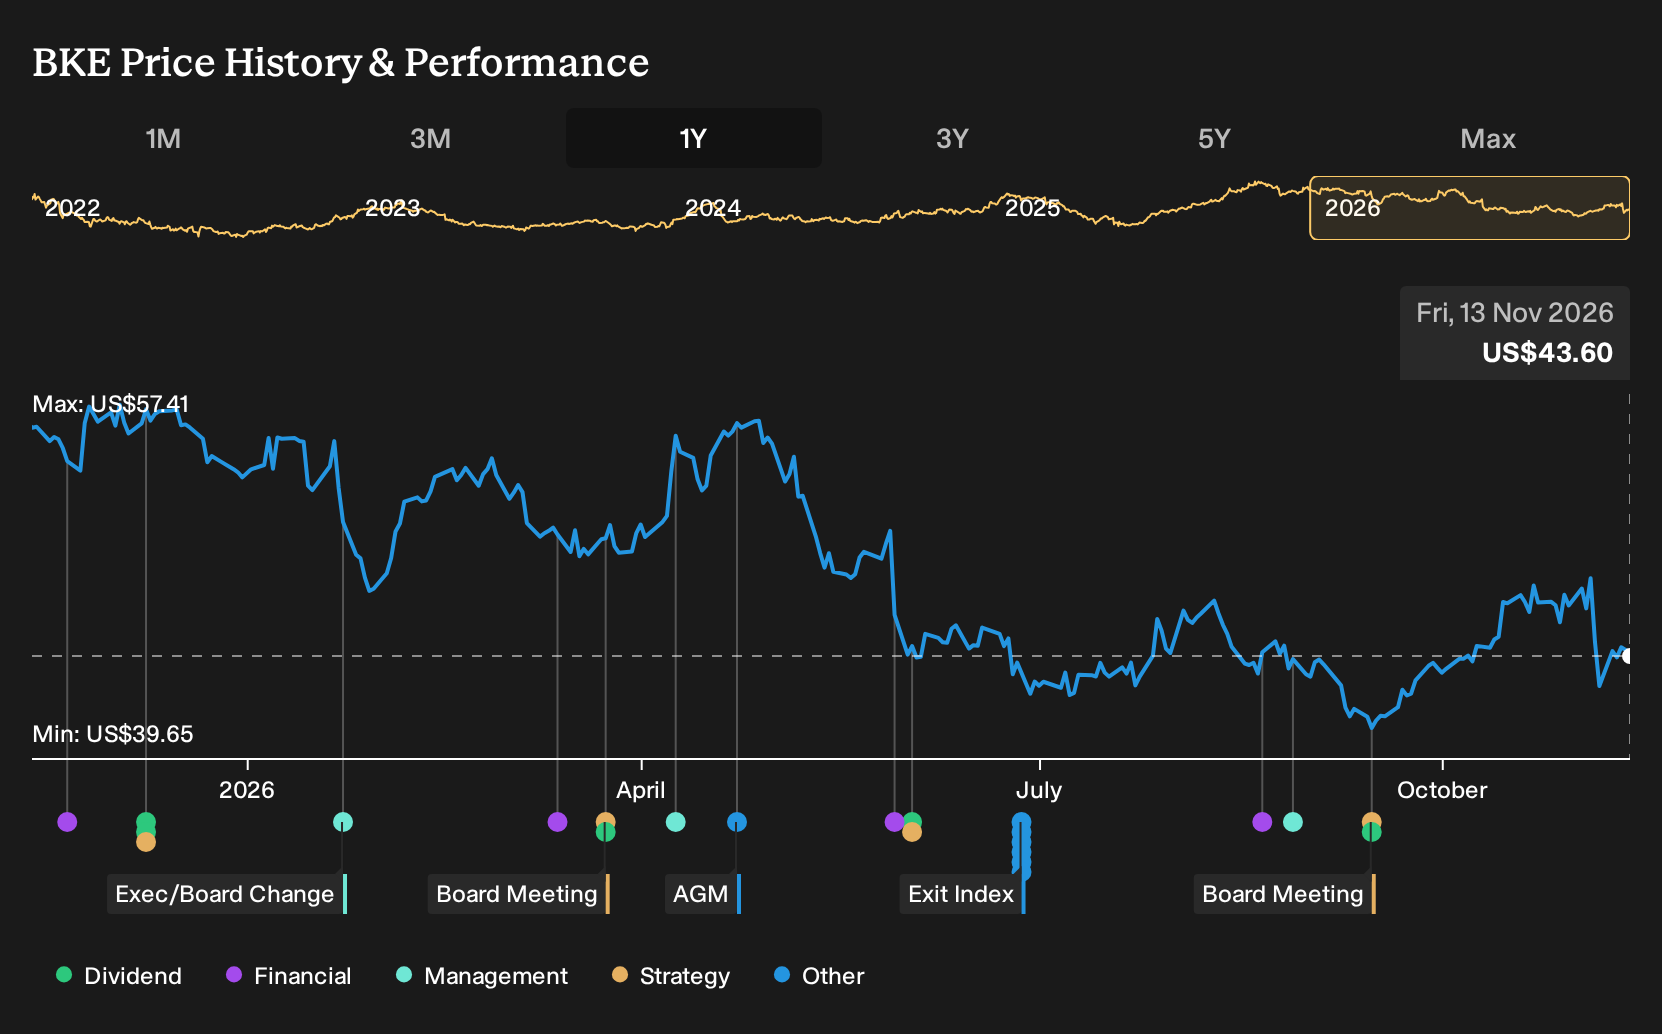
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$26 to about US$78, with the widest gap at the top end pointing to some members seeing Buckle as heavily mispriced. Those opinions were formed before the latest sales update. Consider the mix shift, margin pressure and store spending as live variables, and explore the full spread of views.
Explore 3 other Buckle fair value estimates, including one that suggests as much as 80% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Buckle research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Buckle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Buckle's overall financial health at a glance.
Looking for more investment ideas beyond Buckle?
Once you have formed a view on Buckle, it helps to widen the lens and compare it with other businesses that match your preferred style, risk level, and income needs. The Simply Wall St Screener can narrow that universe quickly so you spend more time assessing fundamentals and less time trawling through tickers.
- If capital preservation comes first for you, start with resilient candidates on our 30 resilient stocks with low risk scores that keep overall risk scores in check.
- For investors who want strong balance sheets to back up the story, filter for companies on the list of solid balance sheet and fundamentals (24 results) and see which ones line up with your quality bar.
- If you are hunting for opportunities that the market may be overlooking, scan through the 19 high quality undiscovered gems to spot lesser known businesses with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com