
Zillow Group (ZG) Climbed, But What Is Behind The Fresh Attention?
Zillow Group (ZG) just released third quarter and year to date results, reporting higher sales and revenue along with a shift from a small profit last year to a sizeable net loss.
The latest earnings announcement landed alongside a sharp reset in expectations. Zillow Group’s share price has fallen 54.11% year to date and the 1 year total shareholder return is down 55.20%, even after a 3.44% daily gain and weaker multi month share price momentum that hints at investors reassessing both growth potential and risk around the business model.
Scan how other real estate and property focused businesses are priced and growing right now by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) in this sector.
Zillow Group now has growing top line numbers alongside a swing into losses and a share price that has reset hard. Does that combination leave the stock looking mispriced or fairly valued today?
Most Popular Narrative: 34% Undervalued
The analyst consensus Narrative on Simply Wall St sets a fair value of $45.59 for Zillow Group compared with a last close of $30.11. That gap frames a view that current pricing leaves meaningful upside if the long term revenue and earnings path plays out as expected.
The shift toward integrated, end to end digital transaction ecosystems (such as Zillow 360 and Enhanced Markets) is enabling Zillow to capture more ancillary services revenue (mortgages, rentals, software). This is reducing dependence on advertising and expanding top line growth, as well as supporting EBITDA margin expansion through operational efficiencies. Secular tailwinds from increased mobility, remote work, and persistent demand for digital home search and rental tools are continuing to boost transaction volumes and the need for data rich, tech enabled real estate solutions. This underpins Zillow's user growth, increased monetizable connections, and ultimately revenue potential even in a flat macro housing environment.
See why 27 investors see Zillow Group as 34% undervalued.
Result: Fair Value of $45.59 (UNDERVALUED)
Still, pressure on US housing activity and the heavy reliance on Premier Agent and advertising spend could undermine the Zillow Group upside narrative if conditions remain challenging.
Find out about the key risks to this Zillow Group narrative.
Another View: What P/S Says About Zillow Group
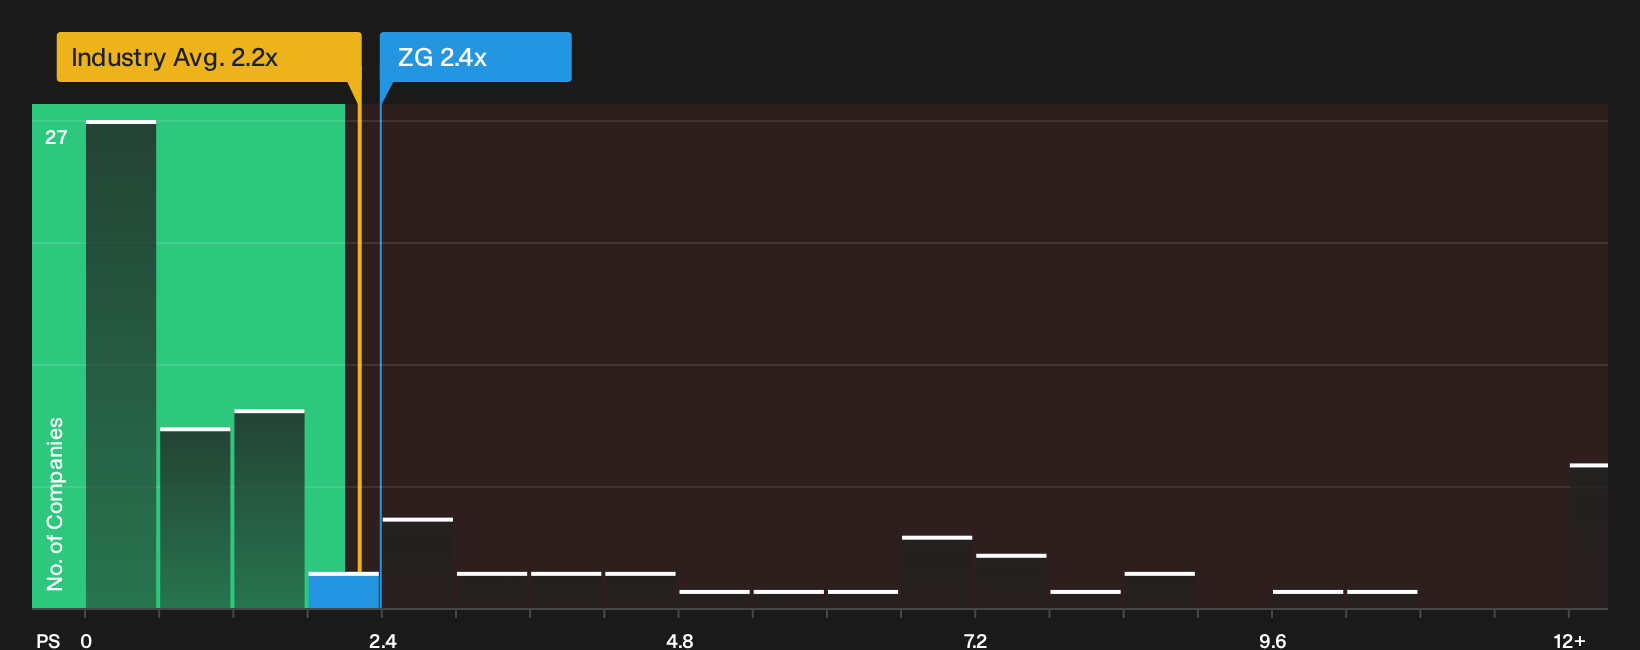
The SWS DCF model points to upside for Zillow Group, yet the simpler P/S lens sends a cooler message. ZG trades at a P/S of 2.4x, richer than the US Real Estate industry on 2.2x and well above peers at 1.2x. The fair ratio sits at 2.7x, which still leaves you weighing whether the premium signals quality or just extra risk.
To see how this price tag lines up against the underlying numbers in more detail, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Zillow Group value are one thing; your own judgment is another, so move fast to review the key positives investors are watching in the 2 key rewards.
Looking for more investment ideas beyond Zillow Group?
If Zillow Group has you rethinking your watchlist, now is the moment to widen the lens and line up a few fresh ideas that fit your style.
- Target resilient balance sheets and steadier fundamentals by scanning the curated 30 resilient stocks with low risk scores that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced opportunities by reviewing the focused 19 high quality undiscovered gems and spot solid businesses that fewer investors are paying attention to.
- Build a watchlist of potential breakout values by checking the carefully filtered 34 high quality undervalued stocks before the rest of the market catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com