
What NKT Doubters Overlooked
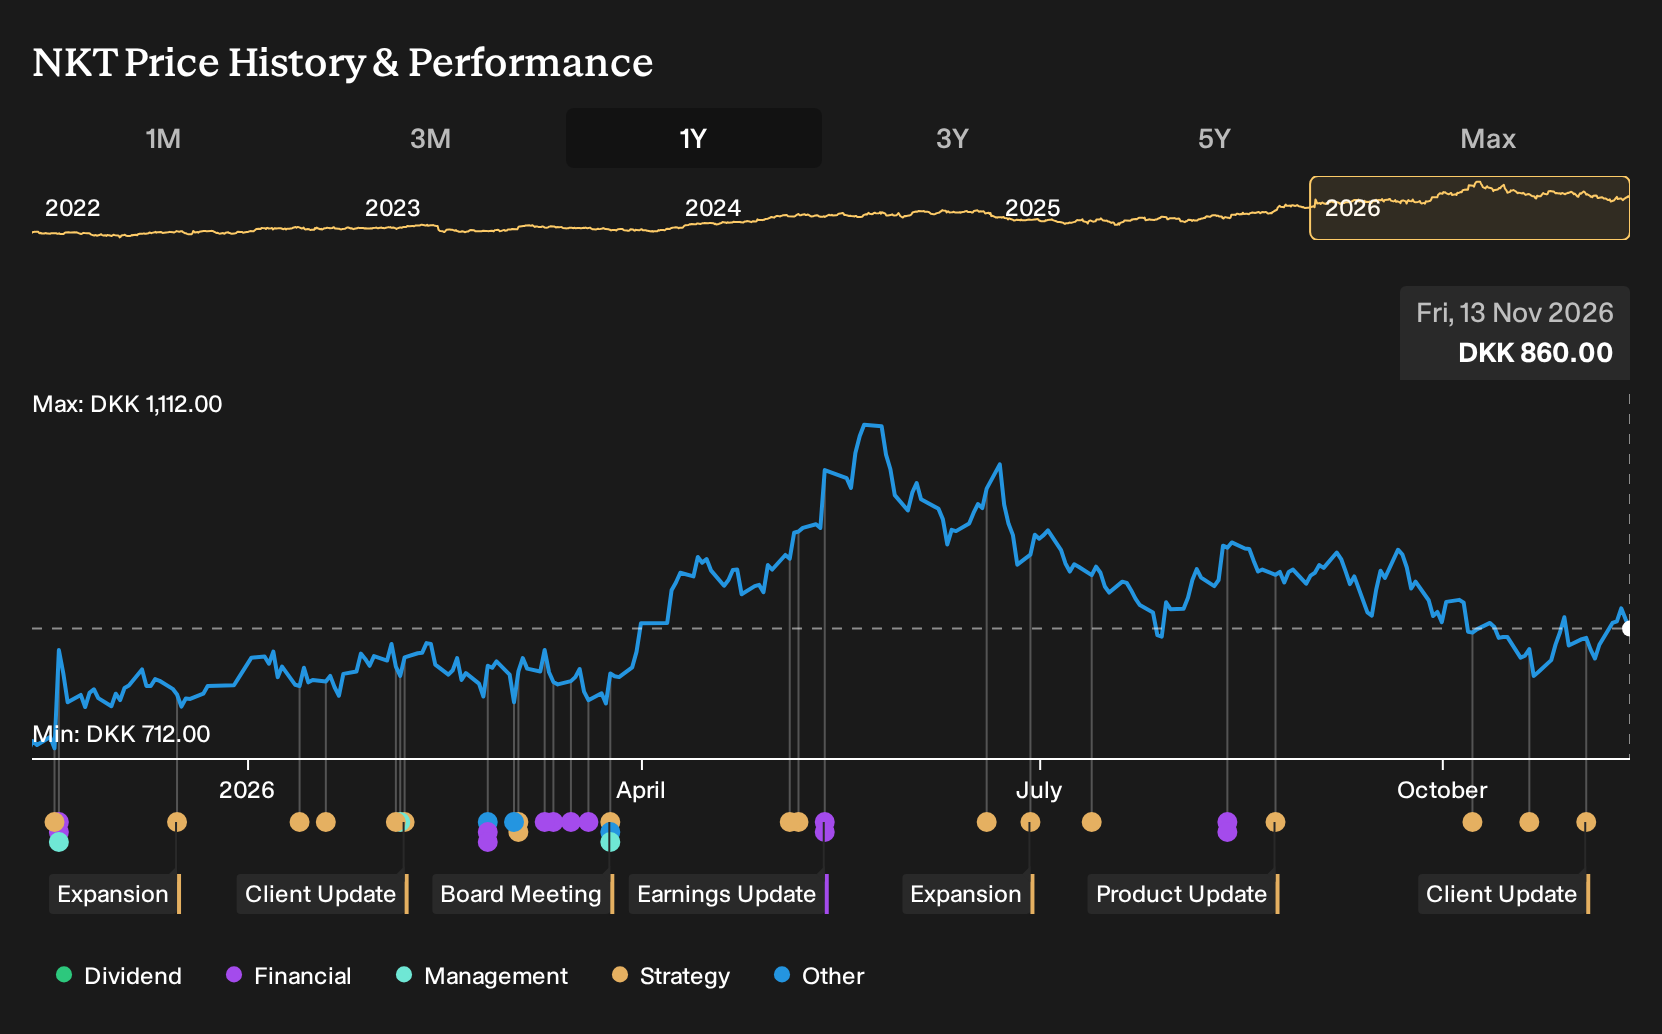
NKT did not spend the year talking about abstractions. It won three high-voltage cable contracts for Hamburg’s Grid of the Future programme and pushed deeper into European grid upgrades with concrete work. For NKT shareholders, the return over the past year was 20.1%, including dividends. If you had been weighing a purchase back on 13 November 2025, what would you have needed to believe about margins, backlog quality, and project execution to justify that decision?
NKT has already moved. Pinpoint other ways to investigate the theme among 44 power grid technology and infrastructure stocks.
The Two Stories Investors Had To Choose Between On NKT
The shares cost DKK721 at the start of the period, so anyone looking at NKT had to decide whether that price already captured the grid boom story or still left room for upside.
The bullish narrative pointed to a Fair Value of DKK843, a price level implied by assumptions of 10.7% annual revenue growth and profit margins rising from 6.0% to 7.2% by 2028 as high voltage projects and new capacity kicked in.
The more cautious narrative pointed to a Fair Value of DKK600, based on 7.6% yearly revenue growth, margin expansion to 7.5%, and concern that heavy €2.0b CapEx and backlog concentration with European TSOs could strain cash flows and flexibility.
What The Evidence Did To The NKT Argument
The clearest new fact for NKT was operational. The group reported Q2 2026 revenue of €947m and net income of €51m, the same profit as Q2 2025. That kept the net margin flat at 5.4%. Record backlog, new 525 kV HVDC qualifications, and a €50m Portuguese plant expansion supported the bullish demand story, but profitability progress lagged. Overall, the evidence cut both ways.
The key assumption investors had been testing was margin expansion on top of a swelling order book. When you look at another grid supplier, track whether backlog growth is showing up in higher reported margin and absolute earnings, not just bigger project headlines.
What NKT's Recent Run Already Prices In
NKT now trades at DKK860 after a 20.1% gain over the past year. The bearish analyst Narrative on Simply Wall St sees its Fair Value below that level, arguing the current quote leans heavily on execution rather than offering clear valuation slack.
This Narrative focuses on whether heavy grid capex, flat high voltage capacity and input cost swings can still translate a large backlog into stronger, cleaner cash earnings. Anyone paying today’s price needs confidence that the investment wave finishes on time and that the extra capacity is filled at solid margin quality.
"Rising revenue at standard metal prices and higher operational EBITDA guidance for 2026 rest heavily on a rapidly expanded transmission and grid solutions backlog. At the same time, the ongoing capex ramp, input cost pressures and the guidance for later free cash flow inflection suggest that if new high voltage capacity and lifecycle service offerings are not filled at the expected margin quality, future earnings and return on capital could fall short of current long term ambitions."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 42% below our estimate - helps large online platforms accept and send local payments as transaction volumes broaden.
- Company 2 - 29% below our estimate - executes large onshore and offshore wind projects while growing higher margin service contracts.
- Company 3 - 43% below our estimate - opens new entertainment centres while using pricing and AI tools to protect profitability.
Those are three of them. See all 200 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com