
Is Dole (DOLE) Cheap Following Strong Quarterly Earnings?
Dole (NYSE:DOLE) just put fresh numbers on the table for the quarter ended September 30, 2026, reporting higher sales and net income alongside a declared dividend and lower reported impairment charges.
Recent trading suggests investors are treating Dole’s latest earnings as a mild positive. A 30-day share price return of 7.67% and a 90-day gain of 10.75% are building short term momentum, while the 3-year total shareholder return of 37.73% points to a sturdier long haul record, despite a small year to date share price decline of 2.12% and only a 5.14% total shareholder return over the past year.
Spot emerging momentum across fresh food and consumer staples by comparing Dole’s latest move with our curated 34 high quality undervalued stocks.Dole now trades in the low teens while analyst targets and some intrinsic value estimates sit noticeably higher. Is that gap a genuine margin of safety, or is it a value trap waiting to close?
Most Popular Narrative: 17.9% Undervalued
Dole closed at $14.32, while the analyst consensus Narrative on Simply Wall St calculates a fair value of about $17.44 using an 8.12% discount rate and explicit revenue and earnings forecasts. That gap anchors a thesis that future efficiency gains and portfolio moves matter more than short term noise.
The main thing that has to go right is that Dole successfully redirects capital and management focus toward higher return segments, automation projects, and portfolio pruning, so that earnings power improves rather than just balance sheet strength.
The current valuation implies the market is pricing Dole as if cost inflation, legal risk, and segment volatility will cap earnings momentum, which leaves room for potential upside if the company’s diversification, deleveraging, and efficiency efforts gain more credit over time.
See why 10 investors see Dole as 18% undervalued.
Result: Fair Value of $17.44 (UNDERVALUED)
Still, fresh fruit cost pressures and the legal case in Hawaii could restrict Dole’s margin progress and absorb cash that investors might prefer to see used elsewhere.
Find out about the key risks to this Dole narrative.
Another View: Dole Through The Earnings Lens
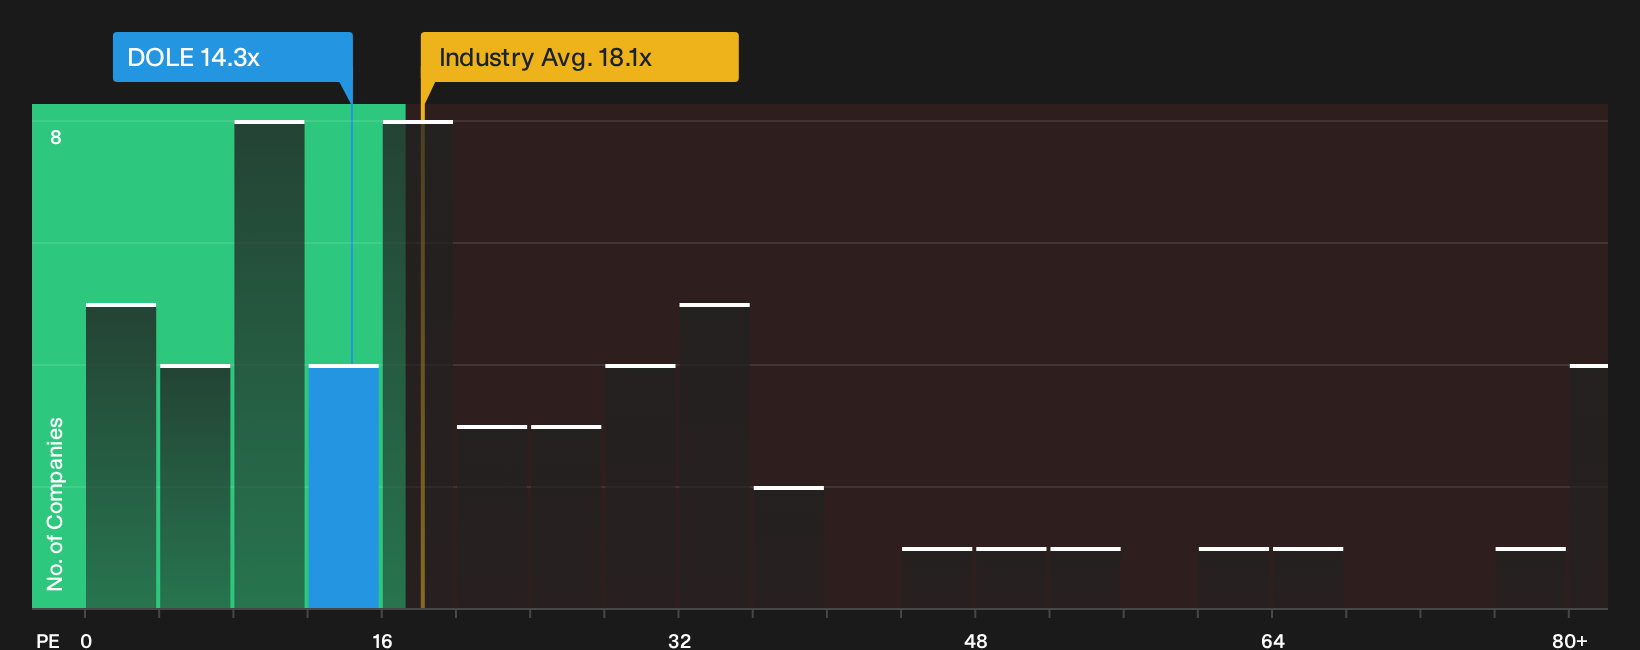
There is a twist when looking at Dole through earnings multiples instead of fair value estimates. The stock trades on a P/E of 14.3x, slightly above a fair ratio of 14x, yet below the US Food industry at 18.1x and peers at 24.3x. That mix points to modest valuation risk on one side and possible relative opportunity on the other. The key question is which matters more for you as an investor.
To pressure test how much weight to give this earnings based view versus intrinsic value estimates, and to see how the fair ratio could shift if margins or growth assumptions change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling cautious after weighing both sides of the Dole story is reasonable. At the same time, the clock is always ticking on new information. Put the recent figures in context for yourself by reviewing the 3 key rewards
Looking for more investment ideas beyond Dole?
If Dole’s story has you thinking about what else might be hiding in plain sight, use the same curiosity to scan other corners of the market.
- Target resilient balance sheets and healthier fundamentals by running your own shortlist through our list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by zeroing in on companies that pass our high bar in the 34 high quality undervalued stocks.
- Build a cash flow focused watchlist by sorting for income ideas inside the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com