
3 Canadian Energy Stocks With Earnings Growth Over 77%
Europe is racing to electrify everything from heating to heavy industry, yet recent reports flag tight natural gas stockpiles heading into winter and persistent worries about energy security. That keeps global attention on large oil and gas suppliers, including Canadian producers. For investors, this creates a live question: Who could benefit if energy reliability stays in focus? This article profiles 3 Canadian oil and gas stocks from our screener.
The stocks highlighted below are just a starter set, and the full screen surfaced 44 more oil and gas companies with equally compelling narratives that are not covered here. To identify your own highest conviction ideas, go straight to the Oil and Gas screener to filter and analyze the wider opportunity set.
Spartan Delta (TSX:SDE)
Spartan Delta is a Calgary based upstream producer focused on exploring, developing, and producing crude oil and natural gas in Western Canada, with all CA$611 million of recent revenue coming from oil and gas reserves work. The business is fully North America focused and carries a market value of about CA$2.3b.
For pure exposure to Canadian upstream output, Spartan Delta offers concentrated oil and gas production in the Duvernay and Deep Basin, rising liquids volumes, and a multi year capital plan. Investors watching this theme may focus on how that level of spending affects cash generation if a single key assumption changes.
If that single assumption is wrong, the DCF valuation analysis for Spartan Delta can show how sensitive Spartan Delta might be if cash generation and spending start to decouple.
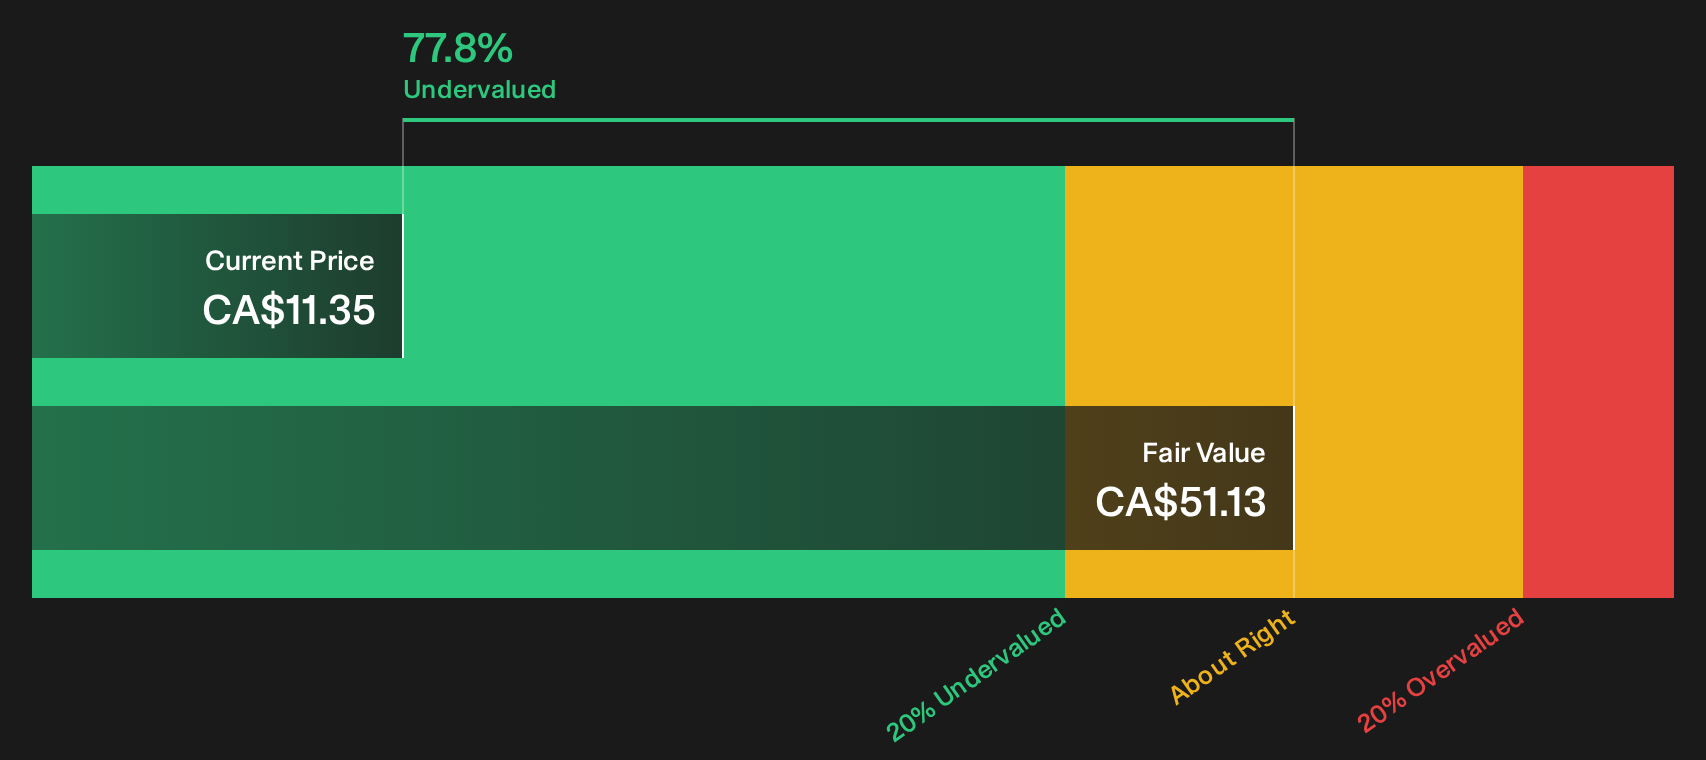
Cenovus Energy (TSX:CVE)
Cenovus Energy is a large integrated oil and gas player, pairing oil sands production in Alberta and Saskatchewan with refining operations that turn crude into gasoline, diesel, jet fuel, and asphalt. Upstream oil sands bring in about CA$34.8b of revenue, with CA$3.5b from conventional assets and CA$1.8b from offshore, while U.S. and Canadian refining add roughly CA$21.6b and CA$6.1b. The business carries a market value of about CA$75.0b.
Cenovus Energy provides direct oil sands exposure plus downstream refining tied to the same barrel, which is why it features in this Oil and Gas screen. The analyst consensus Narrative on Simply Wall St describes how that integrated setup influences expectations for production, cash generation, and future returns.
"Successful completion of key growth projects such as Narrows Lake, West White Rose, and the Foster Creek optimization is set to deliver significant new, stable, long-life production with lower steam oil ratios and reduced capital spending needs moving forward, positioning Cenovus Energy for higher free cash flow and earnings."
The key variable is how one unseen cost pressure ultimately filters through Cenovus Energy's margins if conditions shift at the wrong time.
When that cost pressure bites, the full narrative for Cenovus Energy explains how Cenovus Energy's integrated setup could either keep cash flows accelerating or risk quietly stalling margins.

Suncor Energy (TSX:SU)
Suncor Energy is a large integrated oil and gas producer centered on Canadian oil sands, where it extracts and upgrades bitumen, then refines and sells fuels and petrochemical products across North America. Oil Sands generate about CA$28.4b of revenue, Refining and Marketing about CA$42.1b, and Exploration and Production roughly CA$2.7b, supporting a market value near CA$114.7b.
Suncor Energy brings together large scale oil sands production and high utilization refineries, which is why it features in this Oil and Gas screen. The bearish analyst Narrative on Simply Wall St sets out one of the key pressure points investors need to watch.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
What happens to Suncor Energy's cash generation depends heavily on how one less visible constraint shapes future margins when conditions shift.
If that hidden constraint is what you care about, read the full narrative for Suncor Energy to see whether refinery intensity is masking risk or accelerating opportunity.

Seeking Alternatives Beyond Oil And Gas?
Fresh ideas move first. Markets reprice fast, and the best stories rarely stay under the radar for long. Scan these focused shortlists before momentum is fully established. Consider these options.
- Target steady income streams before yields are compressed by demand crowding into quality. Check out a curated set of 3 dividend fortresses built for staying power.
- Spot potential developments in artificial intelligence while the stories are still forming. Work through a filtered group of 43 profitable AI stocks that aren't just burning cash with real earnings behind the buzz.
- Seek exposure to key materials involved in electrification before prices reflect peak optimism. Review a focused universe of 17 top copper producer stocks that aligns with long term infrastructure build outs.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com