
Applied Optoelectronics (AAOI) Dropped, So What Is Behind The Renewed Attention?
Why Applied Optoelectronics Stock Is Back In Focus
Applied Optoelectronics (AAOI) just paired a swing to quarterly profitability with new revenue guidance that points to sustained demand from AI data center customers, putting the stock firmly back on investor watchlists.
Recent enthusiasm around Applied Optoelectronics has been tempered by volatility, with the share price down 5.6% over the last day and 33.98% over 30 days, yet still showing a 25.98% year to date share price gain and a very large 5 year total shareholder return above 7x. The sharp 90 day share price decline of 67.79% sits alongside a 132.42% 1 year total shareholder return and follows a cluster of events in early November 2026, including a swing to quarterly profit, new revenue guidance, a fresh credit facility, and the purchase of three large Houston manufacturing and warehouse buildings. Together, these developments indicate that investors are re-evaluating both growth potential and balance sheet risk.
Compare Applied Optoelectronics with other AI infrastructure players that have been hand-picked for strong fundamentals and momentum in our 53 AI infrastructure stocks
After a swing back to profit, a fresh credit line, and a sharp pullback in the share price, does Applied Optoelectronics still offer a skewed payoff for buyers, or has the easy part of the rerating already passed?
Most Popular Narrative: 54% Undervalued
Applied Optoelectronics closed at $49.89, compared with a fair value of $109 in the analyst consensus Narrative on Simply Wall St. This fair value is built from analyst targets and long term forecasts and then discounted at 8.97%.
Very strong demand visibility for 800G and 1.6T modules, including a multiyear agreement for 1.6T transceivers that is expected to generate between US$1.0b and US$1.5b of revenue and current 1.6T orders of roughly US$400 million to US$450 million, combined with management’s view that demand exceeds the company’s capacity through at least 2027, underpins the potential for sustained growth in revenue, gross margin and earnings as Applied Optoelectronics works through its capacity constraints.
See why 78 investors see Applied Optoelectronics as 54% undervalued.
Result: Fair Value of $109 (UNDERVALUED)
Still, the story around Applied Optoelectronics only holds if heavy capex and funding needs do not squeeze free cash flow or force value-draining dilution.
Find out about the key risks to this Applied Optoelectronics narrative.
Another View: What Multiples Say About Applied Optoelectronics
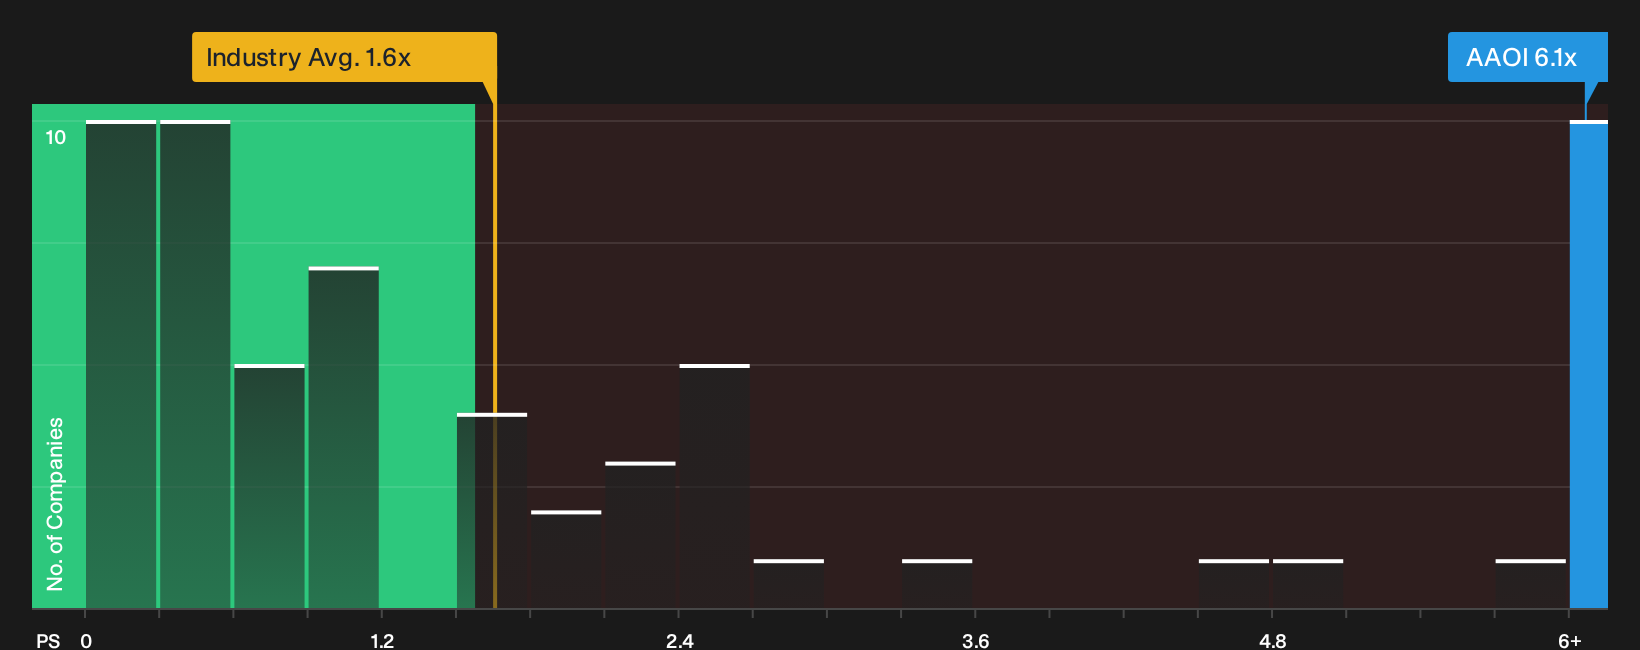
Analysts on Simply Wall St frame Applied Optoelectronics as undervalued relative to a $109 fair value, yet the current P/S of 6.1x is far above both the US Communications industry on 1.6x and peer average of 3.3x, even though the fair ratio model points to 15.1x. For investors, that mix of discount to one model and premium to direct comparables raises a simple question: Which crowd is pricing the risk more accurately?
For a closer read on how this pricing gap could matter to your own process, take a moment to walk through our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Applied Optoelectronics is split, with strong optimism about potential upside alongside clear concern about downside risk. Move quickly, review the underlying numbers yourself, and weigh both sides of the story in the 1 key reward and 3 important warning signs
Looking For More Investment Ideas Beyond Applied Optoelectronics?
If the Applied Optoelectronics story caught your attention, do not stop here. Broader idea hunting often reveals opportunities that a single ticker cannot show.
- Target stronger value setups by scanning companies that combine quality fundamentals with attractive pricing through the 34 high quality undervalued stocks.
- Strengthen your income plan by reviewing a curated pool of higher yielding payers in the 6 dividend fortresses.
- Reduce portfolio stress by focusing on sturdier balance sheets using the list of solid balance sheet and fundamentals (24 results).
Use these screeners now so you stay prepared for the next wave of opportunities instead of hearing about them only after they have become widely known.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com