
RELX (LSE:REL) Leans Further Into AI Analytics, Is The Valuation Still Cheap?
RELX (LSE:REL) is back in focus after fresh commentary highlighted how its LexisNexis and Elsevier franchises are supporting predictable cash flows and steady dividend increases, alongside a broader push into AI-powered analytics.
Recent trading has reflected that story. The share price is up 24.25% over the past 90 days and 5.32% over the past month. The 5 year total shareholder return of 43.70% points to longer term compounding that investors have rewarded despite more muted 1 year gains.
Scan beyond RELX and compare its AI-fuelled analytics story with peers on the 43 profitable AI stocks that aren't just burning cash that already back their ambitions with real earnings, not just promises.
After a 24.25% jump in 90 days, RELX now poses a simple question: accept the current price as the cost of quality, or wait for the market to offer a cheaper entry and risk missing it.
Most Popular Narrative: 11% Undervalued
RELX closed at £30.69, while the analyst consensus Narrative on Simply Wall St suggests a fair value of £34.46. This points to a modest discount and ties the AI story directly to reported revenue and profit metrics.
RELX's continued rollout and integration of advanced AI-powered analytics and decision tools across its Risk, STM and Legal segments is deepening customer value and increasing product adoption. Recent group underlying revenue growth of 7% and adjusted operating profit growth of 9% are cited in support of the view that this mix shift can continue to lift margins and earnings.
See why 86 investors see RELX as 11% undervalued.
Result: Fair Value of £34.46 (UNDERVALUED)
Still, the RELX story only holds if paid academic content and high priced legal tools remain attractive. Open access pressure and AI competitors could squeeze both.
Find out about the key risks to this RELX narrative.
Another View: What RELX’s P/E Is Telling You
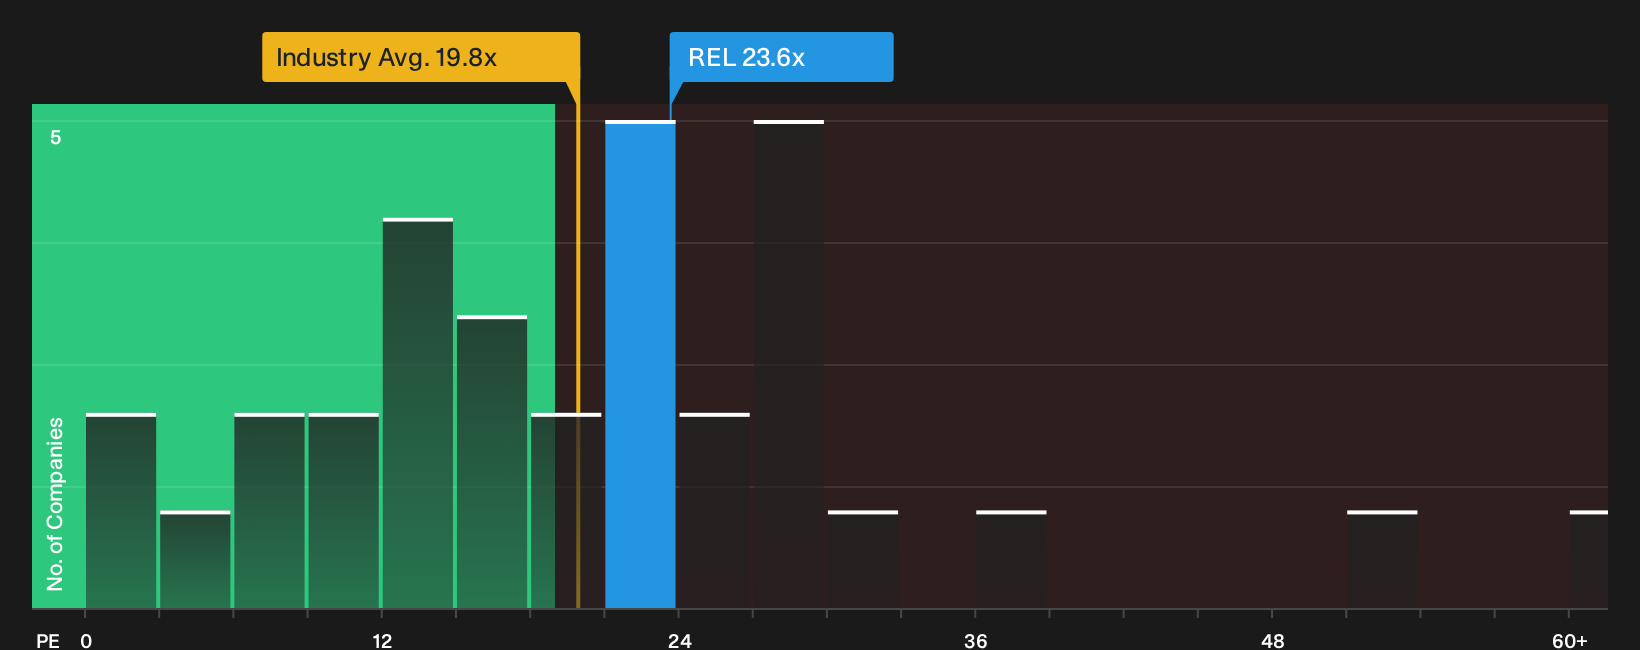
The first narrative leans on cash flows and a fair value of £34.46, yet the market’s current P/E of 23.6x sketches a different picture for RELX. That multiple sits above both the UK Professional Services average of 19.8x and a peer group at 20.9x, even though the fair ratio sits higher again at 34.2x.
So on earnings, the stock looks expensive versus sector and peers, but cheaper than where the fair ratio suggests the market could move. For you as an investor, that mixed signal raises a practical question: is paying up for perceived quality acceptable, or does that valuation gap feel like more downside risk than upside room?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on RELX valuation and quality can either feel exciting or uncomfortable, depending on your risk tolerance and time horizon. Act quickly, pull up the data, and pressure test both sides of the debate against the 4 key rewards and 1 important warning sign
Looking for more ideas beyond RELX?
If RELX now feels fully priced, broaden your opportunity set with a few focused stock lists that surface different types of potential winners.
- Target resilient compounding by scanning companies with strong cash generation and supportive valuations through the 14 high quality undervalued stocks.
- Lock in income-led returns by reviewing a curated set of higher yield payers using the 4 dividend fortresses.
- Prioritise resilience first and hunt for companies with sturdier finances and cleaner leverage profiles via the list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com