
Colliers International Group (TSX:CIGI) Could Be 40% Below Fair Value Following Q3 Guidance Cut
Colliers International Group (TSX:CIGI) moved into focus after its latest Q3 earnings report, which combined higher sales with sharply lower profit and a cut to full year revenue growth guidance.
Against that earnings backdrop, Colliers International Group’s share price tells a cautious story. The stock has fallen about 35.6% on a year to date share price basis, and the one year total shareholder return is down roughly 37.3%. The recent 1 day share price gain of 1.6% only partly offsets a 10.3% share price decline over the past three months as investors digest weaker profit and softer revenue guidance.
Compare Colliers International Group's setback with other real estate and infrastructure players by scanning list of solid balance sheet and fundamentals (6 results) for potential alternatives with stronger recent momentum and balance sheet support.
The recent slide in Colliers International Group looks tied to shrinking profit and softer guidance as much as mood swings in the market. The valuation question now is how that mix should be priced.
Most Popular Narrative: 40% Undervalued
On the analyst consensus Narrative on Simply Wall St, Colliers International Group screens as undervalued, with a fair value of roughly CA$213.20 against a last close of CA$128.49. This pushes the discussion toward what has to go right for that gap to close.
The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins.
The expanded focus on recurring outsourcing services and professional advisory, underpinned by demand for ESG and sustainability expertise, is increasing high-quality, stable revenue streams, leading to improved net margins and stronger earnings defensibility through economic cycles.
See why 7 investors see Colliers International Group as 40% undervalued.
Result: Fair Value of CA$213.20 (UNDERVALUED)
Still, the bullish narrative around Colliers International Group can quickly weaken if industrial leasing stays soft, or if acquisition heavy growth creates integration and margin pressures.
Find out about the key risks to this Colliers International Group narrative.
Another View: Colliers International Group Looks Expensive On Earnings
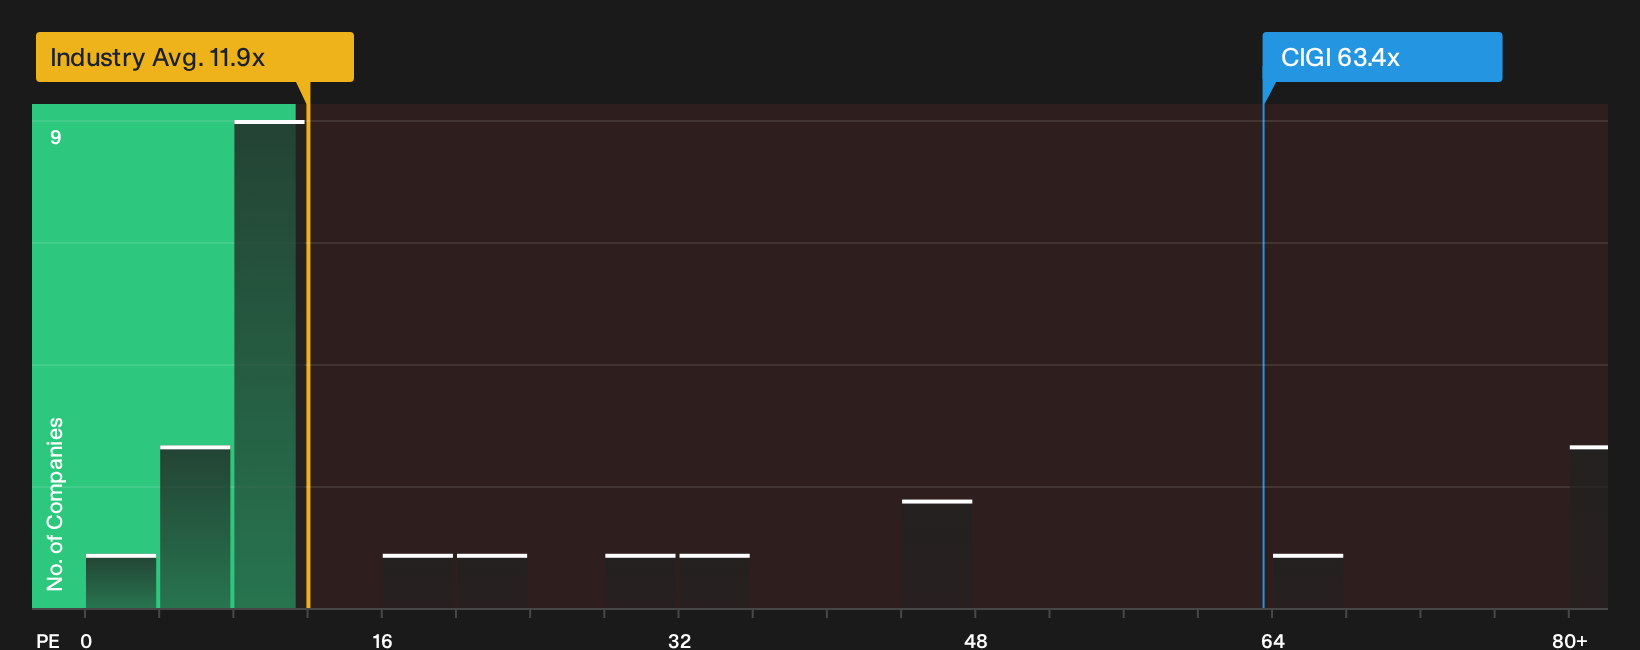
The analyst narrative leans on a fair value of CA$213.20, yet the current P/E ratio of around 63.4x puts Colliers International Group on a far richer earnings multiple than both the North American real estate industry at 11.2x and its peer group at 20.7x.
The fair ratio for Colliers International Group is estimated at 82.3x P/E, which implies the market could still justify a higher multiple if optimistic growth assumptions play out. That gap can be read as room for upside or simply extra valuation risk, depending on how much earnings acceleration you think is realistic.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Colliers International Group is clearly split. This is exactly why this is the moment to review the full picture and decide where you stand based on the underlying numbers, trends and risk markers, then weigh both sides of the story with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Colliers International Group?
If Colliers International Group has you thinking harder about valuation, use this moment to widen your opportunity set and pressure test your next move with fresh candidates.
- Target resilient balance sheets and steadier financial profiles by scanning the list of solid balance sheet and fundamentals (6 results) that pass strict quality filters.
- Hunt for mispriced quality by reviewing the 7 high quality undervalued stocks that combine stronger fundamentals with more modest expectations.
- Focus on income plus durability by checking the 3 dividend fortresses that pair higher yields with more robust financial backing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com