
How Drive Through Biometrics Will Impact Getlink (ENXTPA:GET) Investors
- Getlink reported October 2026 Eurotunnel figures showing LeShuttle Freight carried 105,411 trucks and LeShuttle moved 162,655 passenger vehicles, while also confirming year to date volumes and newly approved drive through biometric passport and fingerprint checks at Folkestone and Calais.
- The combination of detailed traffic data and in car biometric controls highlights how Getlink is focusing on throughput reliability, regulatory compliance and border processing efficiency across both freight and passenger flows.
- The next area of attention will be how Getlink's investment narrative could be influenced by in car biometric checks at Eurotunnel terminals.
Scan how Getlink fits into the broader transport and infrastructure story by comparing it with hand picked peers screened for list of solid balance sheet and fundamentals (198 results)
What Is Getlink's Investment Narrative?
To own Getlink, you have to buy into a fairly simple idea. A hard asset with tight capacity, a cross Channel rail link, throws off cash if it stays busy and runs on time. October traffic data points to solid usage across trucks and passenger vehicles, even though year to date car volumes are slightly lower than a year earlier. The new in car biometric checks sit right on top of that thesis. They are meant to keep throughput predictable while border rules get tougher, rather than let queues undermine the appeal of the tunnel.
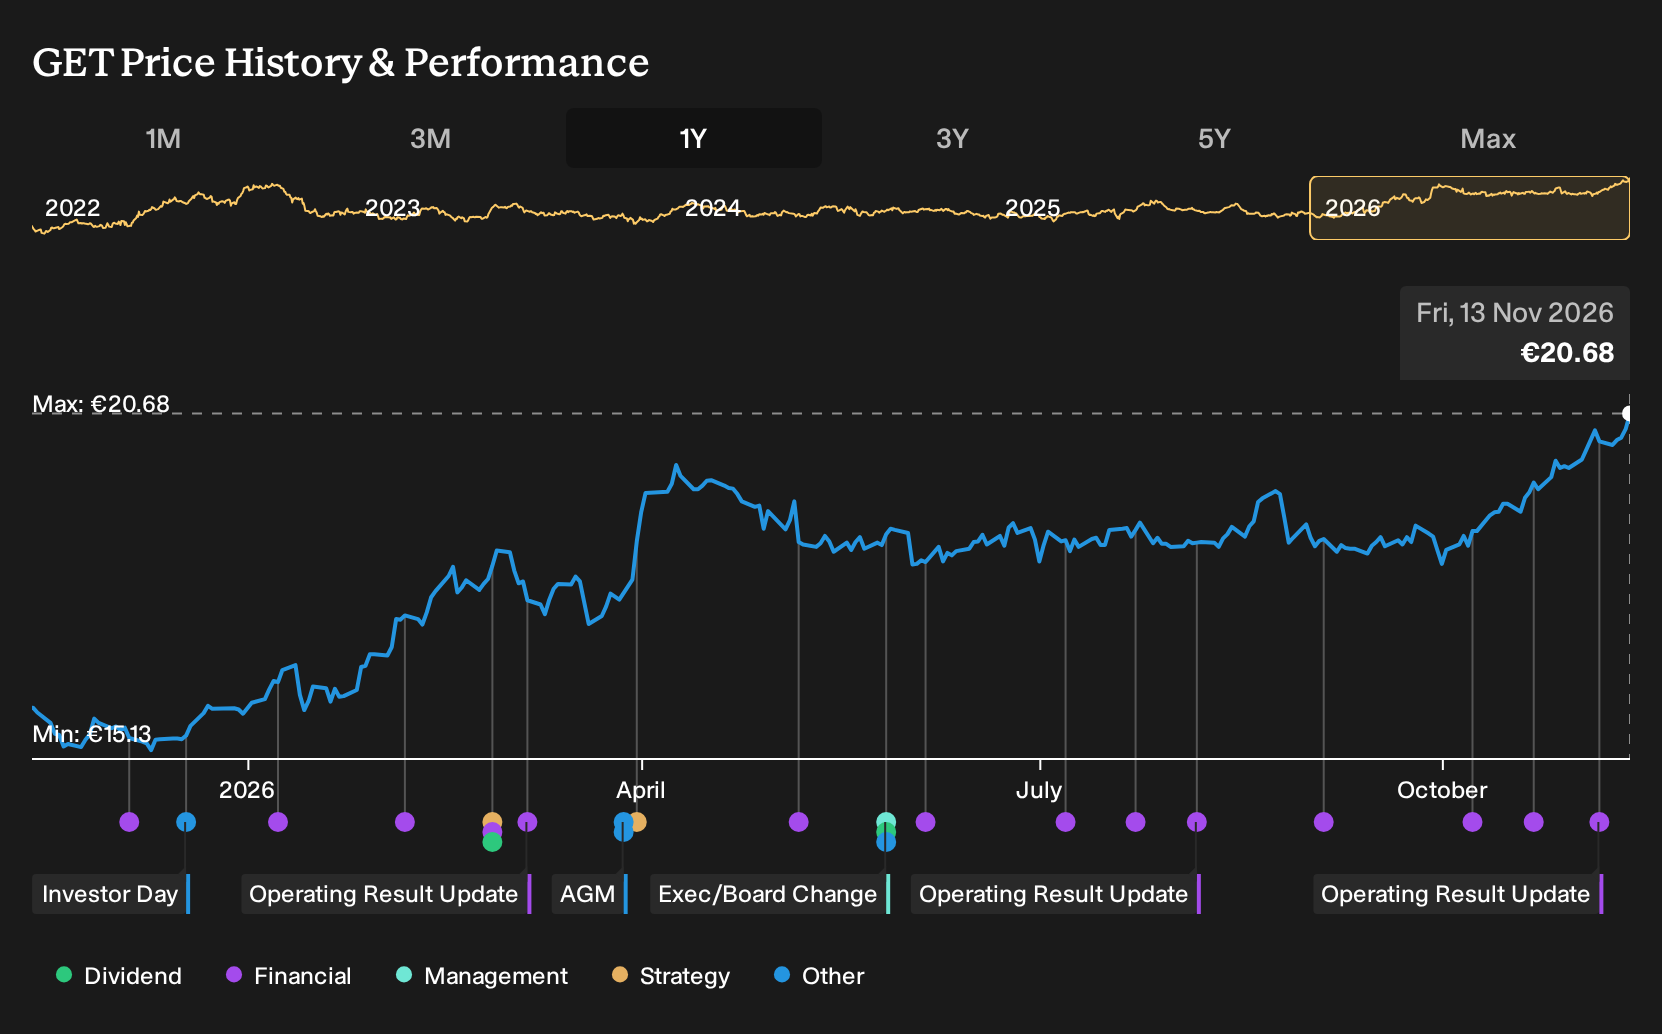
In the short term, the key swing factors are still execution and capital discipline. Drive through biometrics look operationally important, but they do not change that this is a capital intensive asset with debt that is not well covered by operating cash flow and a dividend flagged as not well covered by earnings. With the share price already up strongly over one and five years and the stock on a 34.5x P/E versus much lower peer and sector multiples, you are paying a premium for Getlink's infrastructure story and relying on management to keep the asset sweating without stretching the balance sheet.
Even so, there is a specific pressure point in this story that could matter far more than a single month of traffic numbers or a new passport gate...
There's only one way to know the right time to buy, sell or hold Getlink. Head to Simply Wall St's company report for the latest analysis of Getlink's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Getlink between €12.63 and €19.90, which already shows how far private investors can diverge. Both views were formed before the October traffic release and before the biometric announcement, so you are judging new information against stale models. That gap is exactly why it helps to compare several community viewpoints before leaning on any single number.
Explore another Getlink fair value estimate, including one that suggests as much as 39% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Getlink research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Getlink. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Getlink's overall financial health at a glance.
Looking For More Ideas Beyond Getlink?
If the Getlink story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you scan other opportunities quickly and with consistent data.
- For investors who care most about resilience, start with companies that score well on balance sheet strength through the 210 resilient stocks with low risk scores.
- If you prefer cash flow support and room for re rating, filter for stocks that screen as 200 high quality undervalued stocks on both quality and valuation grounds.
- Or, if you enjoy finding earlier stage situations before the crowd catches on, focus on businesses flagged as 567 high quality undiscovered gems with solid underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com