
Luxury Expansion Might Change The Case For Investing In IHG Stock
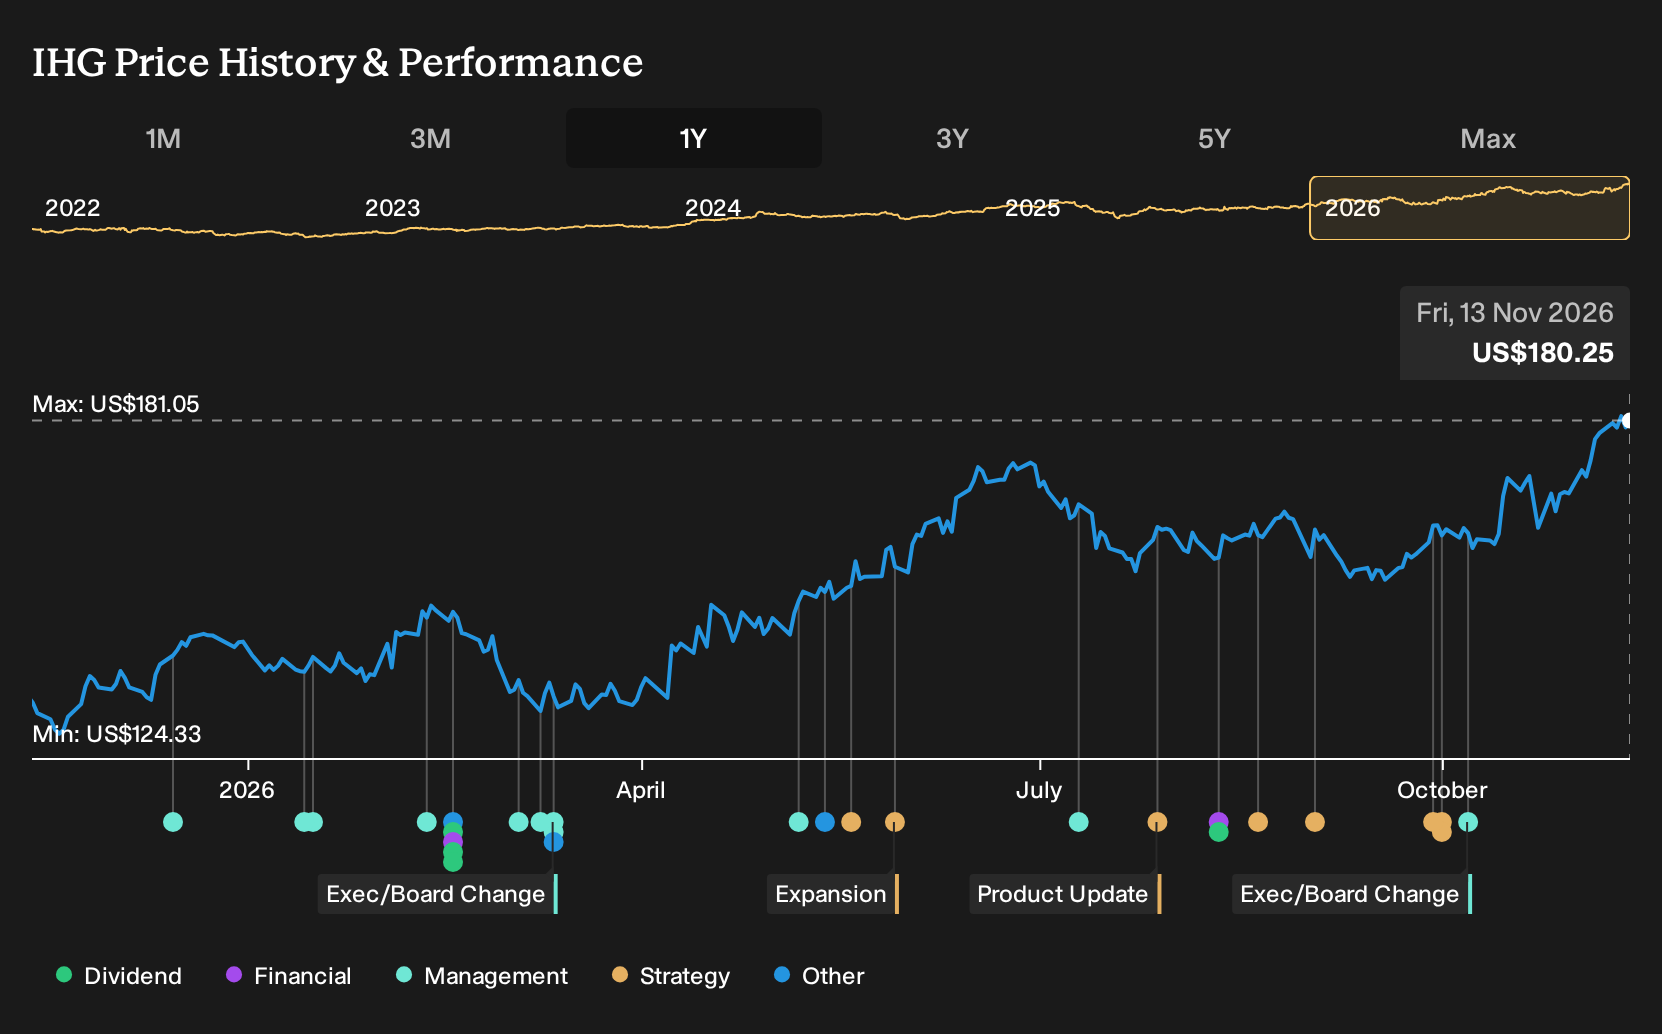
- InterContinental Hotels Group recently bought 96,995 of its ordinary shares for cancellation and grew its luxury footprint with The Hari London and new Vietnam projects.
- The twin moves of targeted share repurchases and a stronger focus on higher fee luxury assets signal management attention on both capital efficiency and premium demand pools.
- How InterContinental Hotels Group’s investment narrative is shaped by its sharper push into luxury hotels in Vietnam remains to be seen.
Scan how InterContinental Hotels Group’s luxury and capital allocation story compares with curated peers by reviewing our 5 high quality undiscovered gems that are quietly building strong fundamentals in premium travel and leisure.
InterContinental Hotels Group Investment Narrative Recap
To own InterContinental Hotels Group, you need to be comfortable with a fee led hotel model that leans on net system growth, broad based RevPAR and high fee margins rather than heavy owned real estate. The analyst consensus narrative on Simply Wall St focuses on this mix, and the latest buyback plus luxury openings do not materially change the near term demand picture.
The more immediate swing factors still look operational. Progress in Greater China and any stabilisation in the Middle East remain key to keeping RevPAR resilient, while higher interest costs and negative equity keep financial risk on the radar. Luxury expansion in Vietnam could help diversify fee pools if execution remains disciplined.
The Vietnam luxury push is the most directly relevant update for that growth story. Four planned projects over 3 to 5 years sit squarely in the Luxury and Lifestyle segment that analysts view as an important fee driver, particularly when paired with branded residences and higher margin ancillary revenue streams.
For you as a shareholder, the question is whether InterContinental Hotels Group can bring these Vietnamese properties onstream in a way that supports system growth and fee margins without adding undue earnings volatility in a single tourism market. Execution quality and owner returns at these assets may influence how credible the broader catalyst set appears.
InterContinental Hotels Group's current earnings of $714.0 million sit against analyst expectations for $1.1 billion in profit and $3.1 billion in revenue by 2029. This implies revenue falling 16.5% per year and an earnings increase of about $386 million over that period.
Uncover why InterContinental Hotels Group's fair value indicates a 7% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One bearish angle you might want to consider focuses on interest costs rather than Vietnam luxury growth. The most pessimistic analysts were already baking in revenue of about US$2.6b and earnings near US$1.0b by 2029, with a lower P/E of 23.5x, before this buyback and new hotel news even landed.
Explore 3 other InterContinental Hotels Group fair value estimates, including one that suggests as much as 25% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your InterContinental Hotels Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for InterContinental Hotels Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate InterContinental Hotels Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond InterContinental Hotels Group?
Once you have formed a view on InterContinental Hotels Group, it can help to widen the lens and compare it with other businesses that fit different risk, income, and quality profiles using the Simply Wall St Screener.
- If you want a wider margin of safety and stronger fundamentals, start with a 14 high quality undervalued stocks that combine earnings strength with solid balance sheets.
- For readers who care most about income stability, scan a curated set of 4 dividend fortresses that aim to pair higher yields with resilient cash flows.
- If capital preservation and smoother returns matter more than chasing every upswing, filter for 5 resilient stocks with low risk scores that score well on financial health and risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com