
Should Stronger Earnings Require Action From STERIS (STE) Investors?
- STERIS plc reported second quarter 2026 sales of US$1,588.6 million and net income of US$213.7 million, with six-month sales of US$3,081.3 million and net income of US$413.8 million, and reiterated its fiscal 2027 consolidated revenue growth outlook of 7% to 8%.
- The fresh earnings detail shows STERIS generating higher basic and diluted EPS from continuing operations over both the quarter and first half, which gives investors more concrete numbers to weigh against earlier expectations about recurring chemistries, services and capital investment returns.
- We will now look at how STERIS's stronger recent earnings and maintained 7% to 8% revenue growth guidance affect that investment narrative.
Scan how STERIS finances its growth compared with a curated peer set by reviewing list of solid balance sheet and fundamentals (24 results) across healthcare and adjacent sectors.
STERIS Investment Narrative Recap
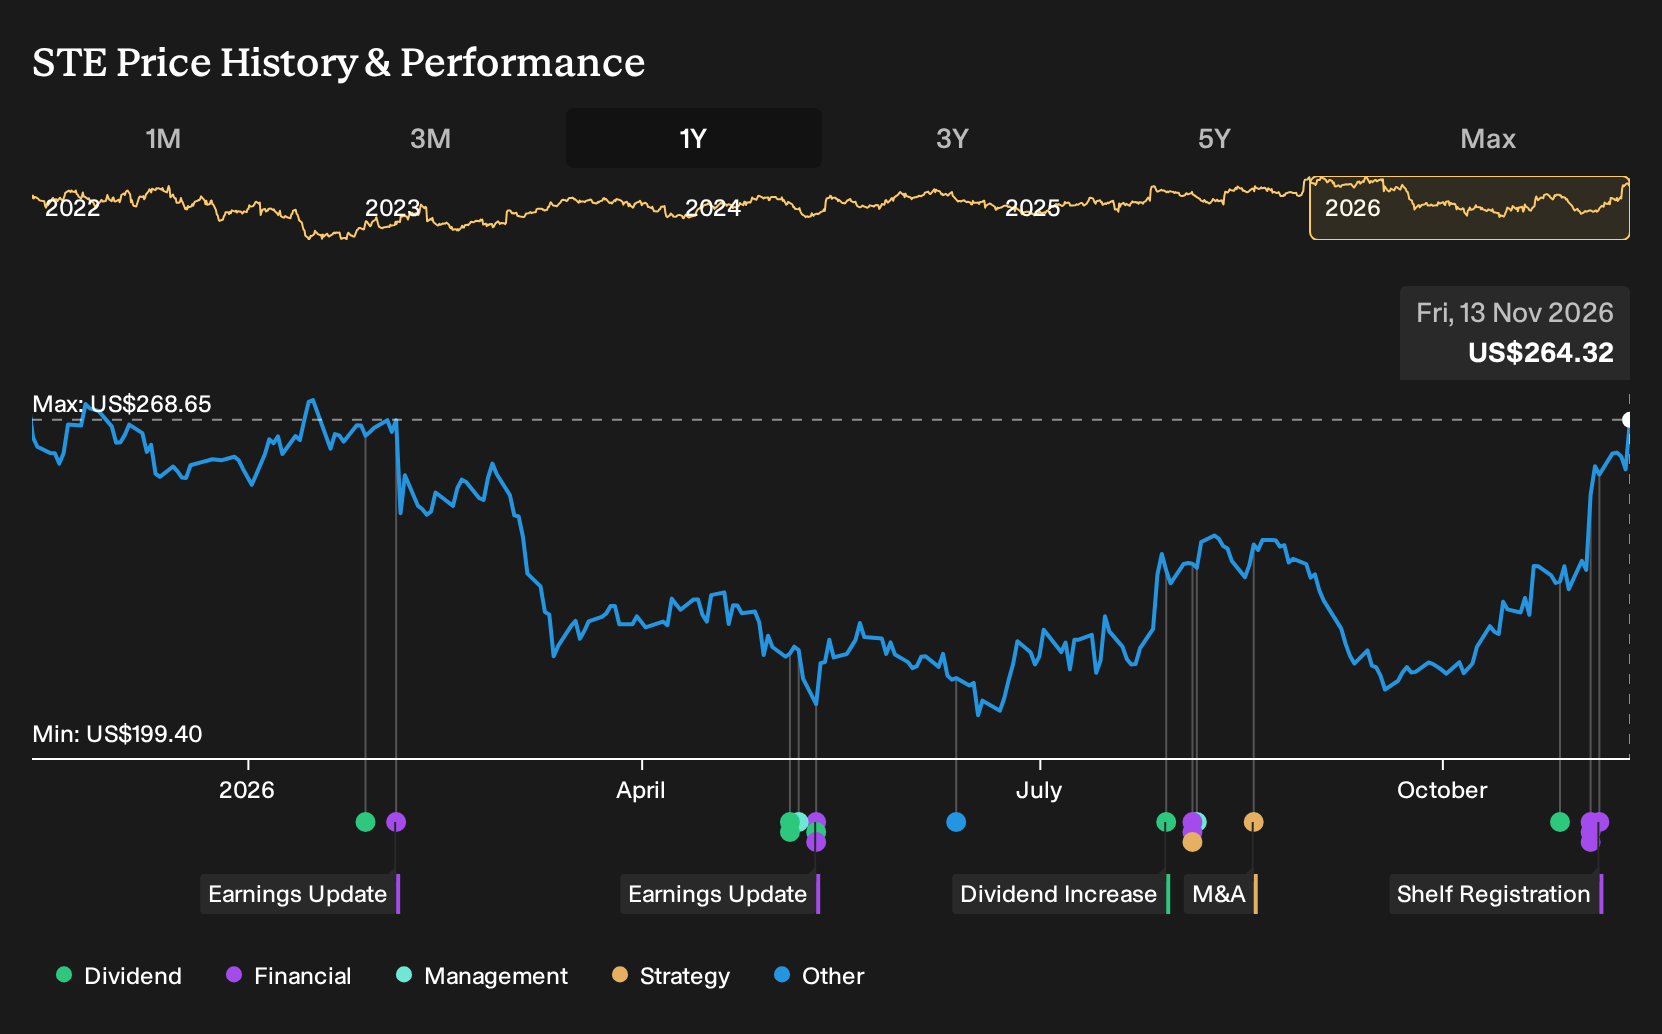
To own STERIS, you need to be comfortable with a healthcare equipment and services business that leans heavily on recurring chemistries and sterilization services, while funding large projects like the North Carolina chemistries build out. The recent earnings update aligns with this picture, and the new shelf registration and credit facilities do not materially alter the near term operating story.
The short term swing factor still looks like execution on capex projects and the Xodus Medical acquisition, which ties into integration risk and return on invested capital. The biggest risk remains margin pressure if tariffs, restructuring charges and higher interest costs from new debt outpace pricing and efficiency gains.
The most relevant fresh disclosure for this setup is the new US$1,600 million revolving credit facility with up to US$800 million of potential expansion plus the US$500 million delayed draw term loan linked to the Xodus Medical deal. This sits alongside the omnibus shelf that covers ordinary shares, preferreds, debt, warrants and units.
For you as a shareholder, that financing toolkit matters because the analyst consensus Narrative on Simply Wall St builds on large chemistry and sterility projects as key catalysts. The new facilities and shelf registration give STERIS room to fund acquisitions and capex, but they also raise the stakes on leverage limits, interest coverage and delivering the returns needed to justify extra capital.
Analysts are currently modeling STERIS to generate about US$7.6b in revenue and US$1.1b in earnings by 2029. This implies roughly 7.0% yearly revenue growth and an earnings increase of about US$273.1m from the current US$826.9m level.
Uncover why STERIS' fair value appears to be generally in line with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$205 and US$271, which already shows how far views on STERIS can stretch. Some members focus on the new shelf registration and expanded credit lines as future growth fuel, while others concentrate on tariff costs and project execution risk. Expect opinions to differ widely and use that spread to test your own view against multiple alternative takes.
Explore another STERIS fair value estimate, including one that suggests it could be worth as much as $270.71.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your STERIS research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for STERIS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STERIS' overall financial health at a glance.
Looking for more STERIS style investment ideas?
If STERIS has sharpened your thinking on quality, balance sheets and long term earnings power, it can help to line that view up against other listed businesses using the Simply Wall St Screener.
- For investors who prize financial strength and room to self fund growth, start with a list of solid balance sheet and fundamentals (24 results) that can handle shocks without relying heavily on new capital.
- If your focus is on finding potential mispricings, compare STERIS with a 34 high quality undervalued stocks that pair sound fundamentals with prices that screens flag as attractive.
- Income focused readers who want cash returns alongside resilience can scan a 6 dividend fortresses that aim to combine higher yields with balance sheets that support ongoing payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com