
3 Australian Growth Stocks With Revenue Growth Over 21%
Warren Buffett has been warning that richly priced markets can feel more like a casino rather than a place to build wealth, and that hits close to home for Australian investors sizing up growth stories today. When broad indices look expensive, a more compelling hunting ground is select businesses where analyst forecasts and management guidance both point in the same direction. This article highlights three such high conviction Australian stocks that regulators and research teams are watching closely.
The stocks covered below are only a small sample of the idea, and the full screen surfaced 21 more Australian businesses with similarly punchy growth stories and aligned analyst and management expectations that are not covered in this article. To go wider and identify your own highest conviction setups, head straight into the High Growth High Conviction screener.
Emerald Resources (ASX:EMR)
Overview: Emerald Resources is a Perth based gold producer focused on its 100% owned Okvau Gold Project in Cambodia as its primary growth engine.
Operations: Emerald Resources generates about A$601 million from mine operations and A$11 million from other activities, with roughly A$609 million earned in Cambodia.
Market Cap: A$4.58b
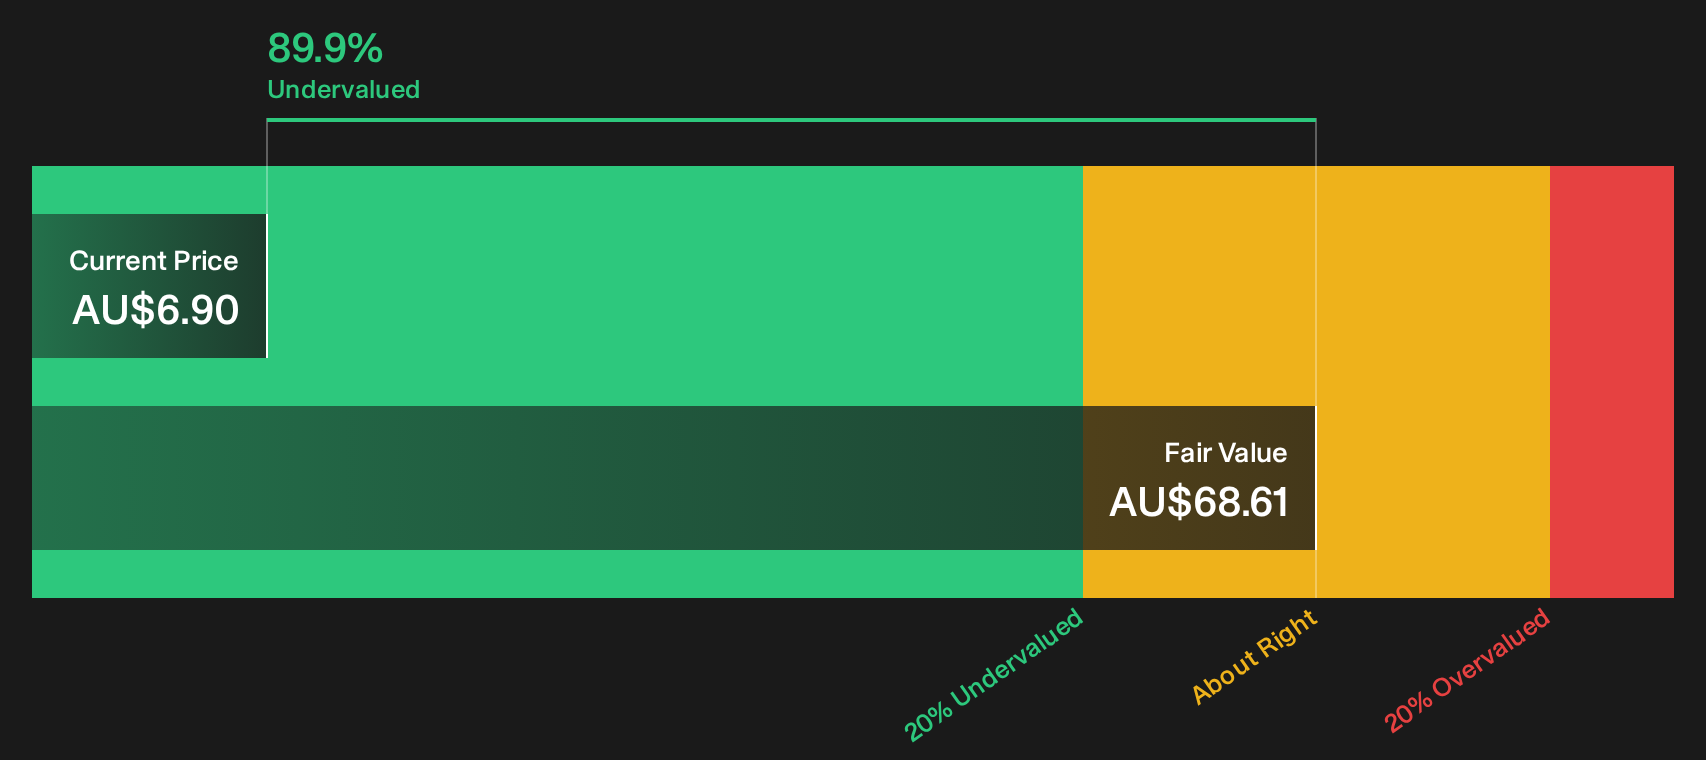
Emerald Resources is closely aligned with the High Growth High Conviction idea, with forecast earnings growth of 35.79% a year and a P/E of 17.6x compared with peers at 23.3x. This is described as being supported by strong Okvau production, high profit margins and a share price that is presented as sitting well below modelled future cash flows, depending on how one unseen funding pressure plays out.
That funding question is exactly what the DCF valuation analysis for Emerald Resources unpacks for Emerald Resources, so you can see how those Okvau cash flows compare with expectations.
Mesoblast (ASX:MSB)
Overview: Mesoblast is a Melbourne based regenerative medicine company developing mesenchymal cell therapies like Ryoncil and Remestemcel L for severe inflammatory and cardiac conditions.
Operations: Mesoblast generates about $120 million from developing and commercializing its allogeneic cellular medicines platform built around mesenchymal lineage therapies.
Market Cap: A$2.51b
For the High Growth High Conviction theme, Mesoblast matters because its mesenchymal cell platform gives the bullish analyst Narrative on Simply Wall St a way to link pipeline progress, product launches and clinical milestones into a single growth story.
"The planned “Generation 2” manufacturing process that adds a proprietary recombinant growth-factor supplement, together with automation and US onshoring of production, points to a step change in cell yields and cost of goods. This could widen gross margins as higher volume indications come through."
The real test for Mesoblast now is how one unresolved funding and execution pressure shapes the timing of that potential earnings shift.
That inflection point is exactly what the full narrative for Mesoblast unpacks, mapping how funding, approvals and execution could accelerate or stall Mesoblast’s mesenchymal cell ambitions.

Pinnacle Investment Management Group (ASX:PNI)
Overview: Pinnacle Investment Management Group runs a multi affiliate funds platform that provides distribution and infrastructure to scale high conviction investment managers.
Operations: Pinnacle Investment Management Group generates about A$110 million from funds management operations, with all reported revenue currently sourced in Australia.
Market Cap: A$3.64b
Pinnacle Investment Management Group matters for the High Growth High Conviction theme because its platform helps fast growing boutique managers turn performance into scalable inflows. The bullish analyst Narrative on Simply Wall St focuses on the link between fund flows, affiliates and earnings momentum.
"Life Cycle Investment Partners has moved from launch to A$42.4b of funds under management in less than 2.5 years, and management has flagged a shift toward higher fee retail channels and higher yielding strategies, which could change the fee mix and support higher revenue margin and earnings contribution for Pinnacle Investment Management Group over time."
The key question for Pinnacle now is whether a shift in how affiliates charge and grow can reset group level profitability.
If that reset is what you are weighing up, go straight to the full narrative for Pinnacle Investment Management Group to see how fee mix, flows and earnings power could be accelerating.

Seeking Fresh Alternatives Before They Fly
Markets move fast, and the next breakout list rarely stays quiet for long. Track fresh momentum shifts that are under the radar for now, before the crowd catches up. Consider acting while conditions still appear favorable to you.
- Target rock solid balance sheets and disciplined capital allocation by scanning the curated list of solid balance sheet and fundamentals (12 results) before valuations potentially adjust.
- Explore structural demand for critical metals by combing through a hand picked 17 top copper producer stocks that could benefit if long term supply tightness develops.
- Look for potential future cash engines in essential infrastructure by reviewing a focused 44 power grid technology and infrastructure stocks while these businesses may still be less widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com