
Coinbase (COIN) Stock Looks Overvalued Based On Its Sales
Coinbase Global has seen its share price fall 61.6% over the past 5 years, even as it secures new regulatory approvals and launches fresh products. With the stock now around US$127.65 and the business still closely tied to crypto activity, the open question is whether today's valuation is adequately backed by its sales.
- The 61.6% decline in Coinbase's 5 year return puts the focus squarely on how much reliable revenue investors believe this business can generate through a full crypto cycle.
- Final approval for a national trust bank charter and the expansion of custody and stablecoin related services can influence how investors think about the durability and mix of Coinbase's future sales.
- Your read on Coinbase Global is one view; the desks covering it have another. See what analysts think Coinbase Global's shares could be worth.
The issue now is whether the current share price asks too much or too little of Coinbase's sales base and its potential to grow over time.
For a broader read on crypto linked equities, it can help to compare Coinbase Global with other 23 cryptocurrency and blockchain stocks
Has Coinbase Global Run Too Far on Sales?
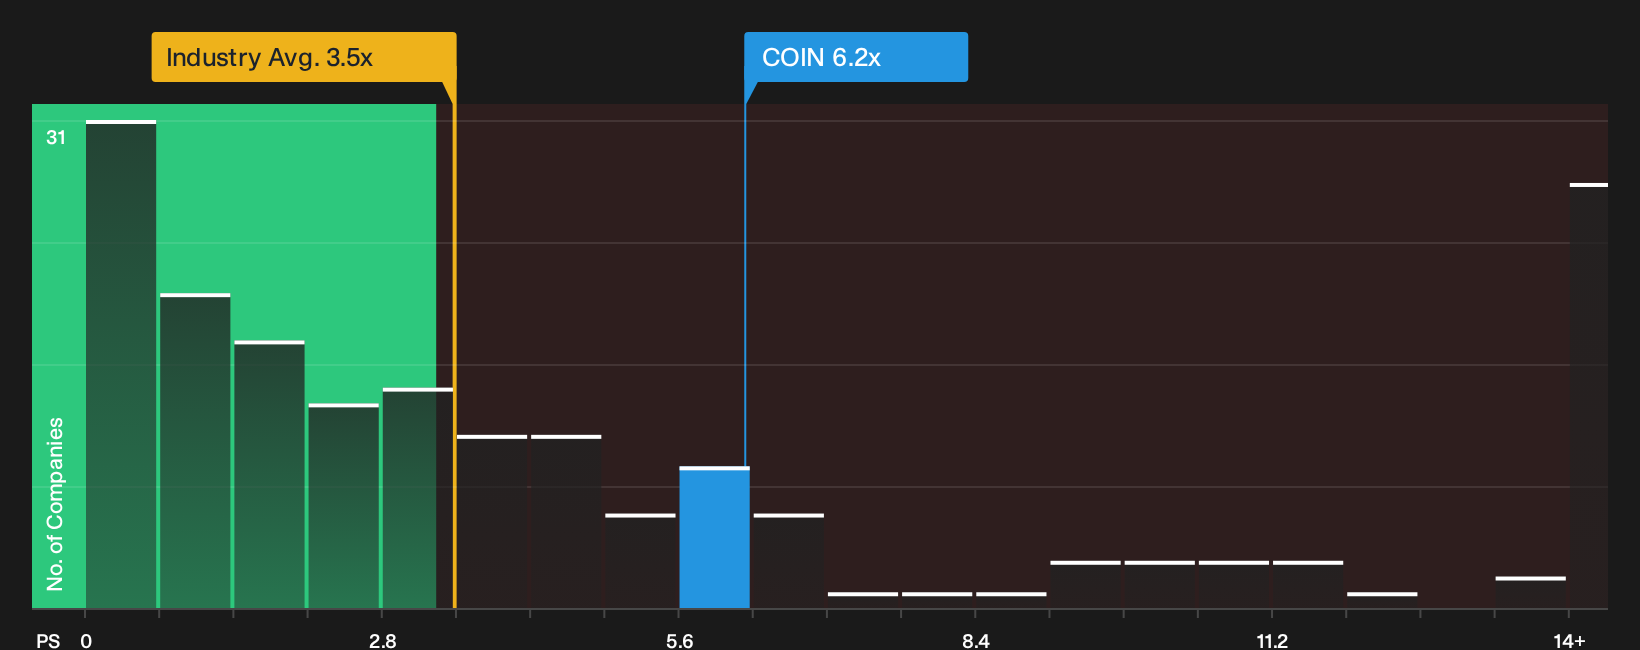
P/S is a useful lens for Coinbase Global because investors focus heavily on its trading and fee revenues rather than steady earnings. On this measure, the stock changes hands at about 6.2x sales, compared with roughly 3.5x for the wider Capital Markets industry and around 10.9x for closer crypto linked peers. That leaves Coinbase trading at a premium to the broader sector but on a lower multiple than its more direct comparators.
The fair P/S level suggested by the tailored model, which factors in Coinbase's margins, risk profile, business mix and scale, sits below where the market currently prices the shares. As a result, the stock screens as overvalued on this framework. Despite the fresh OCC approval for a national trust bank charter strengthening the regulatory footing of Coinbase's custody arm, the present sales multiple already builds in a richer set of expectations than that model implies. Explore the numbers behind Coinbase Global's P/S valuation.
The Coinbase Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Coinbase Global leaves off. Narratives on the Community page spell out which assumptions on future growth, margins and earnings would need to hold for the shares to be worth materially more or materially less than today. Each one treats fair value as a thesis about Coinbase Global's business that you can track over time rather than a one day snapshot.
Views on Coinbase Global split between those who see a stronger platform taking shape and those who think the customer base is not really broadening.
Bull case: 35% undervalued
According to the analyst consensus Narrative on Simply Wall St, the upbeat view leans heavily on recurring revenue and scale effects at Coinbase Global.
"Growth in subscription and services revenue to about US$2.5b on an annualized basis, helped by products such as Coinbase One with more than 1 million paying subscribers..."
Discover why this Narrative puts Coinbase Global at 35% undervalued.
Bear case: roughly fairly valued
CentryResearch, a Simply Wall St Community investor who wrote the Narrative, argues Coinbase Global may be stretching products faster than it is expanding its audience.
"We believe Coinbase may be diversifying its products faster than it is diversifying its customers..."
Explore why this Narrative puts Coinbase Global at roughly fairly valued.
Before you weigh Coinbase Global purely on price and sales
There is one more piece to check before leaning on any valuation view for Coinbase Global, since Simply Wall St's broader review has flagged specific concerns that readers may want to examine in detail. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com