
How Investors Are Reacting To EPR Properties (EPR) $500 Million Convertible Notes
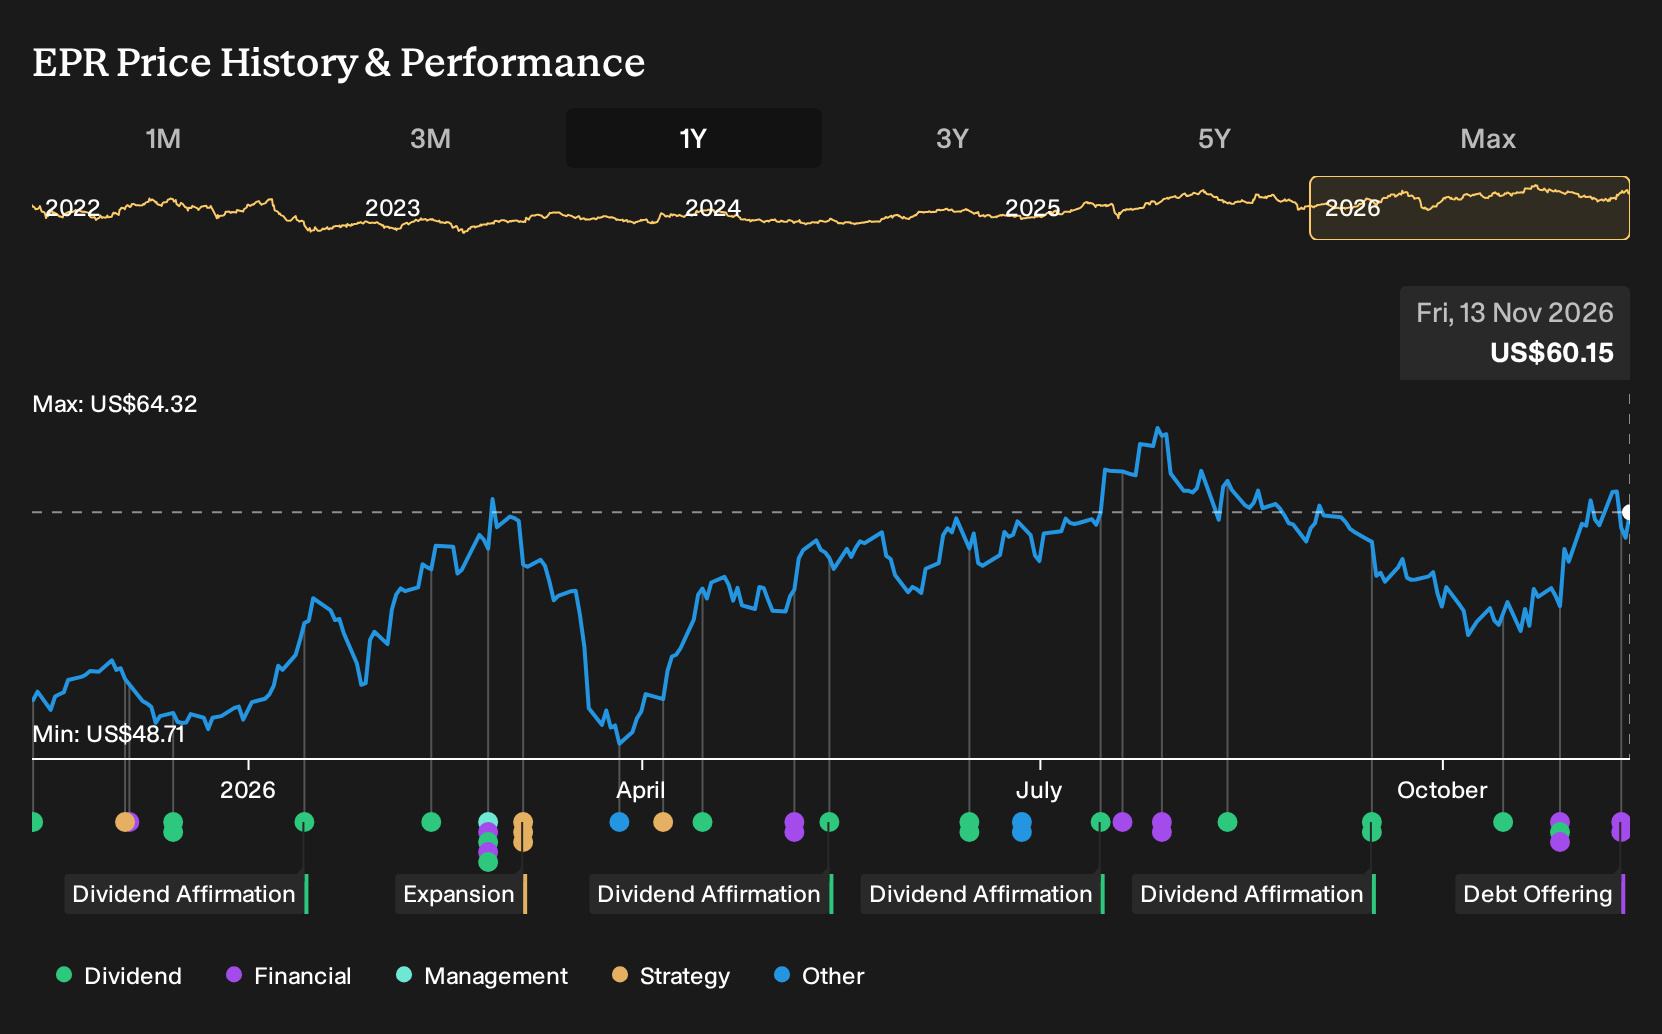
- EPR Properties has completed a US$500 million senior unsecured convertible bond offering, issuing 4.5% notes priced at 100% and maturing on February 15, 2032 under Rule 144A.
- The new 2032 convertible notes give EPR Properties another funding source that could affect how it allocates capital to experiential real estate over time.
- This article examines how EPR Properties' US$500 million convertible notes could influence the current experiential real estate investment narrative.
Compare EPR Properties' new convertible funding move with other real estate and income-focused opportunities by scanning a hand-picked list of solid balance sheet and fundamentals (24 results).
EPR Properties Investment Narrative Recap
To own EPR Properties, you need to be comfortable with an experiential real estate story that still leans on theaters and other discretionary venues while aiming to shift more toward attractions, fitness, wellness and similar assets. The analyst consensus Narrative on Simply Wall St highlights this capital recycling as a key driver, with balance sheet flexibility and largely fixed rate debt supporting ongoing investment plans.
The new US$500 million 4.5% convertible notes do not radically change that thesis on their own. They do, however, add another layer of funding that can affect how quickly EPR Properties invests and how it manages interest costs. This matters because interest coverage and exposure to discretionary tenants are already important short term risks.
The most relevant development here is the completion of those senior unsecured convertible notes due February 15, 2032, issued at 100% with a fixed 4.5% coupon under Rule 144A. For you as a shareholder, the mechanics are straightforward. EPR Properties now has an additional US$500 million of callable, convertible funding that sits as senior unsecured debt.
That structure matters for both catalysts and risk. Extra capital can support the experiential investment pipeline flagged in the analyst consensus Narrative on Simply Wall St, including recycling away from theaters. It also increases the importance of how EPR Properties balances leverage, interest coverage and potential future equity dilution if the notes convert. Execution on those points will shape how the story evolves from here.
What The Forecasts Assume For EPR Properties
EPR Properties' narrative projects US$902.3 million revenue and US$277.7 million earnings by 2029. That framework uses 6.9% yearly revenue growth and implies an earnings increase of about US$38.6 million from US$239.1 million today.
Uncover how EPR Properties' fair value indicates an 8% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$64.68 to US$127.04 per share, so retail opinions already cover almost a 2x gap. Before the new US$500 million EPR Properties convertible bond, many members focused on experiential spending trends and theater risk. Use those differing takes to stress test your own thesis.
Explore another EPR Properties fair value estimate, including one that suggests it could be worth just $64.68.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EPR Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EPR Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EPR Properties' overall financial health at a glance.
Looking for more investment ideas beyond EPR Properties?
Once you have a view on EPR Properties and its new convertible notes, it can help to widen the lens and compare similar income or total return opportunities using the Simply Wall St Screener.
- For potential value opportunities with strong fundamentals, scan a curated set of 34 high quality undervalued stocks that may merit a spot on your watchlist.
- If resilience matters most to you, focus on a 30 resilient stocks with low risk scores that scores well on financial strength and volatility metrics.
- For investors hunting for less crowded setups, review a 19 high quality undiscovered gems that combine solid financial profiles with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com