
Missed Veolia Environnement's Rally? Here Is What Holders Saw
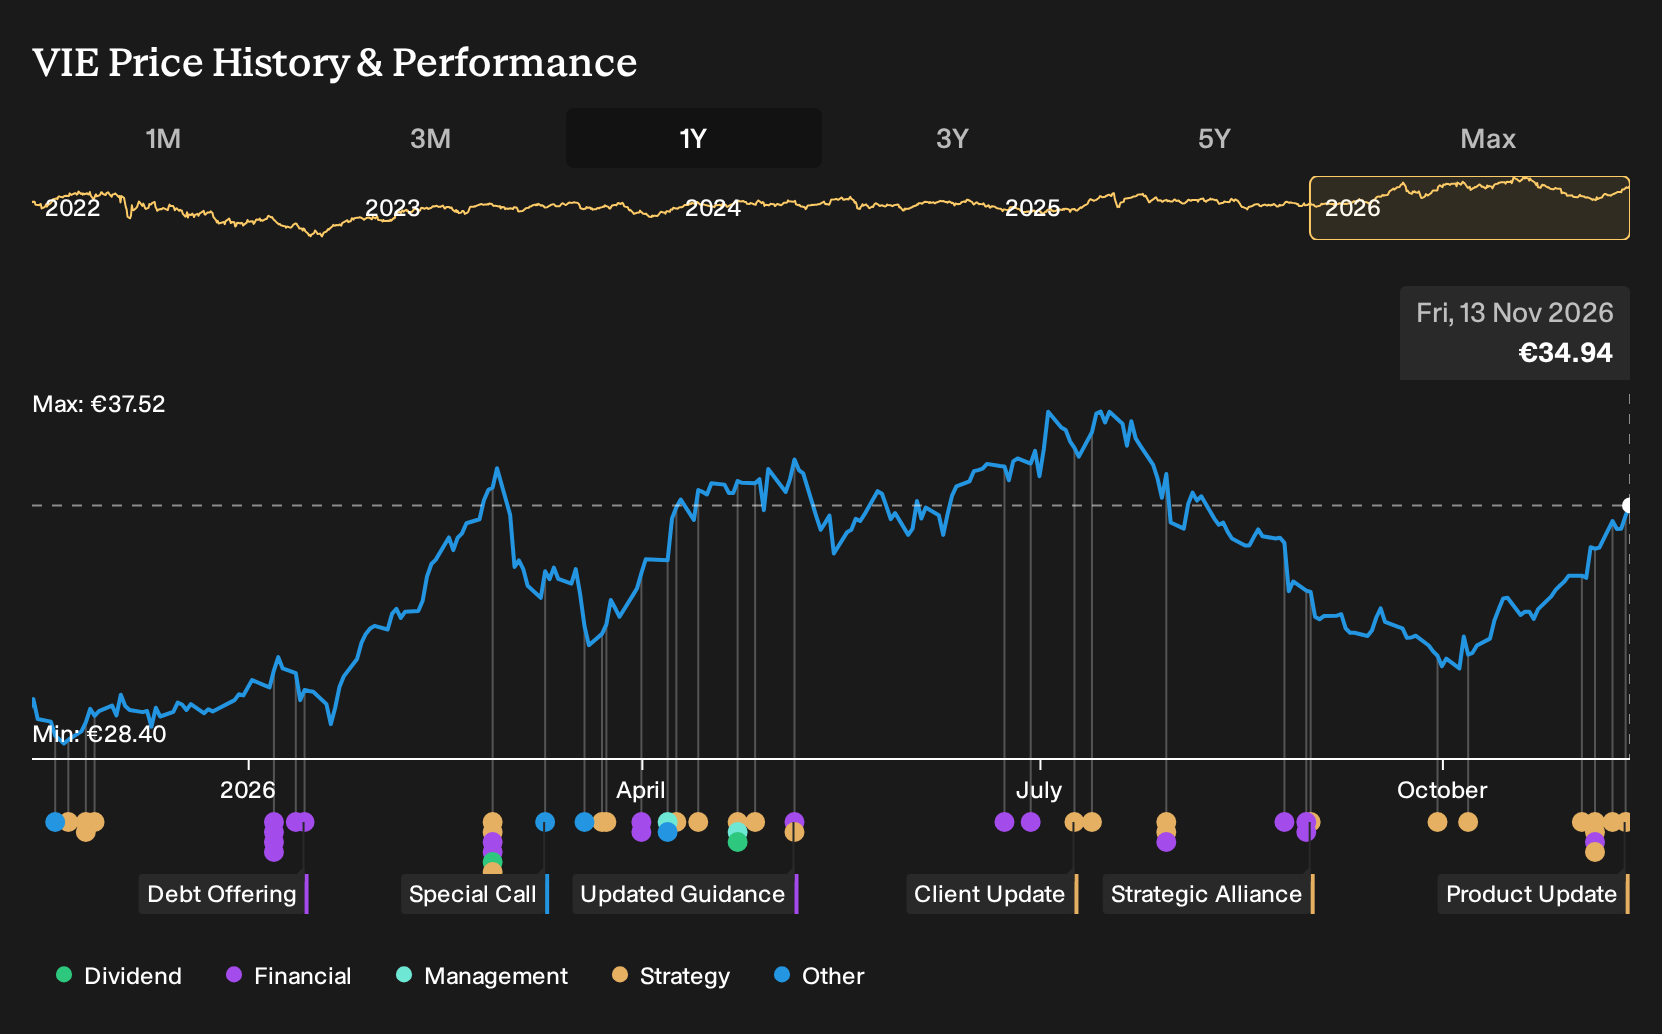
If you had bought Veolia Environnement on 13 November 2025 and simply sat tight, the result would have been hard to ignore. Investors who held Veolia Environnement over the past year are up 25.4%, including dividends. That outcome now sits against the earlier split between bullish research focused on water technologies and hazardous waste, and bearish work worrying about decentralised energy and debt. Which side of that argument would have felt more convincing at the time of the decision?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Veolia Environnement is not the only name tied to this theme. Zero in on 44 power grid technology and infrastructure stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Veolia Environnement
The shares cost €29.62 at the start of the period, and Veolia Environnement sat between two very different but plausible stories about its future.
The bullish Narrative pointed to a Fair Value of €35.23, built on the idea that tighter environmental rules and demand for water technologies and hazardous waste treatment could support recurring earnings, with M&A synergies feeding through to margins and cash generation.
The bearish view set Fair Value at €25.3, focused on the risk that decentralized energy and local recycling might eat into big infrastructure contracts, while a net financial debt load near €21b and leverage around 3x EBITDA limited flexibility.
What The Results Changed For Veolia Environnement
The strongest signal came from Veolia Environnement reporting H1 2026 revenue of €22,193m and net income of €671m, both higher than H1 2025, alongside Q3 updates that highlighted contract wins in Spain, the Middle East, Latin America and the US hazardous waste market. That pattern broadly supported the optimistic case that regulation driven water and waste activities and M&A execution could support earnings and cash generation, although the evidence did not directly address the debt concerns.
The practical lesson is about focus. When a thesis hinges on recurring earnings from long contracts and acquisition synergies, track reported revenue, net income and disclosed integration milestones against the original story for any infrastructure stock you study.
What Veolia Environnement’s Price Already Assumes
Veolia Environnement now trades at €34.94, after a 25.4% gain over the past year. The bearish analyst Narrative on Simply Wall St sees Fair Value as below that level, reflecting a view that recent operational strength is already largely accounted for in the market price.
The same Narrative argues that the key question is how reliably Veolia Environnement can turn its mix of water, hazardous waste, bioenergy and digital tools into durable profitability. A buyer today would need to judge whether margin gains can keep offsetting input cost shocks, project delays and the extra leverage tied to acquisitions.
"The current valuation implies the market is cautious about Veolia Environnement being able to translate its record 16% EBITDA margin, strong H1 2026 earnings, expanded booster activities and long term PFAS and data center pipelines into durable value per share."
One Narrative disagrees with today's price. → See where this Narrative says Veolia Environnement should trade
Another Way To Read Veolia
Veolia highlights how regulation heavy infrastructure can influence long term cash flows.
Nearby, a different business leans on a similar structural force.
Large power buyers want carbon free electricity available at all hours under stable contracts.
One specialist generator serves that demand, using long dated clean power deals to smooth earnings.
Its outlook depends on nuclear policy, shifting grid rules and intricate plant upgrades, leaving its future role in dependable low carbon energy still wide open.
That argument has a Narrative and a number behind it. → See the company one Narrative values 22% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com