
Doximity (DOCS), What Is Behind The Fresh Attention?
Doximity (DOCS) is back in focus after expanding its collaboration with NewYork-Presbyterian, Columbia University and Weill Cornell Medicine, rolling out AI tools for clinical decision support and medical scribing across their Epic-based workflows.
Against that product backdrop, Doximity’s shares have climbed recently, with a 90 day share price return of 35.97% and a 30 day gain of 7.65%. However, the year to date share price return is down 22.98% and the 1 year total shareholder return has declined 32.81%, leaving longer term performance mixed despite stronger short term momentum.
Scan for other healthcare AI stories with breakout potential by comparing Doximity’s move with our curated list of 36 healthcare AI stocks in the same space.
Doximity has just put up a sharp short term rebound on the back of its healthcare AI story, while longer term holders are still nursing double digit declines. Does that setup reward patience or a fresh entry now?
Most Popular Narrative: 1.1% Undervalued
Doximity’s last close at $33.34 sits just below a fair value of $33.70 implied in the most followed narrative, leaving only a slim valuation gap for investors to interpret.
According to Dc12, an investor in the Simply Wall St Community who wrote the narrative, the real asset here is the depth of the physician audience and how that might be translated into business value over time.
What I like about Doximity is that there really is a very high viewership / user base of active practicing Physicians in the US and that is not invaluable and definitely could be monetized perhaps more efficiently. I also think that Doximity offers a lot of interesting tools for Physicians a lot of which you’re free and really marketed towards I think Physicians who are more in private practice.
See why 11 investors see Doximity as 1% undervalued.
Result: Fair Value of $33.70 (UNDERVALUED)
Still, the Doximity story could be knocked off course if physician engagement with its tools weakens or if rival healthcare platforms pressure pricing and ad budgets.
Find out about the key risks to this Doximity narrative.
Another View: What Doximity’s P/E Is Telling You
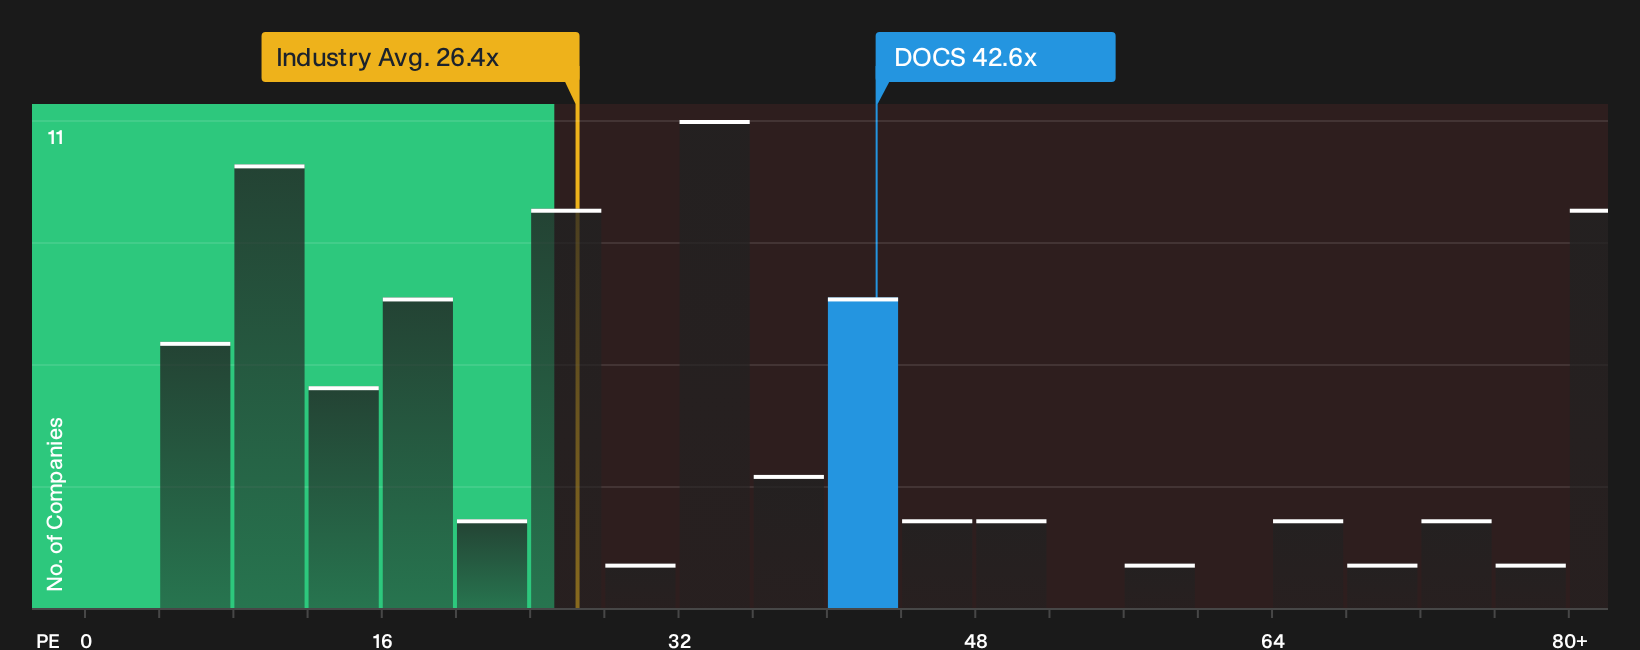
The first narrative frames Doximity as modestly undervalued around $33, yet the P/E picture is less forgiving. At 42.6x earnings versus a fair ratio of 30.4x, the stock screens expensive, even if it trades below peer levels of 59.5x. Is that premium a cushion or a glass ceiling for returns?
Investors who lean on earnings multiples rather than cash flow models may want to see how this richer P/E and fair ratio gap stack up in a fuller breakdown before deciding how much valuation risk feels acceptable here. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals rarely stay mixed for long, so treat this as a moment to stress test Doximity against your own expectations and risk tolerance. If you want the full context on both the concerns and the upside potential, take a closer look at the 2 key rewards and 2 important warning signs.
Looking for more Doximity-sized investment ideas?
If Doximity has you thinking about what else might be hiding in plain sight, use this moment to scan fresh ideas before the next move leaves you watching.
- Target resilient balance sheets and steadier fundamentals by reviewing our list of solid balance sheet and fundamentals (24 results) tailored to financially stronger companies.
- Hunt for potential value opportunities by checking the 34 high quality undervalued stocks that filters for quality businesses trading below fair value estimates.
- Prioritize stability-focused opportunities by scanning the 30 resilient stocks with low risk scores that concentrates on companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com