
Is Clean Harbors (CLH) Undervalued Or Is Its Premium P/E Still Too Rich?
Clean Harbors (CLH) drew attention after a session in which the share price closed 1.32% higher at US$293.84, while trading volume came in lighter than usual for the stock.
Recent trading puts Clean Harbors in an interesting spot. The share price is up 3.42% over the past week but down 8.20% over the past month and 9.89% over the past quarter, while year to date the share price return is 20.69% and the 1-year total shareholder return of 42.73% points to momentum that has been building over a longer horizon.
Scan beyond Clean Harbors to find other environmental and industrial players showing strong momentum and fundamentals across our hand picked list of solid balance sheet and fundamentals (24 results)
Clean Harbors now trades at a clear discount to both analyst targets and one estimate of intrinsic value after that recent pullback. Is this simply caution catching up with a hot stock, or has the market gone too far?
Most Popular Narrative: 16% Undervalued
The narrative fair value of $350.00 sits well above Clean Harbors' last close at $293.81, which puts the current pullback in a very different light according to prajeeshprathap, a Simply Wall St Community investor who wrote the narrative.
The deeper investment thesis is:
Modern society keeps producing hazardous waste, and somebody has to safely collect it, transport it, treat it and dispose of it. Clean Harbors owns one of the most difficult-to-replicate infrastructure networks required to do that.
See why 3 investors see Clean Harbors as 16% undervalued.
Result: Fair Value of $350 (UNDERVALUED)
Still, the Clean Harbors narrative can break if regulatory rules ease meaningfully, or if hazardous waste volumes soften for longer than investors expect.
Find out about the key risks to this Clean Harbors narrative.
Another View on Clean Harbors’ Valuation
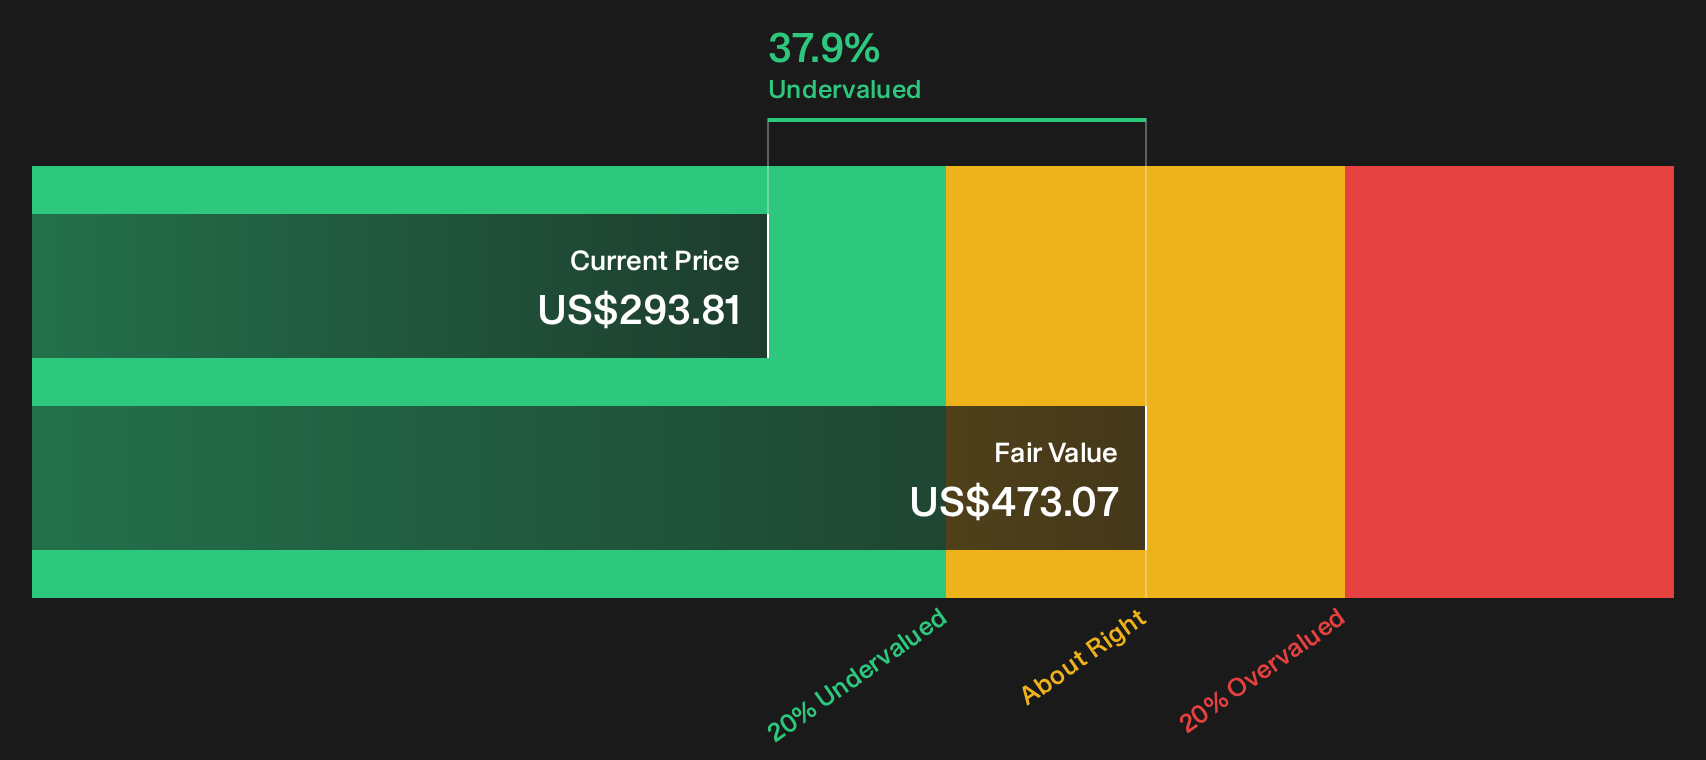
The earlier narrative fair value framed Clean Harbors as 16% undervalued at $350. On earnings multiples, the story looks less generous. The stock trades on a P/E of 29.3x, compared with a fair ratio of 21.6x and a US Commercial Services average of 19x. That leaves investors weighing a richer current multiple against a narrative of long term compounding.
For readers who want to see how this earnings based view stacks up against a cash flow lens, our DCF workup sets out a different angle on Clean Harbors’ value profile: Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Clean Harbors' value and risk profile make this a stock you need to assess directly. Then weigh both sides of the story using 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Clean Harbors?
If you only stop with Clean Harbors, you risk missing other setups that fit your style just as well, or even better, across the market.
- Scan for quality at a discount by reviewing companies flagged in our 34 high quality undervalued stocks and see which ones line up with your return expectations.
- Target resilient cash generators by checking the 6 dividend fortresses that combine income potential with proven payout histories.
- Prioritize staying power by focusing on businesses in the 29 resilient stocks with low risk scores that pair sturdier balance sheets with more measured risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com