
Can Regeneron Pharmaceuticals (REGN) Stay Below Fair Value After Trial Wins?
Regeneron Pharmaceuticals has climbed strongly in recent years, and with the stock last closing at US$955.47 the obvious question is whether that price still lines up with what its earnings can support. Between the recent share gains and a string of positive trial updates, investors are increasingly asking if the earnings power of the business is enough to carry the current valuation.
- Over the past 5 years the stock has delivered a 47.8% return, which puts real pressure on the idea that earnings need to do more work to justify where the share price now sits.
- Recent trial results for baloncibart in POTS and CIDEB siRNA in MASLD may support expectations for future earnings, since successful programs can affect pricing power, product mix and the timing of cash inflows if they progress through late stage development.
- Your read on Regeneron Pharmaceuticals is one view; the desks covering it have another. See what analysts think Regeneron Pharmaceuticals's shares could be worth.
The stock's next move may depend on whether Regeneron Pharmaceuticals' current earnings are enough to support a share price near US$955.47.
If you are weighing Regeneron Pharmaceuticals against other earnings driven healthcare opportunities, it can help to compare it with companies in 36 healthcare AI stocks.
Is Regeneron Pharmaceuticals a Bargain on Earnings?
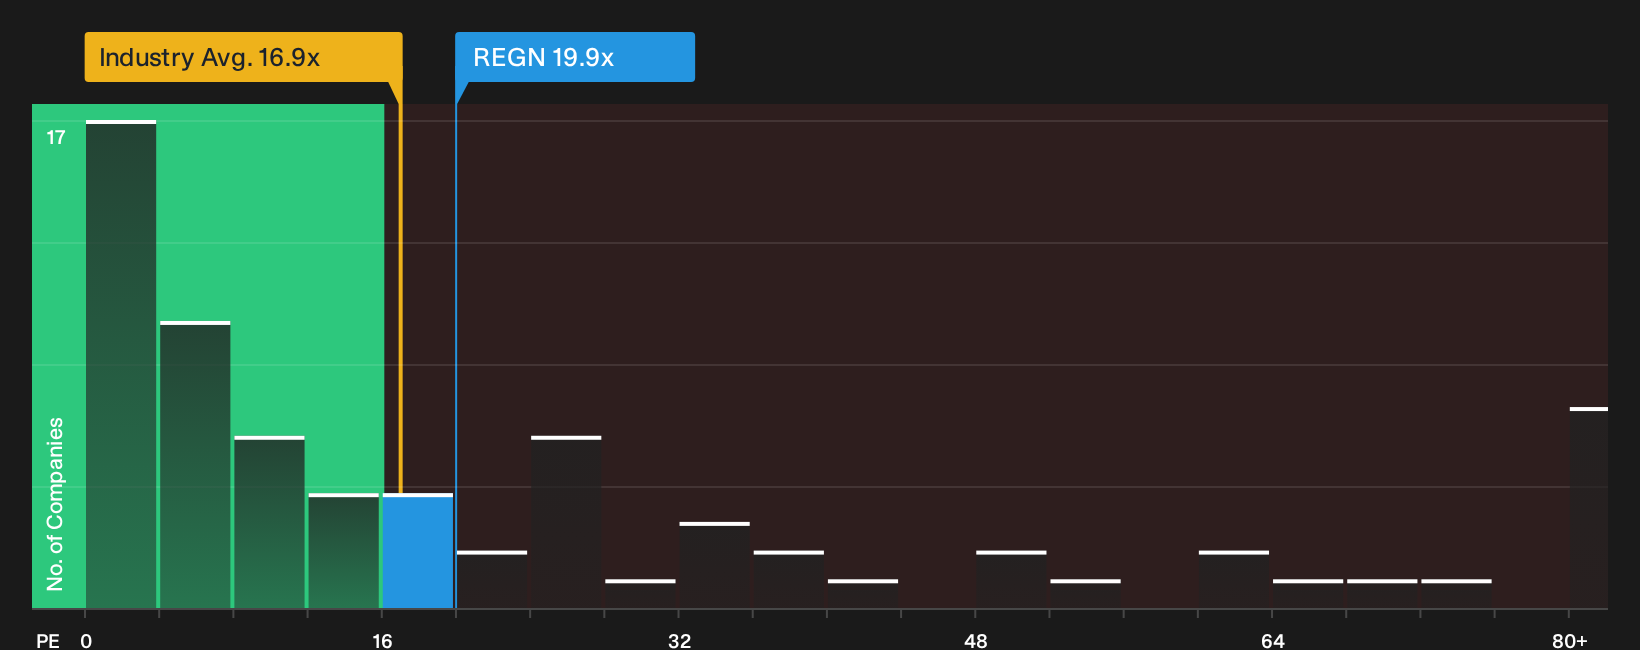
The P/E ratio suits Regeneron Pharmaceuticals because earnings remain a core yardstick for how the market judges large established biotechs. At roughly 19.9x earnings, the stock trades below the broader biotech industry average of about 16.9x but far under the peer group average of around 55.2x, which includes more aggressively valued research heavy developers.
Within this framework, which blends the company’s growth, profitability, scale and risk into a tailored benchmark, Regeneron Pharmaceuticals trades below the multiple implied for it by that fair value model. This points to an undervalued P/E setup rather than a stretched one. Because the latest baloncibart and CIDEB siRNA trial updates are concrete clinical milestones that often command richer pricing in this sector, the current discount to that fair benchmark suggests the recent news has not fully flowed through into the earnings multiple yet. Explore the numbers behind Regeneron Pharmaceuticals's P/E valuation.
The Regeneron Pharmaceuticals Narrative: What Would Justify Today's Price?
Narratives pick up where that valuation puzzle for Regeneron Pharmaceuticals leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to end up worth materially more or materially less than today’s price. All of this is housed on Simply Wall St’s Community page.
Rather than focusing on a single P/E or model output, each narrative lays out the earnings and cash flow assumptions that underpin its view of fair value so you can compare those expectations with Regeneron Pharmaceuticals' actual results as they are reported.
Investors reading Regeneron Pharmaceuticals see the same products and trials, yet one camp thinks the story still has more to give while the other worries expectations already run hot.
Bull case: roughly fairly valued
This view comes from the analyst consensus Narrative on Simply Wall St, which builds on pooled earnings and revenue forecasts.
"Regeneron Pharmaceuticals is still advancing a broad late stage pipeline in areas such as immunology, oncology, genetic medicines, and obesity..."
Discover why this Narrative puts Regeneron Pharmaceuticals at roughly fairly valued.
Bear case: 20% overvalued
This angle is drawn from the bearish analyst Narrative on Simply Wall St, which leans on the most cautious earnings assumptions.
"Bearish analysts expect Regeneron Pharmaceuticals to remain exposed to concentrated product risk as EYLEA faces biosimilar competition and Dupixent growth moderates against tougher comparisons in 2026..."
Explore why this Narrative puts Regeneron Pharmaceuticals at 20% overvalued.
One more angle on Regeneron Pharmaceuticals that could change your view
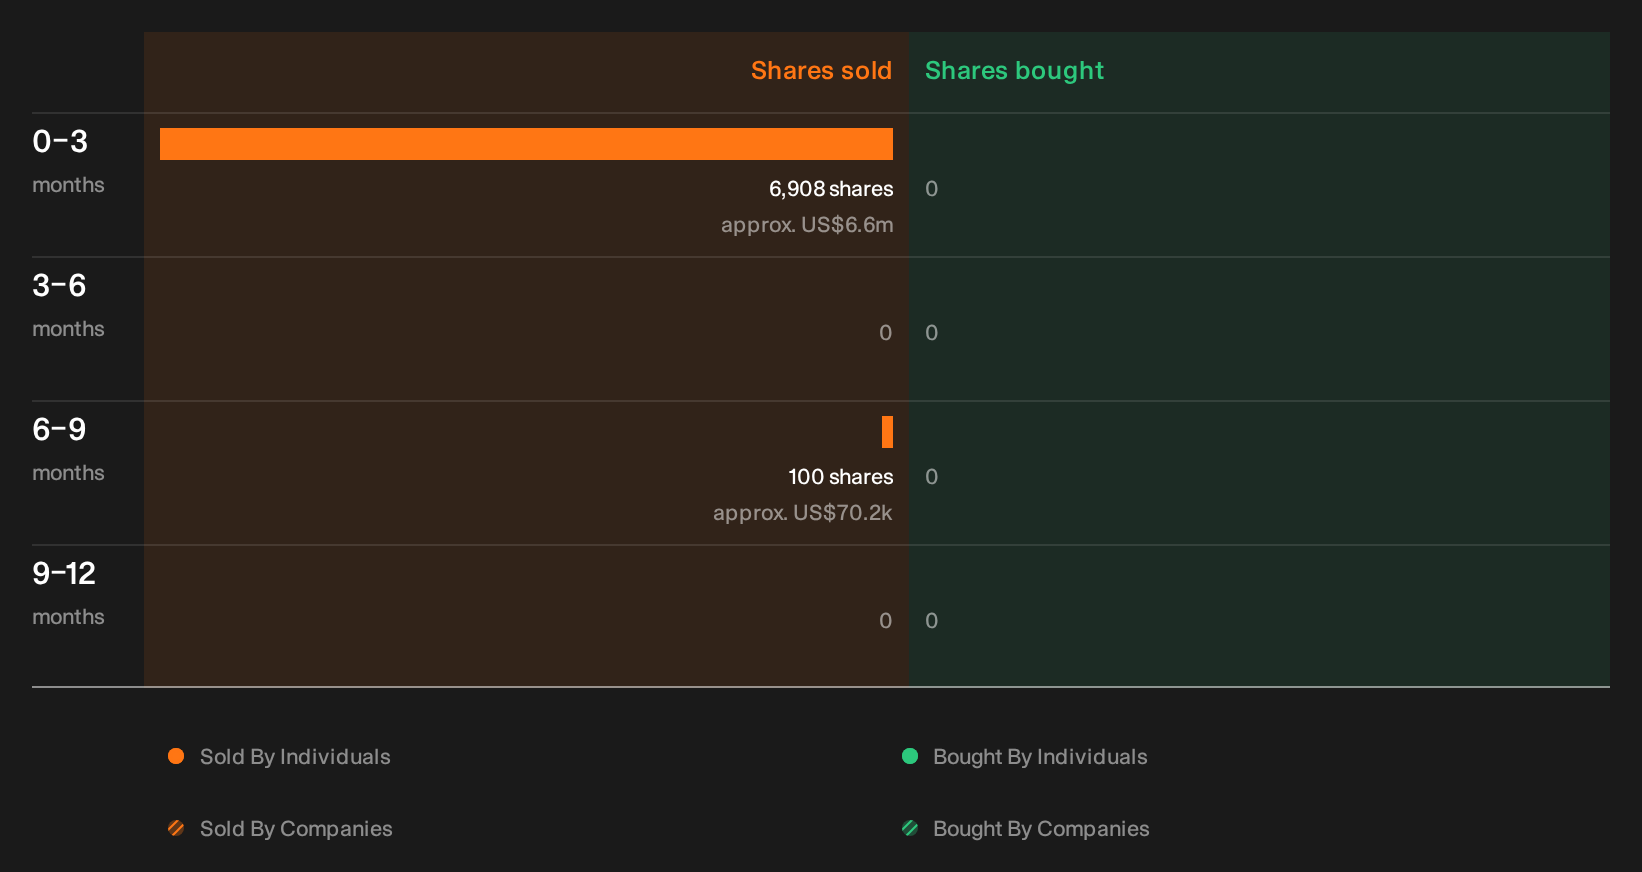
Valuation only tells part of the story, because recent trading by people inside Regeneron Pharmaceuticals can hint at how those closest to the business are acting. See the recent insider selling flagged for Regeneron Pharmaceuticals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com