
What’s Going On With AutoZone (AZO)?
AutoZone (AZO) has drawn fresh attention after its recent share price move, with the stock closing at US$3,259.70 on 9 November 2026. This extended a steady run over the past month.
For context, AutoZone has seen a 7.96% 90 day share price return and a 4.46% 30 day share price return. However, the year-to-date share price return is slightly lower, and the 1 year total shareholder return is down 15.48%, while the 5 year total shareholder return of 75.28% points to much stronger longer-term momentum.
Scan how AutoZone's recent swing compares to other retailers with solid fundamentals by checking the hand picked list of solid balance sheet and fundamentals (24 results) in the same corner of the market.
After that sharp rebound yet weaker one-year record, the issue for AutoZone is simple. Is the meaningful upside still ahead, or did most of it already play out before this latest move?
Most Popular Narrative: 15% Overvalued
AutoZone last traded at $3,259.70, while the leading narrative from the Simply Wall St community assigns a fair value of $2,829.08, implying the stock is pricing in more optimism than that valuation supports according to LunaRodas, a Simply Wall St Community investor who wrote the narrative.
AutoZone closed its fiscal fourth quarter with earnings per share up 15.1% and a store count that crossed 8,000 for the first time. These figures were built substantially on a $96 million tariff refund and a LIFO charge that landed $65 million lighter than the year-ago period. Underneath that headline, domestic DIY sales turned negative, and the SG&A discipline management explicitly promised three months earlier gave way to the fastest per-store expense growth of the year.
See why 2 investors see AutoZone as 15% overvalued.
Result: Fair Value of $2,829.08 (OVERVALUED)
Still, that overvaluation narrative could be challenged if AutoZone continues to grow revenue and net income at recent annual rates, or if management reins in SG&A expense growth.
Find out about the key risks to this AutoZone narrative.
Another View on AutoZone’s Valuation
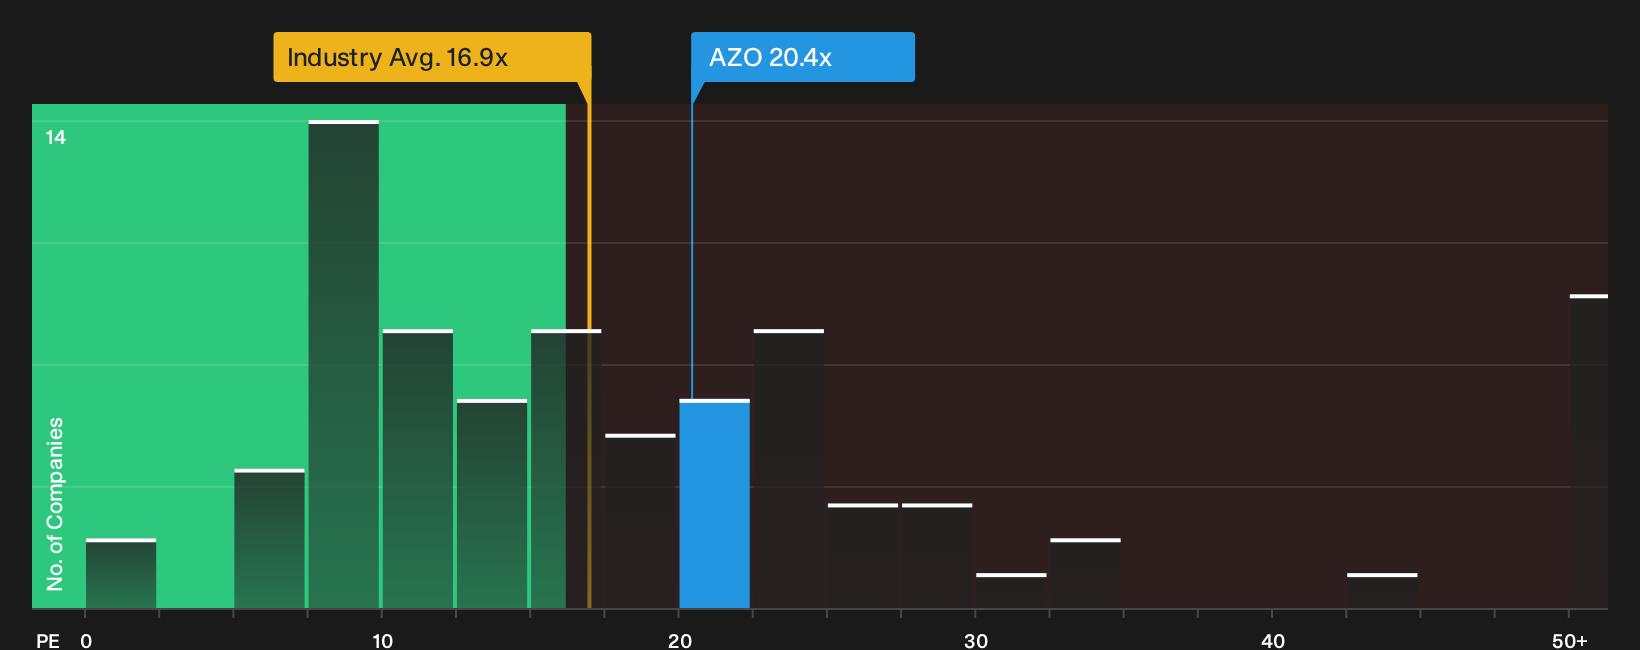
The community fair value pins AutoZone at $2,829.08, which frames the stock as 15% overvalued. A different lens tells a softer story. On a P/E of 20.4x, the shares trade below peer averages at 22.1x, and only slightly above a fair ratio of 20.2x. This points to limited margin of safety rather than clear excess. For an investor, the real question is how comfortable that narrow buffer feels if sentiment shifts.
To see what the numbers say about this price in more detail, look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on AutoZone's valuation make this a judgment call. Look through the same figures, pressure test the key risks and rewards, and ground your own stance in the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond AutoZone?
If AutoZone has sharpened your thinking on valuation and quality, expand your watchlist now so you are not relying on a single opportunity.
- Target stronger value by reviewing the 34 high quality undervalued stocks that pair quality fundamentals with more appealing pricing.
- Strengthen your income stream by scanning the 6 dividend fortresses that aim for yield with balance sheet support.
- Reduce portfolio stress by focusing on the 30 resilient stocks with low risk scores that score well on resilience and financial health.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com