
Is First American Financial (FAF) Undervalued On Its Dividend News And Board Update?
First American Financial (FAF) is back on investors’ radar after two fresh signals. The company appointed veteran insurance executive Darryl D. Button to its board and affirmed a quarterly dividend of US$0.61 per share.
Against this board refresh and dividend affirmation, First American Financial’s share price has been choppy, with a 1-day share price return of 0.73% but a 90-day share price return down 11.36%, while the 3-year total shareholder return of 26.64% signals longer term momentum.
Scan how First American Financial compares with other dividend-focused financial stocks by reviewing a curated list of 6 dividend fortresses in similar income-orientated sectors.
First American Financial now sits at US$64.87 after a mixed run, paired with a reaffirmed payout. Do you lean into the current setup, or wait for a cheaper entry before the valuation stacks up for you?
Most Popular Narrative: 17.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, First American Financial screens as undervalued, with a fair value of $79 against the recent $64.87 close. This anchors the case that the stock offers a valuation gap shaped by future earnings assumptions and margin pressure.
The anticipated normalization and eventual rebound in U.S. home purchase volumes driven by demographic tailwinds as Millennials and Gen Z enter prime homebuying years still points to First American Financial as a potential beneficiary of higher residential transaction counts. This would support title revenue and operating leverage when purchase activity moves off trough levels.
Accelerating adoption and rollout of proprietary technology platforms such as Endpoint and Sequoia has progressed, with automation now covering a rising share of escrow tasks and title decisioning. Management is targeting broad branch and national deployment by 2027, which extends the potential for structurally higher net margins as more of the workflow becomes automated.
See why 3 investors see First American Financial as 18% undervalued.
Result: Fair Value of $79 (UNDERVALUED)
Still, the story can break if residential real estate activity stays weak for longer or if title waiver programs expand and chip away at refinance volumes.
Find out about the key risks to this First American Financial narrative.
Another View: DCF Flags a Very Different Fair Value
The analyst narrative frames First American Financial as undervalued around $64.87 against a $79 fair value, yet the SWS DCF model paints a much harsher picture. On that cash flow lens, the estimated value is just $7.42, which implies a large gap that points to meaningful valuation risk.
If cash generation ultimately matters more than earnings multiples for you, the DCF result deserves a closer look Look into how the SWS DCF model arrives at its fair value.
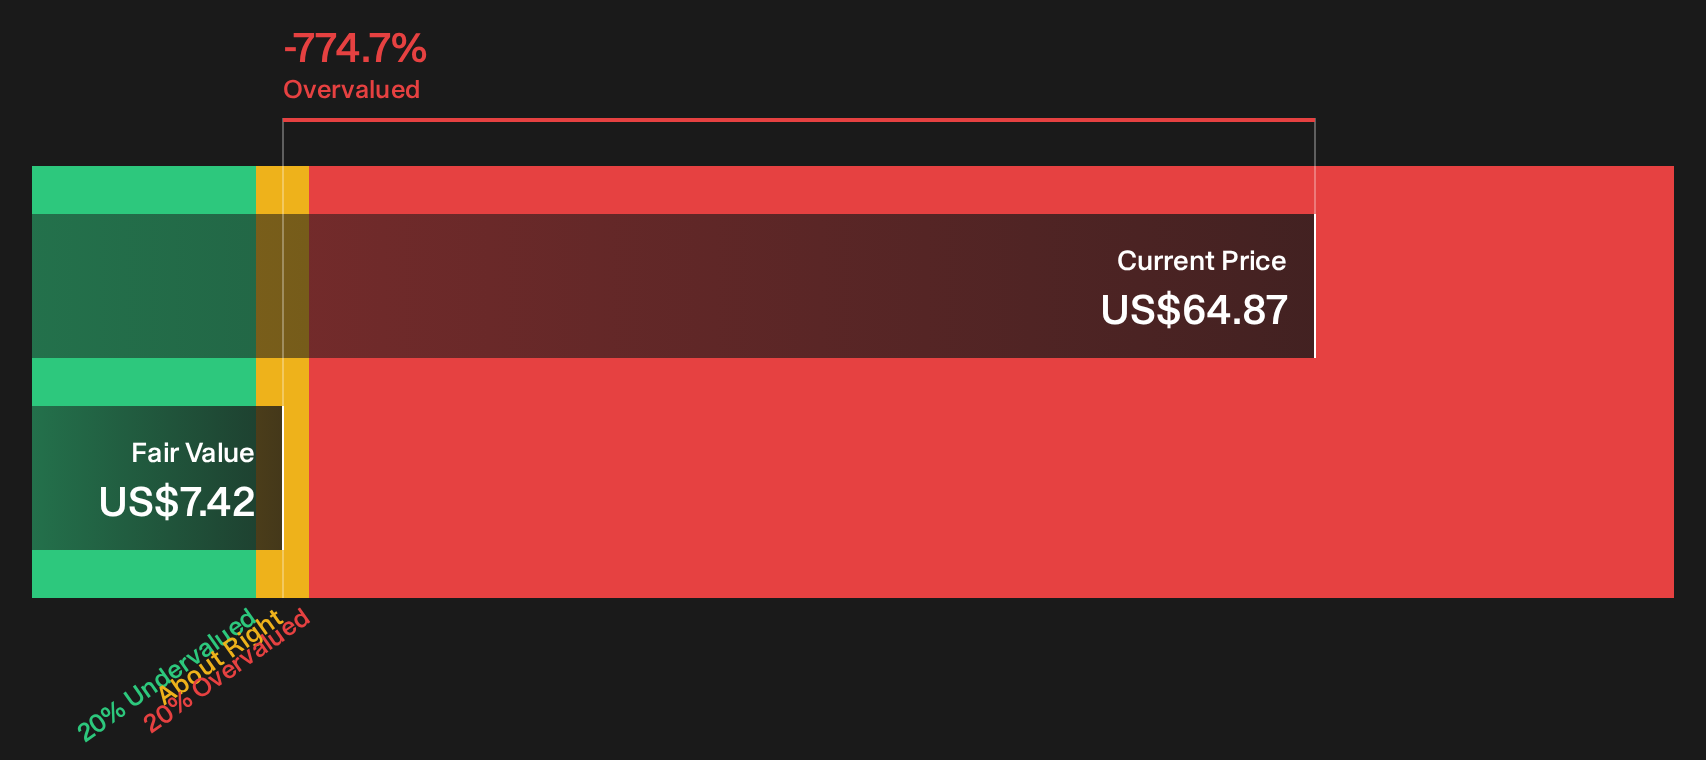
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First American Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or early opportunity? With both risks and rewards on the table for First American Financial, move quickly, review the data, and weigh the 5 key rewards and 1 important warning sign.
Looking for more ideas beyond First American Financial?
If First American Financial has you thinking about what else might be on the table, use this moment to scout fresh ideas before they move without you.
- Target higher potential upside by scanning a curated set of underpriced opportunities through the 34 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night positions by reviewing a 29 resilient stocks with low risk scores that filters for sturdier businesses.
- Hunt for future leaders hiding in plain sight by checking a focused pool of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com