
Dominion Energy (D) Stock May Be Cheap On Merger Opposition
Dominion Energy has delivered a solid multi year return, and with the stock recently closing at US$67.66, investors are increasingly asking whether that price still lines up with what its earnings can support.
- Over the past 3 years the share price has gained 66.6%. That puts the spotlight on whether the earnings story has kept pace with that move.
- The proposed merger with NextEra Energy could reshape how Dominion Energy funds future grid investments and data center demand, which can affect how investors think about the durability and timing of its profit stream.
- Your read on Dominion Energy is one view; the desks covering it have another. See what analysts think Dominion Energy's shares could be worth.
The stock's next move may depend on whether Dominion Energy's current earnings justify the valuation investors are paying today.
If you are weighing whether Dominion Energy's recent 66.6% three year return and merger risk are fairly reflected in the price, it can help to compare that earnings story with 44 power grid technology and infrastructure stocks.
Is Dominion Energy Still Cheap on Earnings?
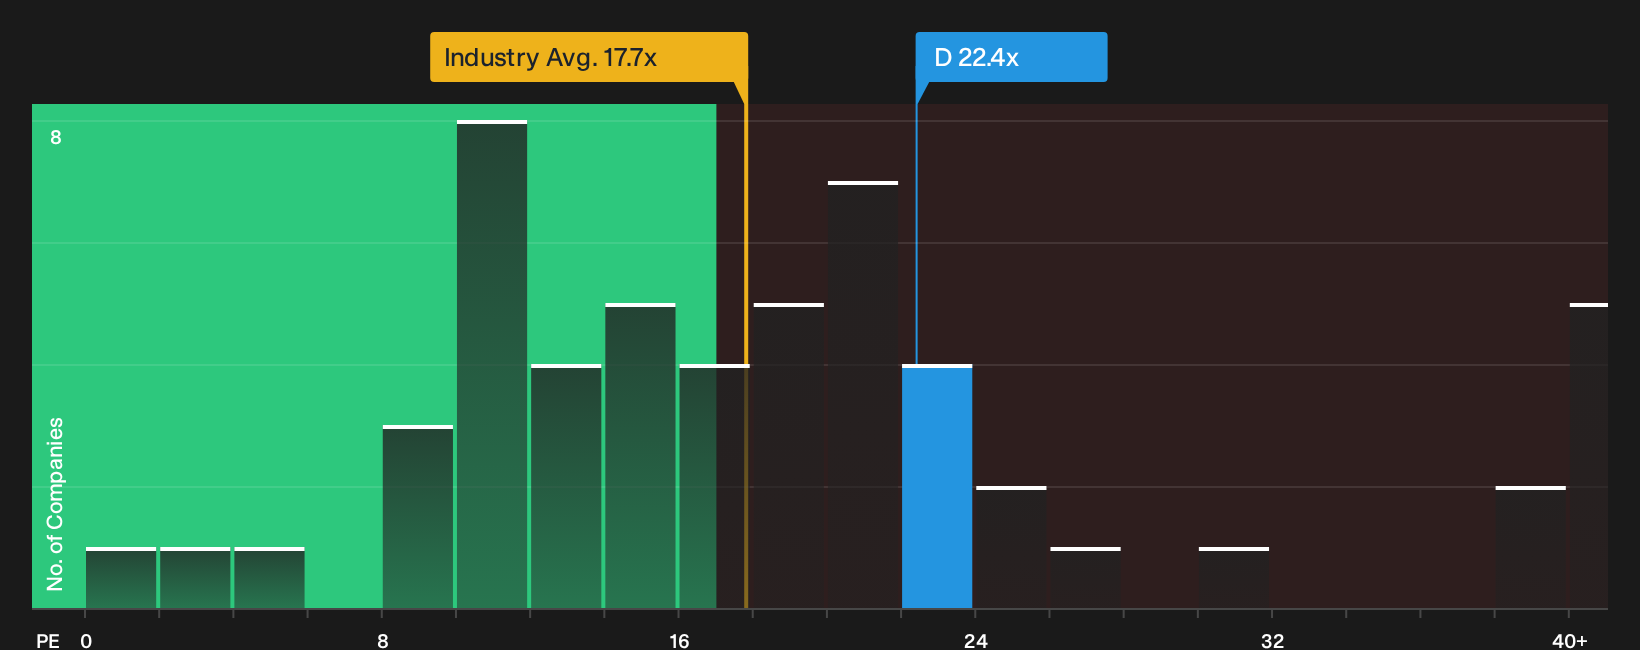
The P/E ratio fits Dominion Energy because earnings remain the main anchor for how investors value a regulated utility. On this yardstick, the stock trades on roughly 22.4x earnings, compared with about 17.7x for the wider Integrated Utilities group and around 19.8x for closer listed peers. That points to investors paying a premium earnings multiple for Dominion Energy relative to the sector.
Because the proposed merger with NextEra Energy could reshape how future profits are earned and regulated, the current P/E also reflects expectations around that deal and the risks regulators are weighing in Virginia. The valuation model that blends Dominion Energy’s growth profile, margins, scale and risk suggests a lower P/E would be more typical. As a result, the current 22.4x sits above that tailored benchmark and screens as overvalued on this measure. Explore the numbers behind Dominion Energy's P/E valuation.
The Dominion Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Dominion Energy's valuation puzzle leaves off, spelling out which paths for growth, margins and earnings would need to hold for the share price to look meaningfully higher or lower than it does today on the Community page. Each one treats Dominion Energy's fair value as a thesis about how the business might develop, so you can watch how that view holds up over time.
One of the top narratives on Dominion Energy: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor that has to go right is continued constructive regulatory and policy support for large capital plans across Virginia, the Carolinas and other jurisdictions..."
Discover why this Narrative puts Dominion Energy at roughly fairly valued.
Before acting on Dominion Energy's valuation, there is one more piece to check
Price, earnings and merger risk only tell part of the story for Dominion Energy, because the people setting priorities and how they are rewarded can strongly shape future decisions. See who runs Dominion Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com