
Ascendis Pharma (ASND) Stock Looks Reasonable Following Its 22% Run
Ascendis Pharma has seen its stock climb in recent weeks, and that move puts a sharper spotlight on what investors are actually paying for in terms of earnings. With the price now well above where it sat a month ago, the question is whether the current valuation still lines up with the company’s profit profile.
- The share price is up 22.3% over the past month, which raises the stakes on whether recent enthusiasm is fully supported by Ascendis Pharma’s underlying earnings power.
- New progress in commercializing the TransCon platform and expanding approved products can feed into expectations for future profitability and the timing of cash generation that matter directly to any earnings based valuation.
- The analysts covering Ascendis Pharma have run their own numbers. See what analysts think Ascendis Pharma's shares could be worth.
The issue now is whether Ascendis Pharma’s current share price is justified by its earnings when set against the Fair Ratio benchmark.
To see how Ascendis Pharma’s recent earnings story compares with other opportunities, it can help to line it up against companies in 34 high quality undervalued stocks.
Is Ascendis Pharma Still Cheap on Earnings?
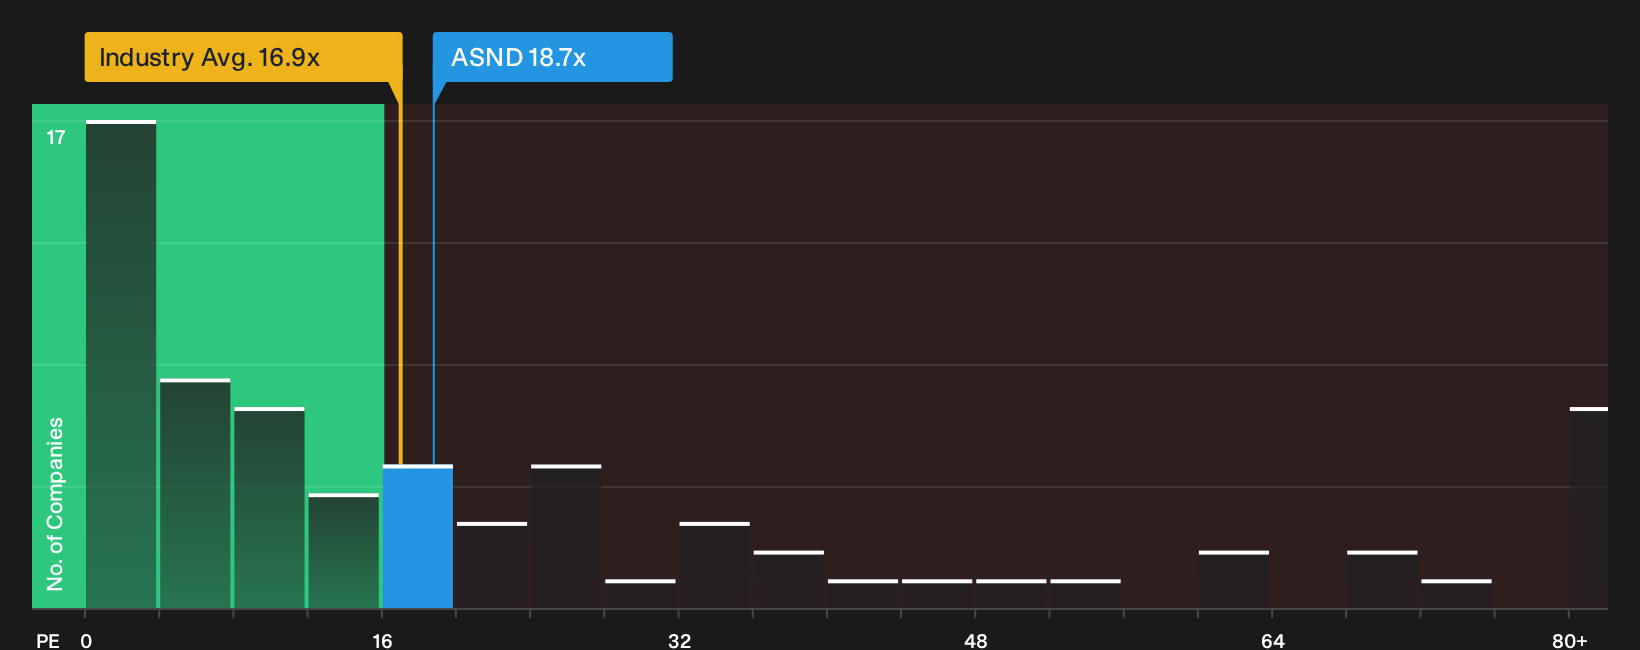
The P/E ratio is a useful lens for Ascendis Pharma because investors are focused on how its earnings compare with its growing commercial footprint. On this basis, the stock trades on about 18.7x earnings, which is below both the Biotechs sector average of roughly 16.9x and the broader peer group on about 39.5x. The Fair Ratio model, which blends factors such as growth prospects, profitability profile, size and sector risk into a single benchmark, indicates that Ascendis Pharma is trading at a lower multiple than might be expected for those fundamentals, which screens as undervalued on this metric.
Because management has just reported strong Q3 2026 results and highlighted a shift toward a more cash-generating commercial setup, the current discount on the P/E multiple suggests that recent news has not fully closed the gap implied by that benchmark or by higher-rated peers. That tension between improving operations and a still muted earnings multiple is what investors may want to weigh before deciding whether the recent share price move has already captured the story. Explore the numbers behind Ascendis Pharma's P/E valuation.
The Ascendis Pharma Narrative: What Would Justify Today's Price?
Narratives pick up where the Ascendis Pharma valuation puzzle leaves off. They spell out which expectations on growth, margins and earnings would need to hold for Ascendis Pharma's share price to look meaningfully higher or lower than today, and each scenario links a fair value to a clear storyline about potential catalysts and risks so you can track over time which version of events seems to be unfolding.
Ascendis Pharma splits opinion, with one view seeing more long term potential in the TransCon platform than the other.
Bull case: 10% undervalued
The analyst consensus Narrative on Simply Wall St leans into platform breadth and recurring endocrine revenue when it sketches the upside.
"Partnerships such as the collaboration with Novo Nordisk on once monthly TransCon semaglutide and ex U.S. partners like Teijin for endocrine products extend the TransCon model into larger disease areas and additional geographies…"
Discover why this Narrative puts Ascendis Pharma at 10% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St focuses more on pipeline concentration, capital allocation and cardiometabolic execution risk.
"Despite the cardiometabolic franchise and once monthly semaglutide program being positioned as new growth areas, taking full ownership of development after regaining rights means Ascendis Pharma now absorbs the entire cost and execution risk…"
Explore why this Narrative puts Ascendis Pharma at roughly fairly valued.
The Ascendis Pharma share price is only one piece of the risk puzzle
Before you lean too hard on the current valuation, it helps to know that Simply Wall St's checks have flagged specific risk factors for Ascendis Pharma that deserve a closer look. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com