
Exelixis (EXEL) Stock May Trade At A Discount On Fresh Cancer Research
Exelixis has ridden a powerful multi year upswing, and the question now is whether the current share price is still anchored in the company’s earnings profile. With such a strong run behind it and fresh research updates coming through, investors are asking how much of the earnings story is already reflected in today’s valuation.
- Over the past 5 years the stock has delivered roughly 283% in total returns, which puts real pressure on the earnings picture to justify how far the valuation has traveled.
- New preclinical data on Exelixis’ PLK4 inhibitor EXEL-1855, which showed suppressed tumor growth in mouse models, may support expectations for future revenue and cash flow streams if the research eventually translates into commercial success.
- The analysts covering Exelixis have run their own numbers. See what analysts think Exelixis's shares could be worth.
The stock’s next move may depend on whether Exelixis’ current earnings and their trajectory are strong enough to support where the share price has arrived today.
If you are weighing Exelixis against similar earnings driven stories, it can help to compare it with 34 high quality undervalued stocks.
Does Exelixis Look Undervalued on Earnings?
P/E fits Exelixis because investors are weighing the price of the shares directly against the earnings behind its cancer drug portfolio.
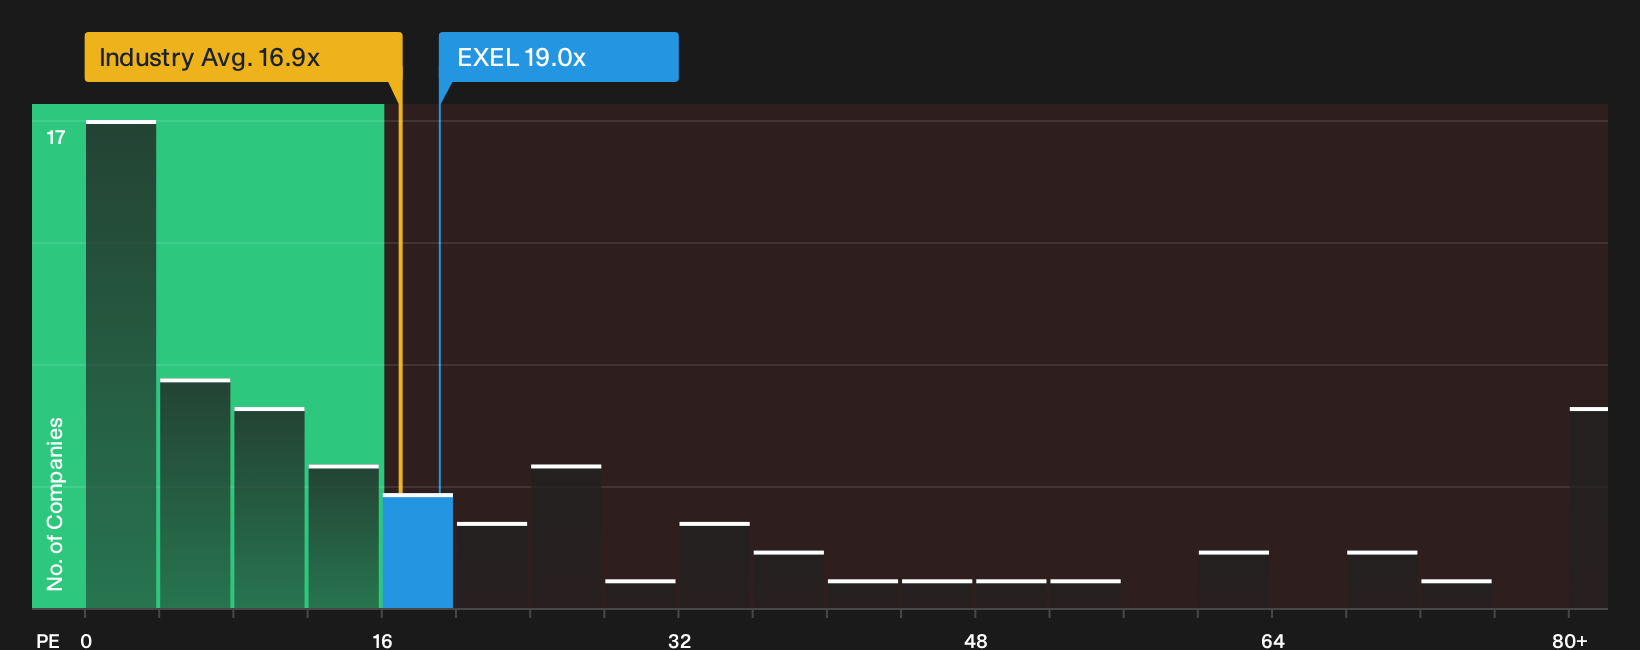
The stock currently trades on a P/E of 19.0x, which is below the broader biotech industry average of 16.9x and well under the roughly 32.3x peer group level. On this framework, the tailored fair multiple that adjusts for Exelixis' own growth profile, profitability and risk points to a higher figure, so the current P/E screens as undervalued rather than stretched.
Because the recent EXEL-1855 preclinical data has focused attention on Exelixis' pipeline potential, it is striking that the shares still change hands at a discount to what that fair multiple model would imply. For anyone trying to judge whether the market is underpaying for those earnings and optionality, the gap between the live P/E and that calibrated benchmark is the key number to examine next. Explore the numbers behind Exelixis's P/E valuation.
The Exelixis Narrative: What Would Justify Today's Price?
Narratives pick up where the Exelixis valuation puzzle leaves off and spell out the specific assumptions on growth, margins and future earnings that would need to hold for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Instead of a single ratio or model output, they lay out the future that number relies on so you can watch how reality tracks against those expectations.
The two Exelixis views sit on opposite sides, with one seeing meaningful upside and the other saying expectations already look full.
Bull case: 12% undervalued
This is how the bullish analyst Narrative on Simply Wall St frames the upside scenario for Exelixis.
"The current valuation suggests the market may be treating Exelixis primarily as a cabozantinib cash generator, with limited recognition of a potential multi-franchise oncology model and ongoing capital returns…"
Discover why this Narrative puts Exelixis at 12% undervalued.
Bear case: 12% overvalued
The analyst consensus Narrative on Simply Wall St sees Exelixis much closer to fully priced.
"The current view that Exelixis is fairly valued and bullish implies the share price already reflects a strong CABOMETYX cash engine, successful zanzalintinib approvals across key indications, and disciplined R&D and buyback-driven capital returns…"
Explore why this Narrative puts Exelixis at 12% overvalued.
One more Exelixis check that belongs beside the earnings math
Price, profits and pipelines matter a lot, but the people steering Exelixis and how their pay lines up with your interests can be just as important to understand. See who runs Exelixis and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com