
What PayPal Stock's Germany Fee Probe Means For Shareholders
- PayPal Holdings has attracted fresh attention after Germany's competition watchdog opened a formal probe into its 2018 merchant surcharge rules and investors revisited the firm's earnings estimates, bank charter ambitions and leadership transition under CEO Enrique Lores.
- The investigation into PayPal's fee and surcharge structure directly touches the economics of its branded checkout business, a key profit engine. Current earnings expectations and product plans implicitly rely on this remaining commercially attractive for merchants.
- The focus now is how PayPal's long term investment narrative holds up as we weigh German regulatory pressure on merchant fees against that story.
Compare how PayPal Holdings stacks up against other payment and fintech stocks by scanning a curated list of 19 high quality undiscovered gems while this regulatory story unfolds.
PayPal Holdings Investment Narrative Recap
To own PayPal Holdings, you need to believe this is a large, resilient payments platform that can keep its 440 million active accounts engaged while stabilizing key profit pools like branded checkout. According to Benjamin_Ziegler, an investor in the Simply Wall St Community, the real swing factor is whether Branded Checkout and transaction margins hold steady rather than accelerate.
Right now, the biggest near term catalyst is evidence that branded checkout volumes and margins remain attractive for merchants. The German fee probe targets that cash register directly but is limited in geographic scope, so the operational impact looks more like a watchpoint than a thesis breaker unless it triggers wider copycat regulation.
The most relevant development around this story is PayPal’s push for a bank charter in the United States. Management has flagged this as a way to broaden financial services for merchants and consumers, support lending and access new funding sources, including deposits, which currently are not part of the liability mix.
If the German regulator ultimately pressures merchant fee economics, a bank license could become more important for investors who are monitoring funding costs and product flexibility. A charter could offer extra tools for Enrique Lores as he restructures the business and addresses risks that Benjamin_Ziegler highlights, such as margin pressure and any erosion in the core checkout franchise.
On that basis, Benjamin_Ziegler sees fair value at about US$68. The key driver is a move from an 8x P/E to 12x on earnings that are broadly stable, supported by ongoing buybacks and the view that PayPal Holdings only needs to hold its ground rather than grow aggressively.
Uncover why PayPal Holdings' fair value indicates a 15% potential upside to its current price that could narrow quickly.
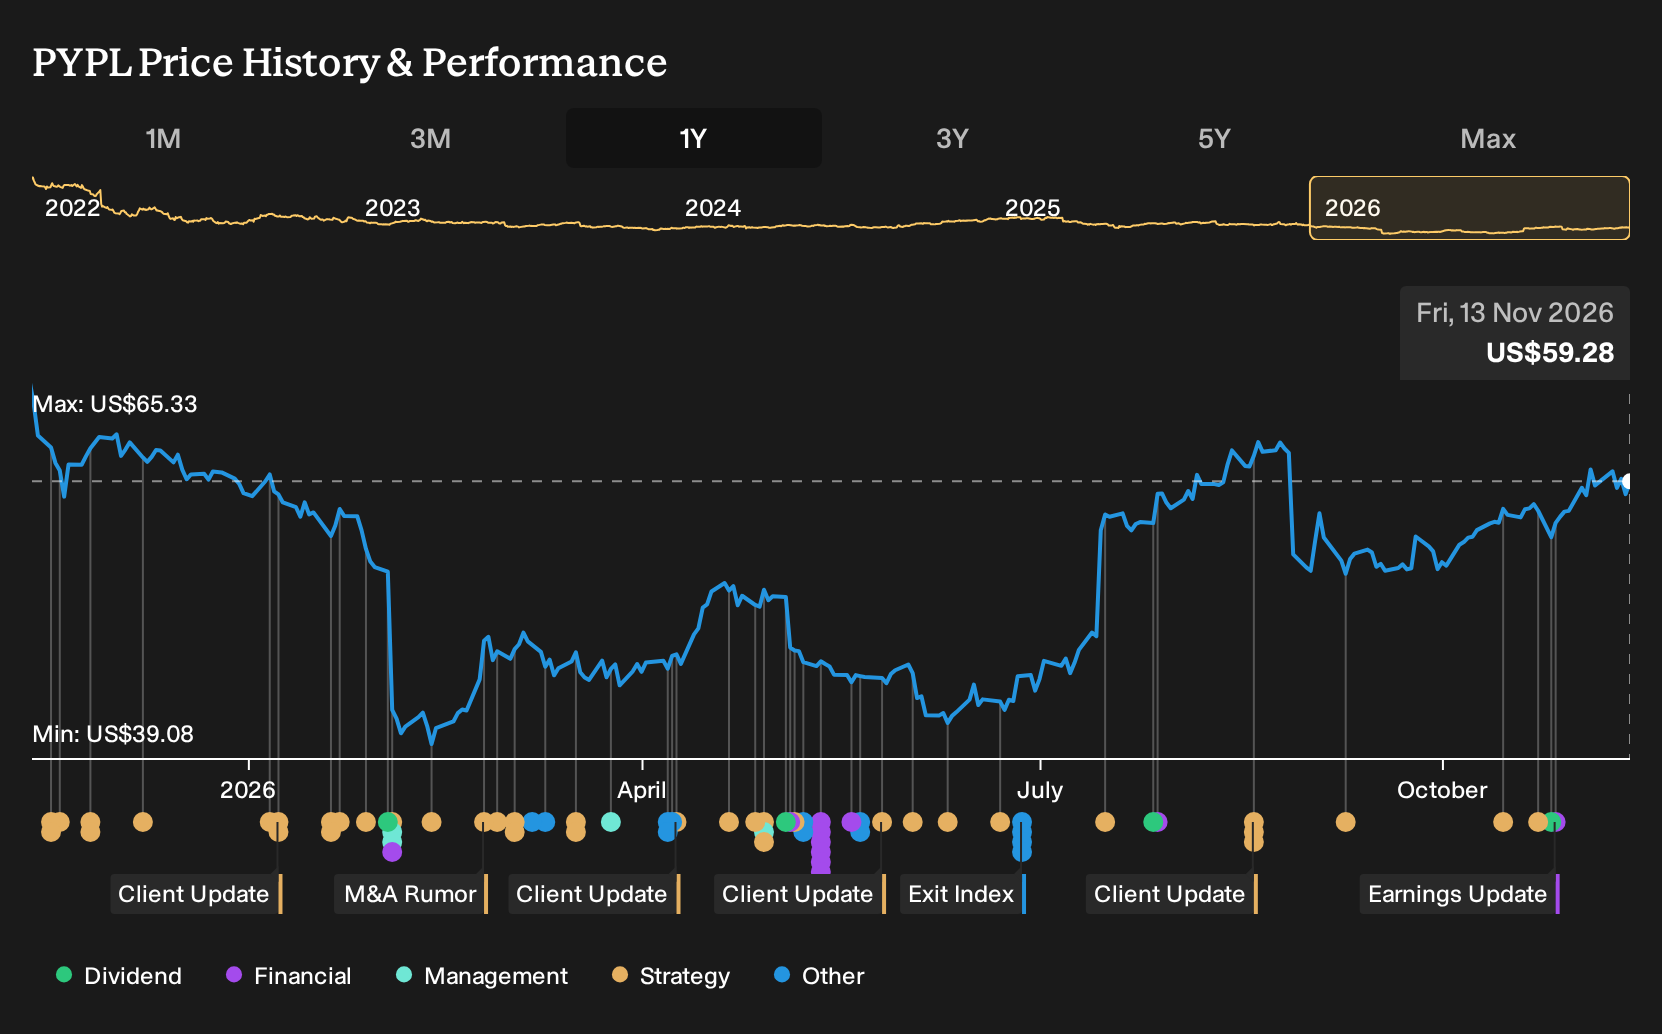
Exploring Other Perspectives
Some of the lowest analysts frame the German probe very differently. You might see the surcharge rules as a narrow issue for PayPal Holdings, while they already worried that a 1.61% transaction take rate and revenue of about US$37.2b by 2029 could still support only US$4.4b of earnings. Their pre news view was far more cautious, so fresh regulation could push those expectations in either direction. Exploring those alternative forecasts can help you test your own stance before the story moves on.
Explore 24 other PayPal Holdings fair value estimates, including one that suggests it could be worth just $56.92.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PayPal Holdings research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PayPal Holdings' overall financial health at a glance.
Looking for more investment ideas beyond PayPal Holdings?
If this PayPal Holdings story has sharpened your thinking, use that same lens on a wider watchlist. The Simply Wall St Screener lets you quickly filter for different types of opportunities and stress test your thesis across other businesses.
- If you care most about stability, focus on companies that pair resilient operations with measured risk using the 29 resilient stocks with low risk scores.
- If balance sheet strength is your starting point, shortlist businesses with solid finances through the list of solid balance sheet and fundamentals (24 results).
- If you want income on top of potential capital returns, scan for reliable cash distributors via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com