
NMI Holdings (NMIH) Stock May Look Reasonable As Earnings Backdrop Faces Questions
NMI Holdings has delivered a solid 5 year share price gain, yet recent softer returns have put a spotlight on whether the current valuation is still backed by its earnings power. With the stock now trading at US$38.65, the question for you is how well that price lines up with what the business earns today and is expected to earn over time.
- The share price is up 85.1% over the past 5 years, which raises the question of how much of that move is supported by the underlying profit engine.
- The business model is tightly linked to the credit quality of insured mortgages and disciplined underwriting, which can influence how sustainable its earnings base is and how much investors are willing to pay for each dollar of profit.
- There is a second opinion on NMI Holdings worth weighing. See what analysts think NMI Holdings's shares could be worth.
The stock's next move may depend on whether NMI Holdings' current share price is adequately explained by its earnings and the multiple investors assign to those profits.
If you want to test the same earnings driven valuation question you are asking about NMI Holdings across a broader watchlist, start by scanning 34 high quality undervalued stocks.
Is NMI Holdings a Bargain on Earnings?
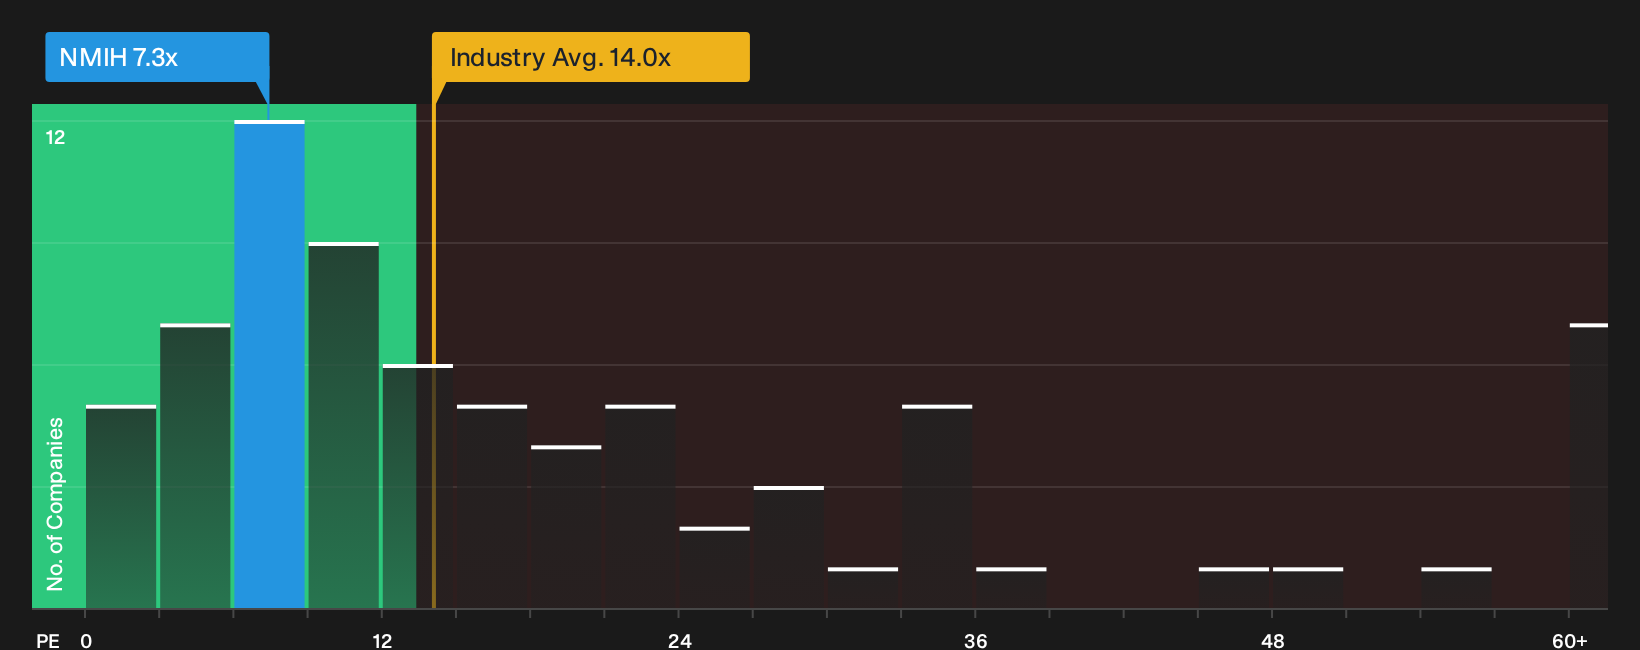
P/E fits NMI Holdings because earnings are the main driver of value for an insurer style business. At the current price, the stock trades on a P/E of 7.3x, below both the diversified financial industry average of 14.0x and the peer group on 9.8x. That suggests the market pays fewer dollars for each dollar of NMI Holdings earnings than it does for many comparable financial stocks.
The valuation model that blends the company’s growth outlook, profitability, size and risks points to a higher P/E as a fairer anchor. As a result, the present 7.3x level sits below that implied range and screens as undervalued on this lens. For you as a shareholder or prospective buyer, the key question is whether the earnings quality, mortgage credit exposure and return on equity profile justify the gap or whether it reflects an overly cautious stance on the business. Explore the numbers behind NMI Holdings's P/E valuation.
The NMI Holdings Narrative: What Would Justify Today's Price?
NMI Holdings' Simply Wall St Narratives pick up where the valuation puzzle leaves off and explain which combinations of future growth, profitability and earnings power would need to hold for the share price to be materially higher or lower than it is today. All of this is housed on the Community page so you can track how each storyline, with its own implied fair value tied to specific catalysts and risks, lines up with what actually unfolds over time.
One of the top narratives on NMI Holdings: 18% undervalued
This is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies the share price does not fully reflect the company’s record profitability, large excess capital and ongoing share repurchases…”
Discover why this Narrative puts NMI Holdings at 18% undervalued.
One more NMI Holdings check before you stop at the share price
The final question is who is steering NMI Holdings and how their incentives line up with the results you have just assessed, because that alignment can shape what happens from here as much as any multiple. See who runs NMI Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com