
Sansan And 2 Other Top Japanese Growth Stocks
Global credit is tightening as higher interest rates and heavy debt loads make life harder for weaker borrowers. Investors are rewarding financially healthier Japanese companies that can fund growth without stretching their balance sheets. That is where this high growth, solid fundamentals theme comes in. This article highlights 3 Japanese stocks from the screener that combine strong earnings potential with relatively robust finances, helping you focus on quality growth ideas.
The three stocks highlighted here offer a compelling starting point if you want exposure to financially healthier high growth potential businesses. However, if you want the absolute best, these 19 best high growth potential stocks are the cream of the crop.
Sansan (TSE:4443)
Overview: Sansan provides cloud tools that turn business card and contact data into shared, searchable databases that streamline sales, invoicing, and contract workflows.
Operations: Sansan generates about ¥48.9b from its Sansan and Bill One segment, ¥7.1b from Eight, and ¥0.4b from Others, almost entirely in Japan at ¥56.2b.
Market Cap: ¥274.9b
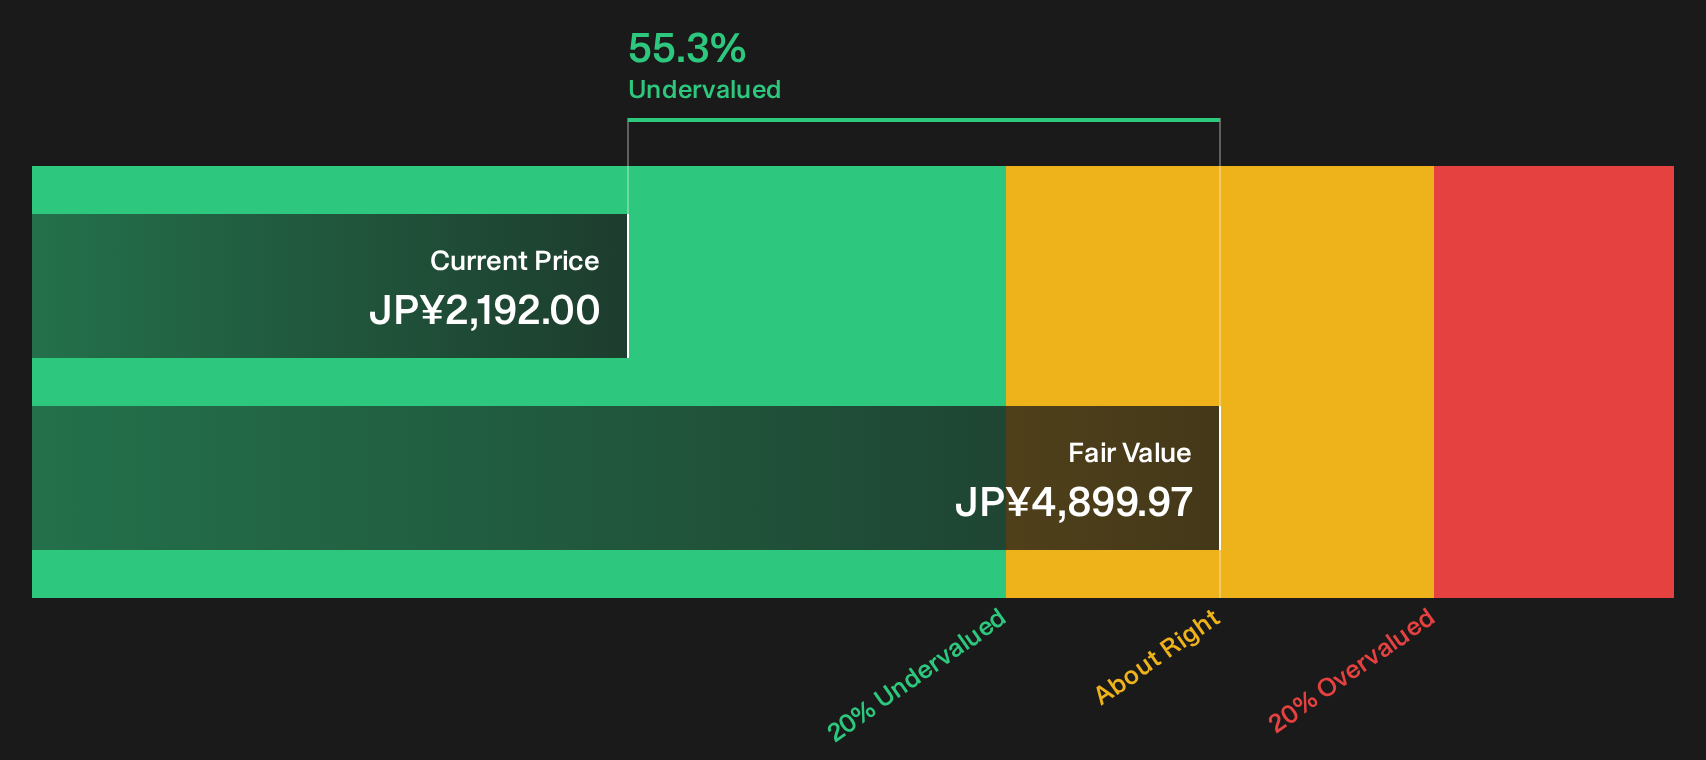
Sansan aligns tightly with the Healthy high growth potential theme, with earnings projected to rise about 23.4% a year and net margins at 14.3%. The stock trades at a large discount to an estimated future cash flow value. This valuation could matter significantly for long term returns, depending on how an unseen pressure around translating that contact data network into durable pricing power develops.
To see how that tradeoff between valuation and pricing power could be playing out, check the DCF valuation analysis for Sansan and identify where expectations might be misaligned.
Micronics Japan (TSE:6871)
Overview: Micronics Japan develops semiconductor test equipment such as probe cards, wafer probers, and test sockets, as well as smaller body-measuring and display inspection tools.
Operations: Micronics Japan generates about ¥84.9b from its Probe Card Business and ¥1.4b from TE Business, mainly across Asian semiconductor hubs.
Market Cap: ¥413.7b
Micronics Japan aligns with the Healthy high growth potential theme, with earnings forecast to grow 25.46% a year and revenue expected to rise 23.7% as high margin probe cards and test equipment serve chip makers. That growth profile depends heavily on how long current semiconductor testing demand holds up before the next cycle turn shifts the balance between pricing and volumes.
That cycle question is exactly why the 2 key rewards and 1 important major warning sign can help you see whether Micronics Japan’s growth story is masking pressure points or revealing fresh upside.

Infomart (TSE:2492)
Overview: Infomart runs B2B platforms in Japan that digitize invoicing, ordering, contracts, and payments, turning paper-heavy workflows into recurring SaaS and transaction revenue.
Operations: Infomart generates about ¥12.7b from B to B-PF FOOD and ¥7.6b from B to B-PF ES, all from Japan at roughly ¥20.3b.
Market Cap: ¥199.1b
Infomart aligns with the Healthy high growth potential theme, with earnings up 47.5% last year and forecasts suggesting growth of around 31.9% a year while net margins reach 11.8%. The trade-off is a premium P/E of 83.2x and recent dilution, so potential returns appear closely tied to how one unresolved funding pressure influences the high-margin platform story.
That funding pressure is exactly why the 2 key rewards and 2 important warning signs could show whether Infomart’s premium is masking fragility or an accelerating earnings engine.

Seeking Fresh Alternatives Beyond Today’s Ideas
Fresh opportunities move first. By the time momentum is flying, the easy entry points are often gone. Scan these curated stock shortlists before the crowd catches on and act now.
- Charge ahead with income ideas by reviewing a curated mix of resilient payers in the 29 dividend fortresses while yields still look attractive to early entrants.
- Track fast-moving infrastructure suppliers by scanning the carefully filtered 53 AI infrastructure stocks before AI demand stories are fully reflected in market prices.
- Target real asset exposure by assessing a focused group inside the 33 elite gold producer stocks while many producers remain under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com