
Starwood Property Trust (STWD) Could Be 34% Undervalued On Earnings And Buyback News
Starwood Property Trust (STWD) just paired a third quarter earnings update showing higher sales and revenue with a substantial share repurchase that completed its February 2026 buyback authorization.
Those moves landed in a tough tape for Starwood Property Trust, with the share price at $11.34 after declining 5.9% over the past week and almost 9% across the last month, while the 1-year total shareholder return is down 28.5% and the 5-year total shareholder return has also fallen, which points to fading momentum even as buybacks and quarterly results reshape how investors weigh income potential against ongoing risks.
Spot fresh ideas by comparing Starwood Property Trust with a curated 6 dividend fortresses that have kept income at the center of their story even as share prices move around.That mix of higher revenue, large losses and a completed buyback leaves a simple tension. Are investors reacting to Starwood Property Trust’s business reality, or are they just resetting the mood around the stock’s income story and valuation?
Most Popular Narrative: 34% Undervalued
Starwood Property Trust’s last close at $11.34 sits well below the analyst consensus Narrative fair value of $17.31. This valuation is based on detailed revenue and earnings forecasts in the analyst consensus Narrative on Simply Wall St and frames today’s pullback against a longer income driven thesis.
Systematic workout and recycling of roughly US$1.9b of nonaccrual and REO assets, including guidance to resolve about US$800m or 40% of the current balance by year end 2026 and the expected US$140m cash out from the Woodstar refinancing, provides a pipeline of capital that can be redeployed into higher yielding opportunities and potentially improve earnings and dividend coverage.
See why 51 investors see Starwood Property Trust as 34% undervalued.
Result: Fair Value of $17.31 (UNDERVALUED)
Still, the story around Starwood Property Trust only holds if dividend coverage improves and recoveries on the US$1.9b nonaccrual and REO pool remain on track.
Find out about the key risks to this Starwood Property Trust narrative.
Another View: What Multiples Say About Starwood Property Trust
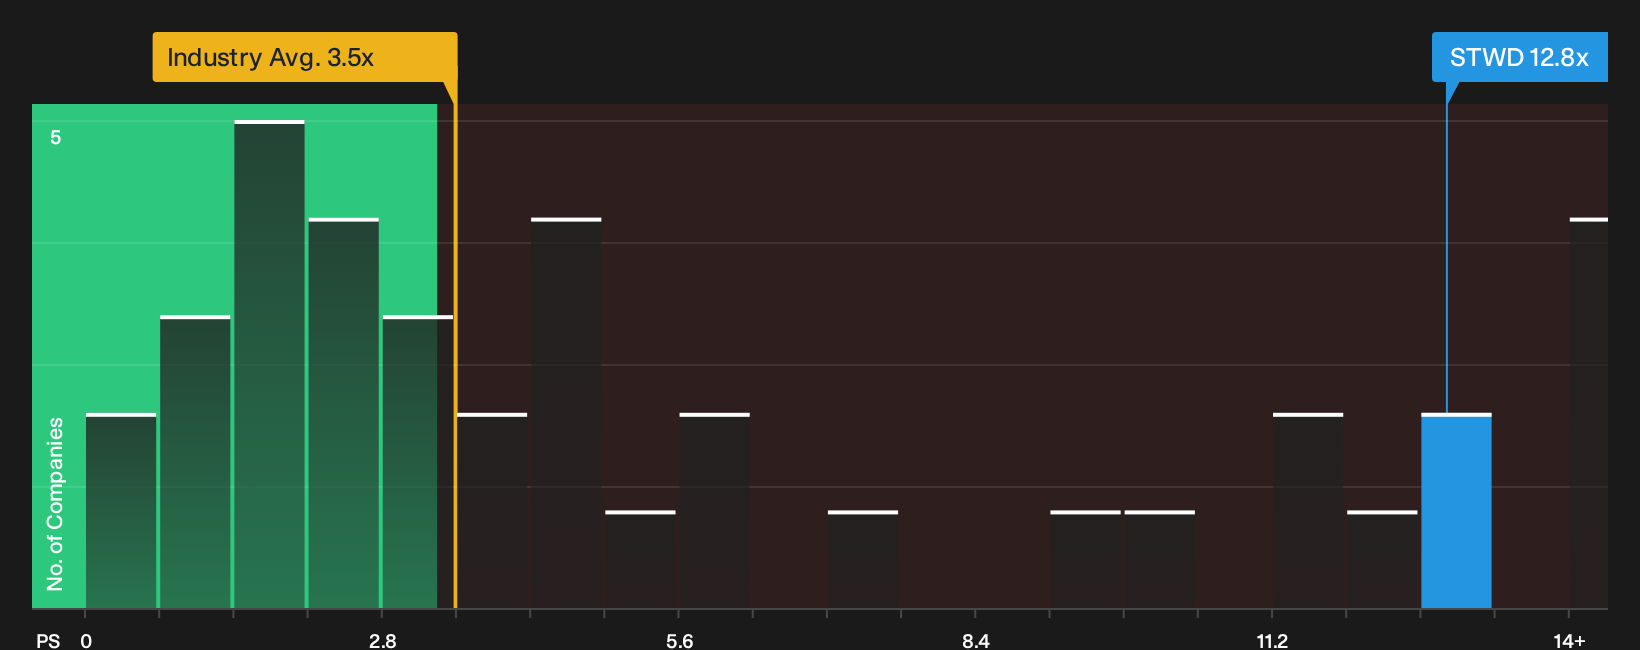
Analyst fair value on Starwood Property Trust leans on long range earnings forecasts, yet the current P/S ratio tells a different story. At 12.8x sales, the stock trades well above the US Mortgage REITs average of 3.5x and the fair ratio of 5.2x, which points to meaningful valuation risk if sentiment cools.
For investors weighing these mixed signals, our valuation breakdown explains how this rich P/S level compares with peers, the wider sector and that lower fair ratio the market could move toward over time. This can help you judge whether today's price leaves enough room for error See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Starwood Property Trust can feel confusing, so act promptly, review the underlying data and consider the balance of 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Starwood Property Trust?
If Starwood Property Trust has your attention, do not stop here. Cast the net wider so you are not relying on a single income story.
- Target resilient portfolios by checking a 29 resilient stocks with low risk scores that focuses on businesses with lower risk scores and steadier profiles.
- Hunt for mispriced opportunities through a 34 high quality undervalued stocks built to surface companies with quality fundamentals at compressed valuations.
- Strengthen your watchlist with a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with healthier financial foundations and fewer funding surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com