
Is Central Securities (CET) Undervalued On Its Dividend News Or Already Priced In?
Central Securities (CET) has put income front and center after declaring a semi-annual dividend of US$3.00 per share, payable on December 18, 2026, with an ex-date and record date of November 16.
The dividend news comes after a year in which Central Securities’ share price has climbed, with an 11.28% year-to-date share price return and a 16.20% total shareholder return over 12 months. The 3-year total shareholder return of 75.12% points to strong longer-term momentum.
Scan beyond Central Securities and see how other income-focused players stack up on payout strength and share performance with our curated list of 6 dividend fortresses.
Central Securities has recent returns on its side while income investors debate whether this latest US$3.00 payout reflects enduring value or froth built on good timing. The numbers behind CET’s current valuation start to answer that question.
Price-to-Earnings of 7.7x: Is it justified?
Central Securities trades on a P/E of 7.7x, which sits against a last close of $56.45 and a wide gap to peer valuations that income investors will notice quickly.
The P/E ratio compares what you pay for each dollar of earnings. For an investment company like Central Securities, this metric helps you see how the market is weighing its profit stream against similar capital markets players.
CET is flagged as good value on this measure when set beside both direct peers at 14.2x and the broader US Capital Markets industry at 33.4x P/E. That is a steep discount that suggests the market is pricing its earnings much more conservatively than the sector and could be treating recent profit quality questions, such as the large one off gain, with extra caution.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 7.7x (UNDERVALUED)
Still, Central Securities relies on investment income and market pricing, so weaker portfolio results or a persistent discount to intrinsic value could quickly challenge the current narrative.
Find out about the key risks to this Central Securities narrative.
Another View: What The SWS DCF Model Says
The P/E discount on Central Securities looks clear, yet our DCF model paints an even starker picture. Using that approach, CET at $56.45 trades well below an estimated future cash flow value of $153.85. This frames the stock as heavily undervalued rather than just optically cheap.
That gap suggests the market could be heavily discounting the quality and durability of Central Securities' cash flows. It also means you need to decide whether the current price reflects hidden problems or a potential opportunity that patient investors are willing to wait on.
Look into how the SWS DCF model arrives at its fair value.
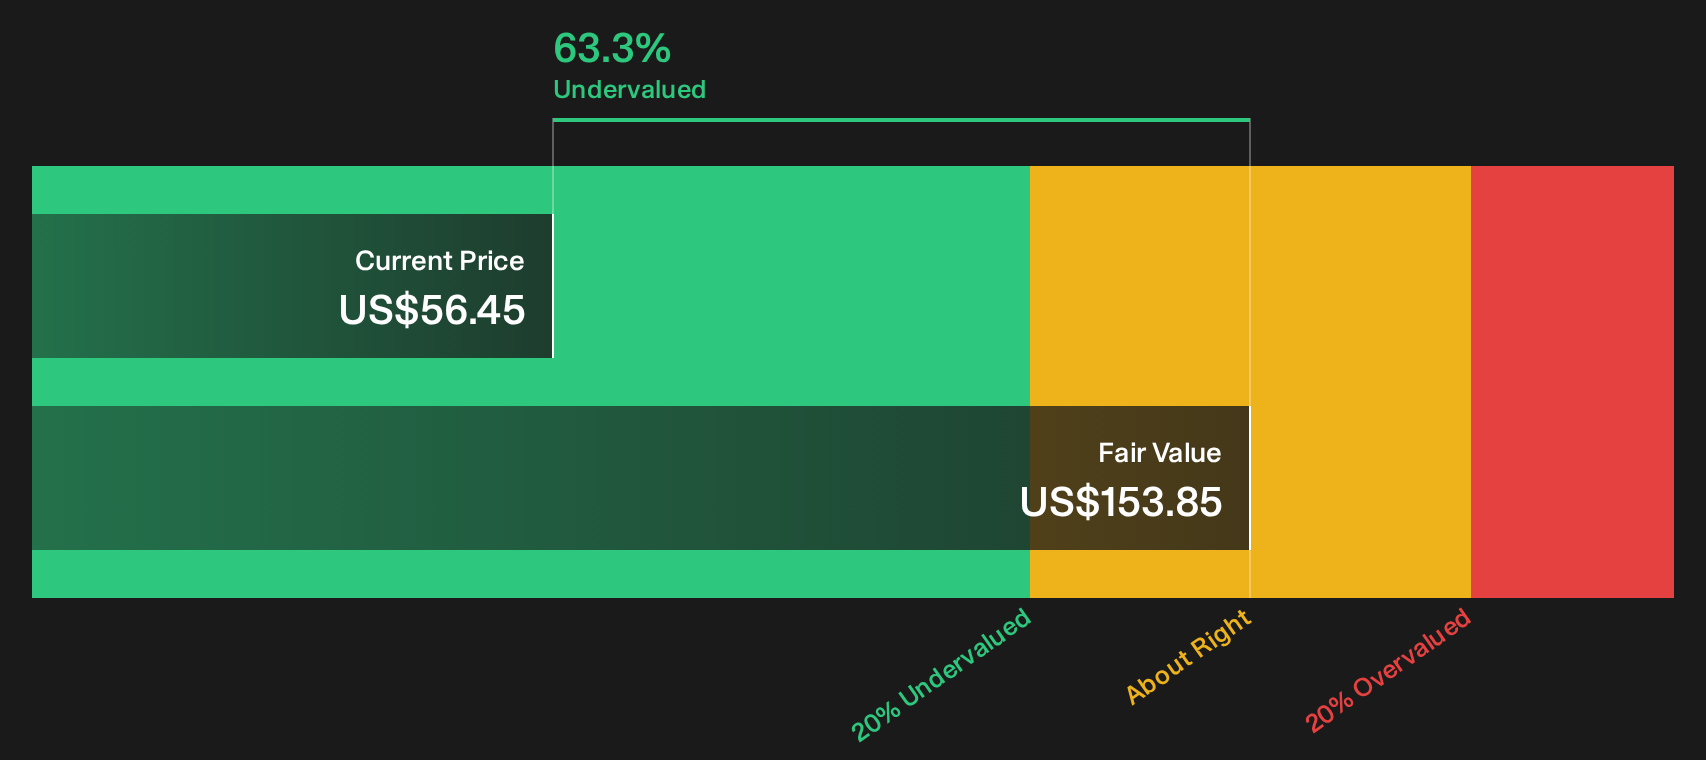
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Central Securities for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly mixed around Central Securities, you have a tight window to weigh the signals for yourself and decide where you stand. Start by reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Central Securities?
If you stop at Central Securities, you risk missing out on other opportunities that match your goals, so broaden your watchlist with a few targeted screens.
- Target steady compounding by reviewing companies with resilient cash profiles and robust finances through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by scanning the 34 high quality undervalued stocks that pair quality fundamentals with compressed valuations.
- Anchor your income plan by checking the 6 dividend fortresses that focus on higher-yield payouts supported by underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com