
Allegion (ALLE) Faces A Valuation Test On Acquisition And Demand Momentum
Allegion (ALLE) heads into its Baird 2026 Global Industrial Conference appearance on 12 November with fresh attention on how management views recent acquisitions, capital returns, and demand across its core non-residential security markets.
Recent trading shows momentum building in Allegion, with a 1-day share price return of 1.00% capping a 30-day share price gain of 22.64% and a 90-day move of 18.43%. Meanwhile, 1-year total shareholder return of 20.80% sits on top of a very strong 3-year total shareholder return of 88.55% and 5-year total shareholder return of 54.57% as investors weigh the impact of acquisitions, capital returns and demand in non-residential security markets.
Review Allegion’s latest move into non-residential security and then compare peers showing similar momentum with our curated list of 44 power grid technology and infrastructure stocks
After a sharp move toward analyst targets and an intrinsic value estimate that sits higher still, Allegion now trades in a tight band between optimism and caution. Is the market being careful for good reason?
Most Popular Narrative: 1% Undervalued
Allegion’s last close at $191.98 sits just below the analyst consensus Narrative fair value of $193.64. This estimate is built on detailed revenue, margin and P/E assumptions in the analyst consensus Narrative on Simply Wall St that go well beyond a simple chart read.
Robust expansion in smart and connected security solutions, with low teens electronics growth in the Americas in Q2 2026 and a pipeline of new Allegion products such as Schlage XE360 with RealSync Wi Fi and the Sense Pro smart deadbolt with Matter over Thread, supports a higher mix of recurring and software linked revenue and can lift both future revenue and adjusted operating margin.
See why 13 investors see Allegion as 1% undervalued.
Result: Fair Value of $193.64 (ABOUT RIGHT)
Still, the bullish Allegion story relies on electronics momentum and non residential projects continuing to offset softer International trends, along with the risk that organic growth trails analyst assumptions.
Find out about the key risks to this Allegion narrative.
Another View: Allegion Through A P/E Lens
The SWS DCF model points to a fair value of $157.44 for Allegion, which sits below the current $191.98 share price and frames the stock as overvalued on that cash flow view. That is a very different message to the analyst narrative fair value of $193.64. Which one feels more realistic to you?
Before leaning too heavily on either approach, it can help to see exactly how the cash flows are modeled and stress test the assumptions behind them with the Look into how the SWS DCF model arrives at its fair value.
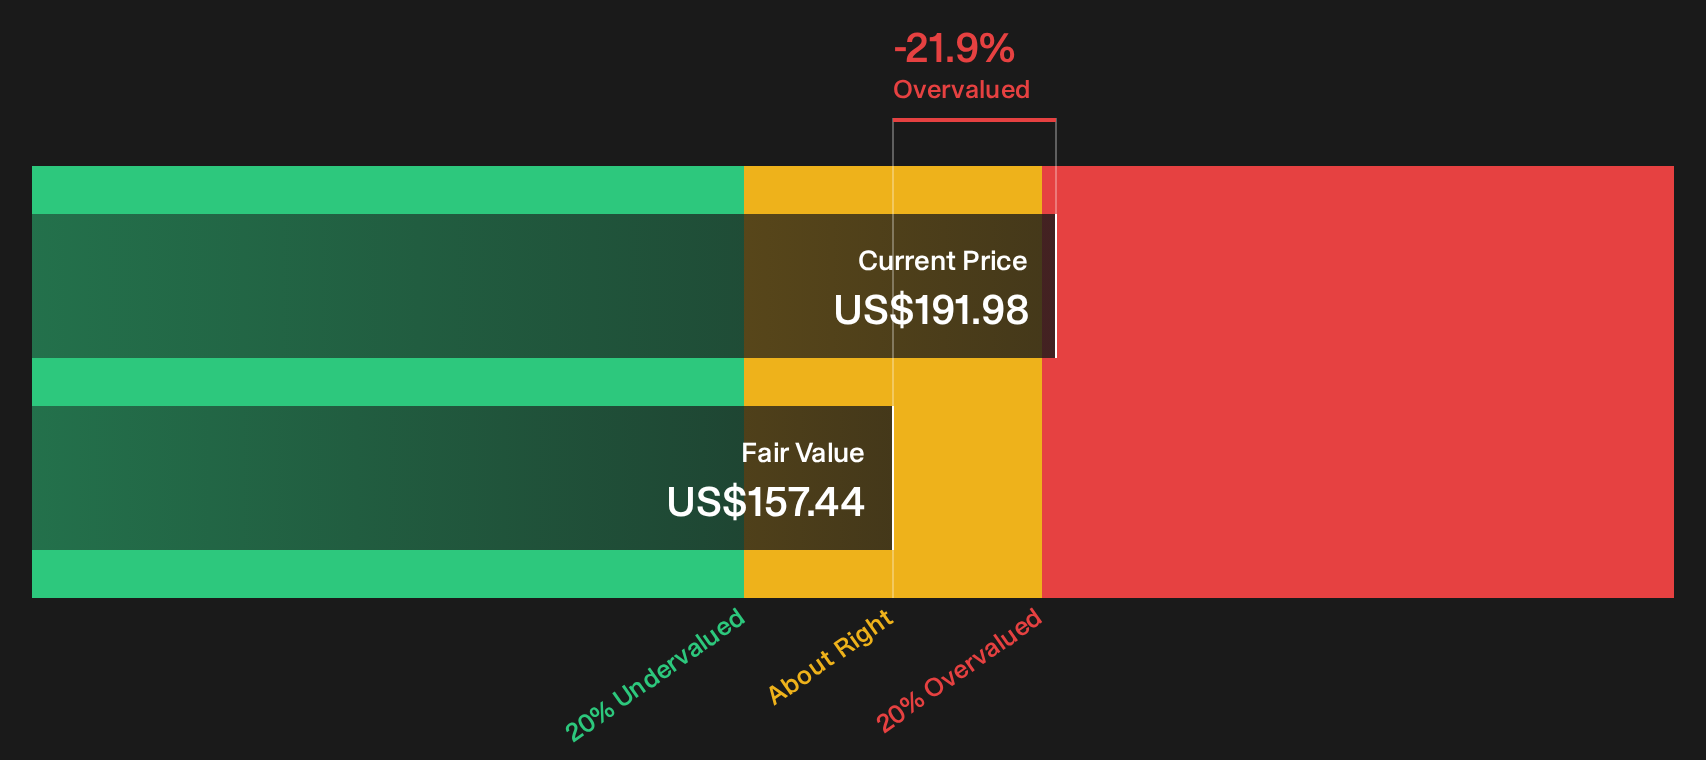
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Allegion for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Allegion’s valuation and narrative can feel confusing, so move quickly from reading to reviewing the numbers yourself and pressure testing the story. To see both sides of the argument in one place, walk through the 2 key rewards and 2 important warning signs
Looking for more Allegion sized investment ideas?
If Allegion has sharpened your focus on quality, do not stop here. Broader idea hunting with targeted screeners can surface opportunities you would otherwise miss.
- Target resilient value by scanning our 34 high quality undervalued stocks that combine solid fundamentals with prices the market may not fully appreciate yet.
- Strengthen your downside protection by reviewing the 29 resilient stocks with low risk scores that pair sturdier balance sheets with more measured risk profiles.
- Spot tomorrow’s quiet winners early by working through the 19 high quality undiscovered gems before attention and pricing catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com