
Dorman Products (DORM) Launches New OE FIX Part On An Undervalued Narrative
Dorman Products (DORM) just rolled out a new OE FIX aluminum engine oil filter housing for select Genesis, Hyundai, and Kia models, targeting a known weakness in the original plastic component.
Dorman Products' new OE FIX launch lands at a time when momentum has cooled slightly in the short term, with a 7 day share price return decline of 3.21%, even though the 30 day share price return of 6.8% and 3 year total shareholder return of 85.65% point to a much stronger longer run story.
Scan for other aftermarket specialists applying similar problem solving to OEM weak spots by starting with our curated list of 19 high quality undiscovered gems in the auto and industrial space.
Dorman Products has pulled back slightly after a strong multi year run, which puts a clear choice in front of you. Does the recent wobble already offer a fair entry, or is patience still the smarter move as the valuation case unfolds?
Most Popular Narrative: 18% Undervalued
On the analyst consensus Narrative on Simply Wall St, Dorman Products screens as undervalued, with a fair value of $161.63 compared to a last close of $132.31. Within that framework, the current price is viewed as having meaningful upside potential.
Management now targets a 2026 adjusted operating margin of 15.5% to 16.5% and expects to exit Q4 2026 at about a 40% gross margin. Management also plans to treat tariffs as pass through costs in both directions, which may support a more resilient margin structure and support future earnings quality.
See why 7 investors see Dorman Products as 18% undervalued.
Result: Fair Value of $161.63 (UNDERVALUED)
Still, the bullish Dorman Products story can crack if reduced 2026 net sales guidance and pressure in more discretionary Specialty Vehicle categories persist longer than expected.
Find out about the key risks to this Dorman Products narrative.
Another View: What Dorman Products' P/E Is Telling You
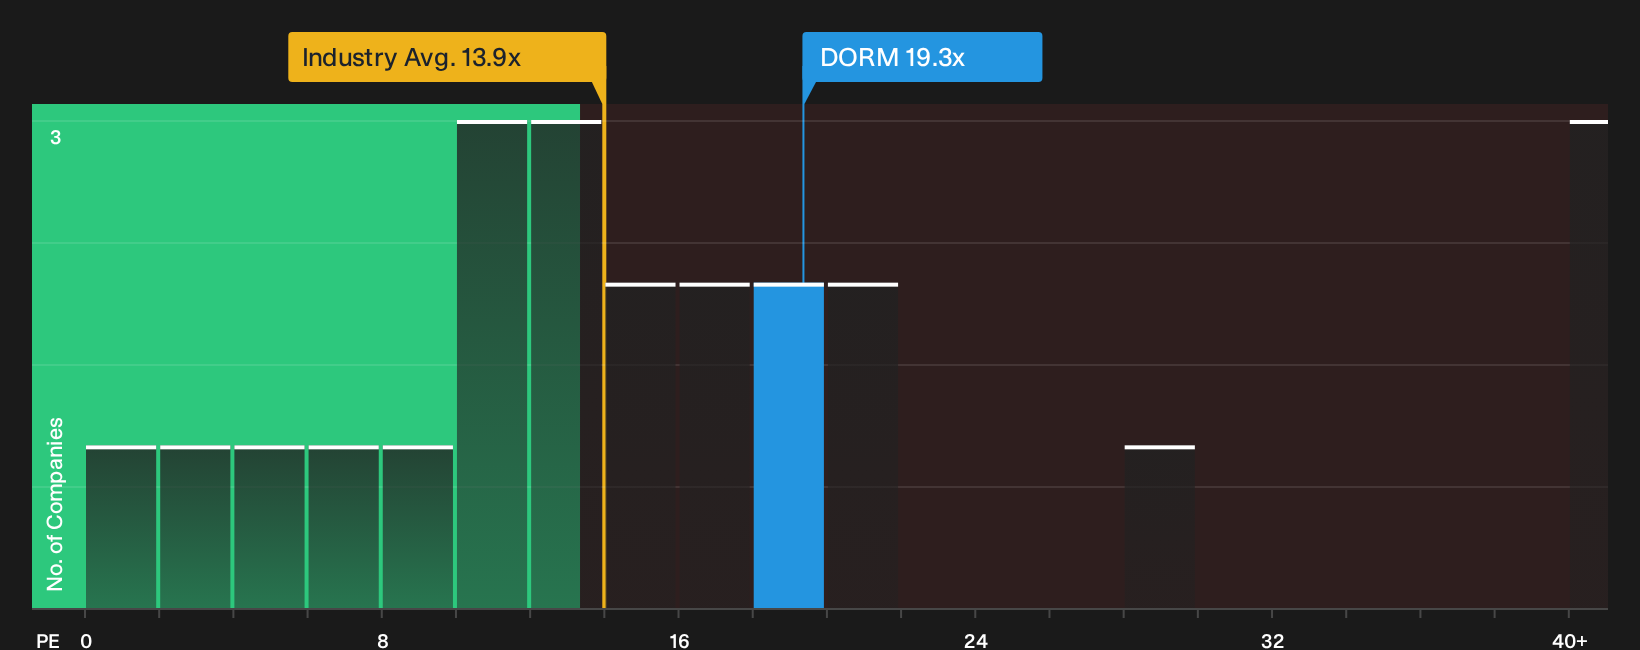
The DCF work paints Dorman Products as slightly undervalued, yet the simple earnings multiple sends a different signal. At a P/E of 19.3x versus a North American Auto Components average of 13.9x and a fair ratio of 13.2x, the stock trades on a richer earnings tag that could compress if sentiment cools.
That richer multiple can either reflect confidence in Dorman Products' forecast 11.1% annual earnings growth or expose you to valuation squeeze risk if those forecasts slip. The key question is how comfortable you are paying up for this story versus waiting for the market to move closer to the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Dorman Products story feels finely balanced, act quickly and review the underlying numbers yourself so your judgment is grounded in data, then pressure test that view against the 3 key rewards.
Looking For More Investment Ideas Beyond Dorman Products?
Do not stop with one aftermarket story. Use the Simply Wall St screener to line up fresh ideas now, before the best setups shift away.
- Target dependable cash generators by reviewing companies with strong payouts and sturdy fundamentals through the 6 dividend fortresses.
- Hunt for quality at a discount by scanning the 34 high quality undervalued stocks that pair solid cash flows with robust balance sheets.
- Protect your downside by focusing on the 29 resilient stocks with low risk scores that combine financial resilience with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com