
Is EZCORP (EZPW) Trading At A Premium Or Near Fair Value?
EZCORP has delivered a powerful 5 year share price run, and that kind of performance naturally raises a question for anyone looking at the stock today. Is the current valuation really supported by the returns the business earns on the capital it puts to work?
- Over the past 5 years, EZCORP has returned 240.1%, which puts real weight on whether those gains line up with the returns it generates on its invested capital.
- The company’s pawn lending model, which recycles capital through short duration loans and inventory, can have a big influence on how efficiently each dollar invested turns into long term value for shareholders.
- Prefer to judge EZCORP on earnings? See why EZCORP's 10.2x P/E tells a different valuation story.
The stock’s next move may depend on whether the strength of EZCORP’s returns on capital genuinely supports the price investors are paying today.
If you are weighing whether EZCORP’s 240.1% five year return is really supported by the returns it earns on its capital, a focused stock screen can give helpful context through 34 high quality undervalued stocks.
Is EZCORP Fairly Priced on Excess Returns?
The Excess Returns model looks at how efficiently EZCORP turns each dollar of shareholder equity into profit above its funding cost. For EZCORP, the framework starts with a Book Value of $19.43 per share and a Stable Book Value estimate of $19.00 per share, both anchored to analyst expectations for the balance sheet. That is paired with a Stable EPS of $2.00 per share, based on the median Return on Equity from the past 5 years, which helps translate accounting capital into an earnings stream.
What ties it together is the relationship between profitability and required return. An Average Return on Equity of 10.52% converts into a cost of equity of $1.65 per share and an Excess Return of $0.35 per share, implying the business is modeled to earn more on its equity base than investors are assumed to require. With the Excess Returns projections putting EZCORP's estimated intrinsic value broadly in line with the current share price of $27.55, the model suggests the stock is roughly tracking the earnings power implied by its capital base. Find out what EZCORP could be worth using our Excess Returns estimate.
The EZCORP Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off for EZCORP. They describe which paths for growth, margins and earnings would need to occur for the stock to end up meaningfully higher or lower than today’s level, and each one links a fair value estimate to a clear storyline about EZCORP's potential catalysts and key risks so you can track over time which version of events is actually taking shape on the Community page.
One of the top narratives on EZCORP: 39% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"Growing disclosure and internal focus on core pawn revenue and gross profit, separate from scrap, can shift how investors value EZCORP toward the recurring pawn engine..."
Discover why this Narrative puts EZCORP at 39% undervalued.
EZCORP’s price is only one piece of the decision
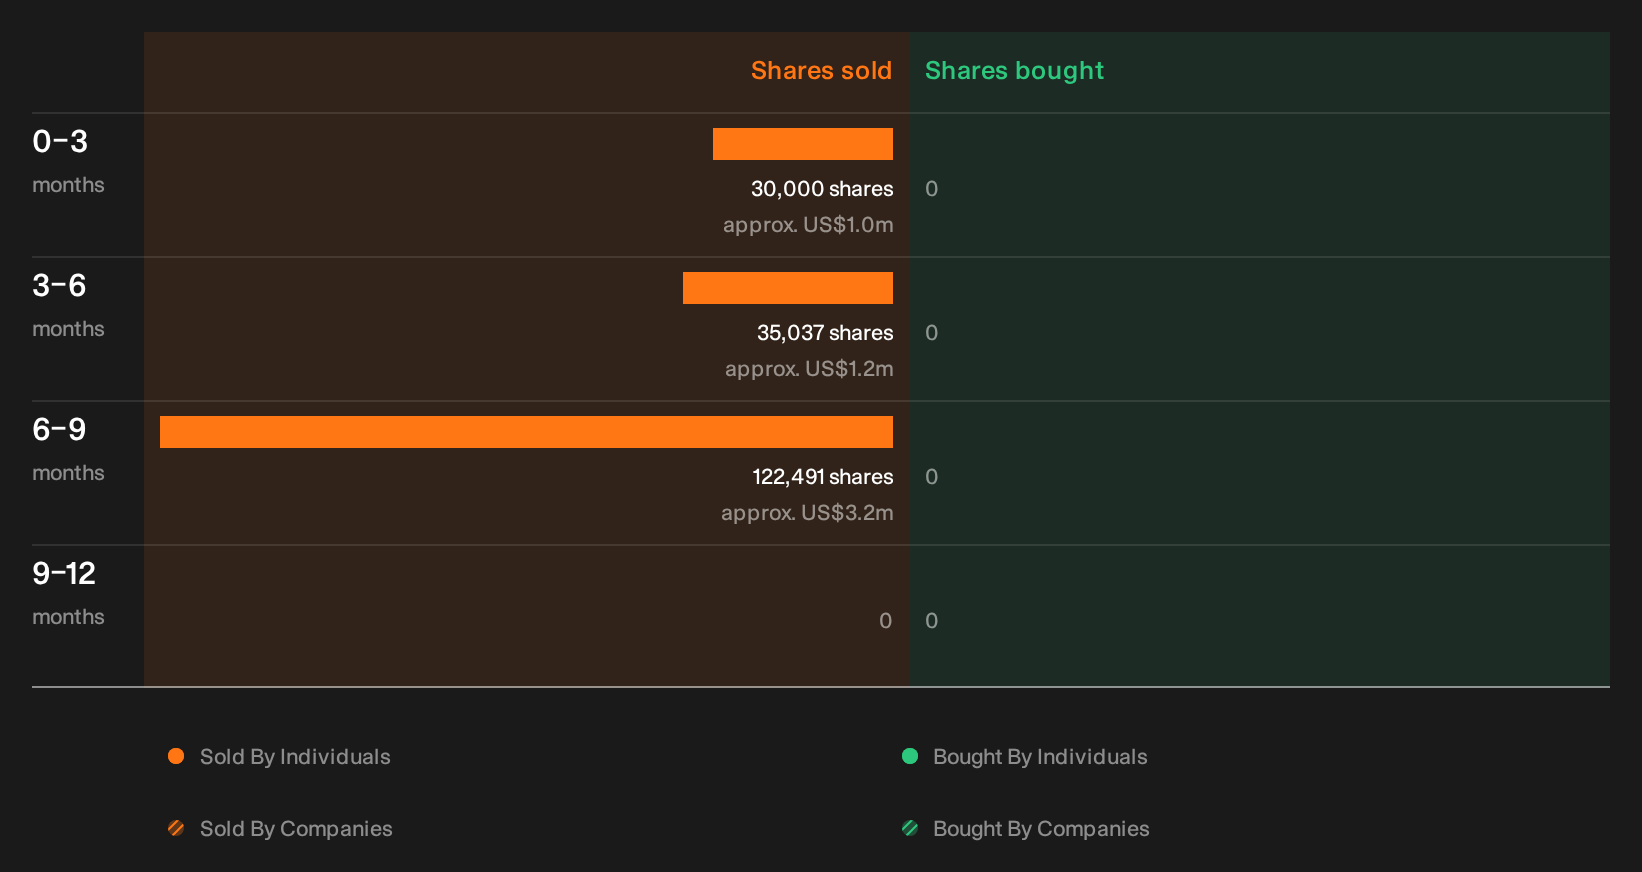
Before you treat EZCORP’s current valuation as the full story, it is worth knowing that Simply Wall St’s checks have recently highlighted insider share sales, with the individuals, volumes and possible interpretations left for you to review. See the recent insider selling flagged for EZCORP.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com