
What Prysmian Doubters Missed
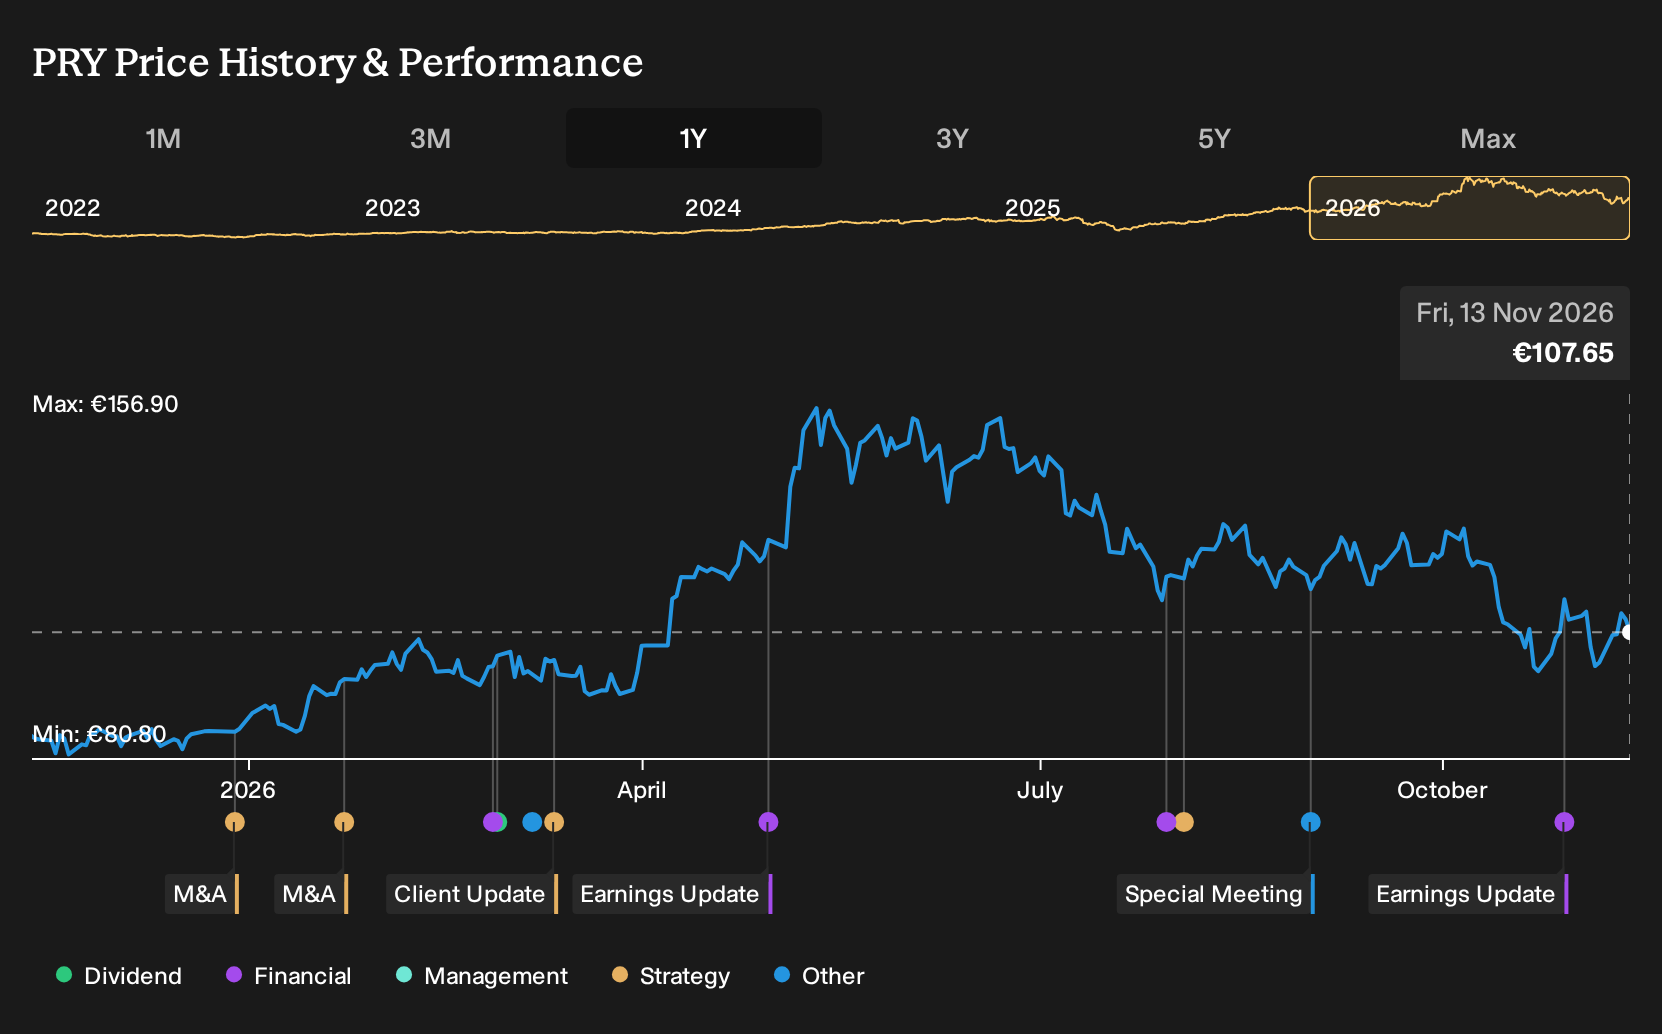
If Prysmian was on your watchlist rather than in your portfolio, the result may feel expensive. Holding Prysmian over the past year would have returned 29.0%, including dividends. That move sat against a backdrop of analysts debating whether high-tech cables for grids and data centers could really support stronger margins and sustained demand. The key question now is whether that profitability story was already visible in 2025, or only clear after the deal headlines arrived.
This theme extends beyond Prysmian. See which of 44 power grid technology and infrastructure stocks may still merit a closer look.
The Two Prysmian Stories Investors Had To Weigh
The shares cost €84.48 at the start of the period, and Prysmian sat between two very different but reasonable stories about where the business could go.
On the optimistic side, one view saw high tech cables powering electrification and data center buildout, with a Fair Value of €102. This was treated as the price those bullish assumptions might justify, backed by expectations of 6.9% annual revenue growth and profit margins rising from 3.9% to 7.4%.
The more cautious narrative put Fair Value at €79.13. This was again an implied price from its own model, built on 5.5% yearly revenue growth and margins reaching 6.2%, while highlighting execution and tariff risks around U.S. focused expansion.
What The Evidence Did To The Prysmian Argument
Prysmian then signed a long term €5.5b supply deal with Molex and committed over €1b to expand fiber capacity, which backed the bullish view that data center cables could support richer margins and steadier demand. The later decision to buy Atkore for about $3.8b gave the more cautious case fresh questions on execution and balance sheet risk. Overall, the evidence cut both ways.
The key assumption investors had to test was whether Prysmian could turn AI driven data center demand into durable, higher quality earnings. In any similar story, investors would typically track long term contracts, capacity commitments and acquisition terms against the original margin and cash flow claims.
What Prysmian's Price Now Assumes
Prysmian shares now trade at €108, after a 29.0% gain over the past year. The analyst consensus Narrative on Simply Wall St sees Fair Value sitting above that level, based on how much future contract delivery is already baked into expectations.
That Narrative leans on AI related fiber, grid work and Atkore. It argues that today’s price still does not fully credit successful integration of recent acquisitions and the cash flow those deals are expected to support.
"The main requirement is successful execution on large optical and grid contracts and on integrating Encore Wire and Atkore so that planned margins, synergies and free cash flow are reflected in future results."
One Narrative disagrees with today's price. → See where this Narrative says Prysmian should trade
Looking Beyond Prysmian's Cables
Prysmian is tied to grids and data lines on the ground. You could also look at what happens much higher up.
Every crop image, logistics ping and weather update from orbit needs a ride into space. One specialist focuses on building both those rides and the hardware they carry.
By combining launch capability with satellite manufacturing, this business tries to capture more of that space backbone. It aims to be useful whether customers want images, connectivity or precise positioning.
If that backbone grows, the role of a vertically integrated launch and satellite supplier could change again. The interesting part is how much value might accrue there before it reaches the ground.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 59% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com