
Hormel (HRL) Stock Looks Fairly Valued After Its 38% Fall
Hormel Foods has seen its share price fall 38.0% over the past 5 years, even though the past month brought a modest rebound, which raises a pointed question about what investors are currently paying for its earnings stream. With that kind of long term performance in the rear-view mirror, you need to ask whether today's valuation is being driven more by recent price action or by the profits the business is actually generating.
- A 38.0% decline over 5 years puts long term holders under pressure and makes the current price level more dependent on how resilient Hormel Foods' earnings power really is.
- The group relies heavily on converting branded food sales into consistent profit margins and cash generation, so any shift in costs or pricing power can feed straight into what investors might be willing to pay for each dollar of earnings.
- Your read on Hormel Foods is one view; the desks covering it have another. See what analysts think Hormel Foods's shares could be worth.
The issue now is whether Hormel Foods' current share price is reasonably aligned with its earnings when set against the Fair Ratio benchmark.
If you are questioning whether Hormel Foods' current P/E makes sense after a 38.0% slide over 5 years, you may want to compare it with 34 high quality undervalued stocks.
Where Does Hormel Foods Sit on Earnings?
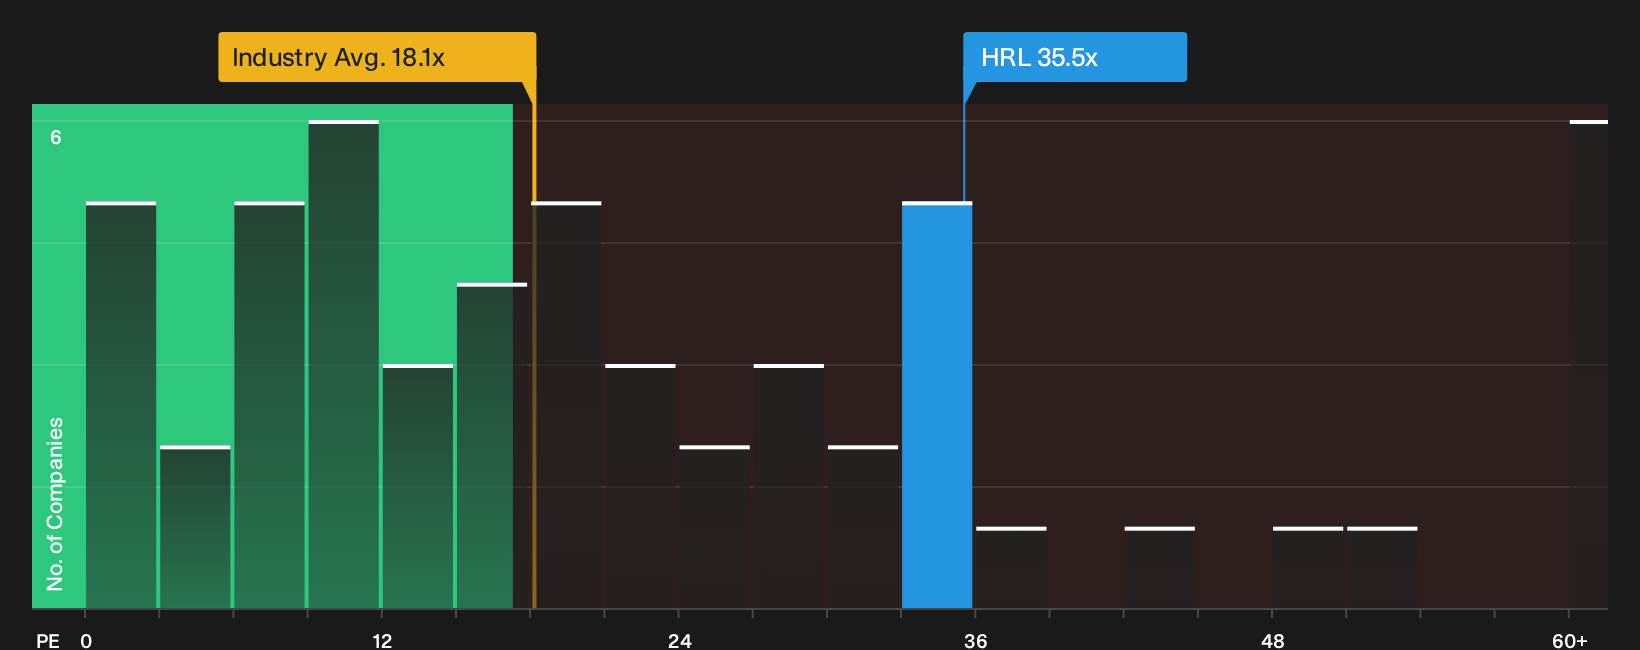
The P/E ratio suits Hormel Foods because investors commonly look at earnings power for mature branded food groups. Hormel Foods currently trades on a P/E of 35.5x, compared with about 18.1x for the wider Food industry and roughly 29.8x for its peer set, so the shares carry a clear premium to both broad sector and closer comparables.
A Fair Ratio model that blends Hormel Foods' growth profile, profitability, size and risk points to a level not far from where the stock trades today. This makes the current P/E look about right rather than obviously stretched or cheap on this framework. For you as a shareholder or potential buyer, the key question is whether the earnings quality and stability you see in Hormel Foods is strong enough to justify paying more per dollar of profit than the typical Food stock. Explore the numbers behind Hormel Foods's P/E valuation.
The Hormel Foods Narrative: What Would Justify Today's Price?
Hormel Foods' current valuation puzzle sets up the role of Simply Wall St Narratives, which spell out in plain terms what kind of future growth, margins and earnings path would need to play out for the stock to trade meaningfully higher or lower than today. Each narrative works as a scenario with its own fair value assumptions, so you can see the moving parts and later compare those expectations with the company’s reported results on the Community page.
One of the top narratives on Hormel Foods: 13% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Hormel Foods successfully executes its portfolio simplification and Brakebush integration, with higher-margin foodservice and value-added protein offsetting retail volume pressure and cost headwinds..."
Discover why this Narrative puts Hormel Foods at 13% undervalued.
Before acting on Hormel Foods' valuation, there is one more angle to check
Numbers only tell part of the story for Hormel Foods, because the people setting priorities, allocating capital and rewarding themselves can reshape the whole investment case over time. See who runs Hormel Foods and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com